Sonida Senior Living owns 153 senior housing properties after a March 2026 merger doubled its scale, with aging-driven demand and tight…
S Value Don't Lie 13h ago 3 clicks
Ondas reported $167.5 million in Q3 revenue but spent $562 million of cash, halved gross margin and fell below its $6 stop level.
BL Cestrian Capital Research 15h ago 3 clicks
Offshore Radar maps 160-plus listed offshore rigs, contracts, day rates and uncontracted capacity through 2029.
S Cannibal Stocks 15h ago 6 clicks
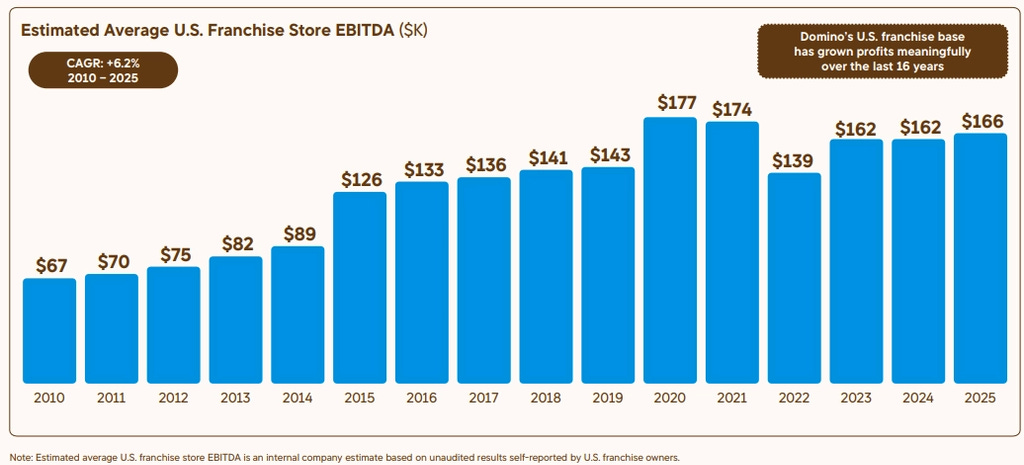
Domino’s built PULSE, online ordering and Pizza Tracker into a delivery machine, driving 10% annual global retail sales growth after its…
S scuttleblurb 17h ago 3 clicks
Nubank and MercadoLibre update target prices as Brazil’s 9% real rates, weaker currency and tighter credit favor their cost advantages and…
S Jimmy's Journal 19h ago 3 clicks
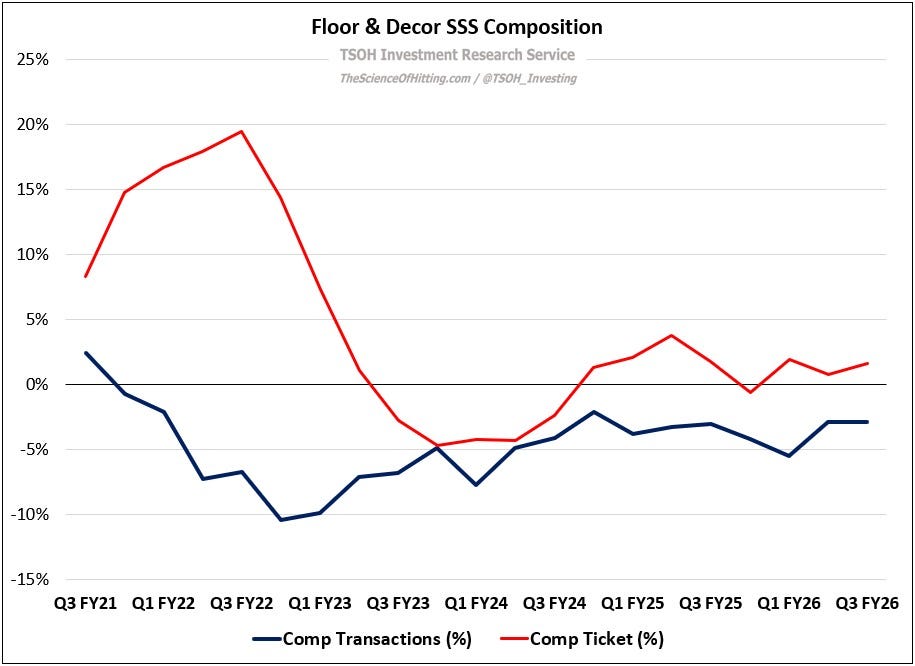
Floor & Decor has logged 20 straight quarters of comp transaction declines, with Q3 quarter-to-date same-store sales down about 3.8% as…
S TSOH Investment Research 19h ago 4 clicks
HCI Group grew Q3 revenue 13% and net income 27%, with $2 billion of invested assets driving investment income.
SA Given Mahlangu 21h ago 3 clicks TPG trades 20% below its average distributable-earnings multiple despite the fastest fee-related earnings growth among alternative…
S Capital Employed 29h ago 8 clicks
CDW CEO Chris Leahy says AI spending is entering a second wave focused on putting technology to work in everyday consumption.
BL The Technology Letter 31h ago 3 clicks
American Tower’s wireless network stayed operational during the FAA ground stop, while CoreSite lifted its 2026 data center revenue growth…
SA Brad Thomas 39h ago 3 clicks Intel’s custom ASIC business more than doubled last quarter as it pursues hyperscaler demand, AI accelerators and a stronger Intel Foundry.
S Chipstrat 41h ago 5 clicks
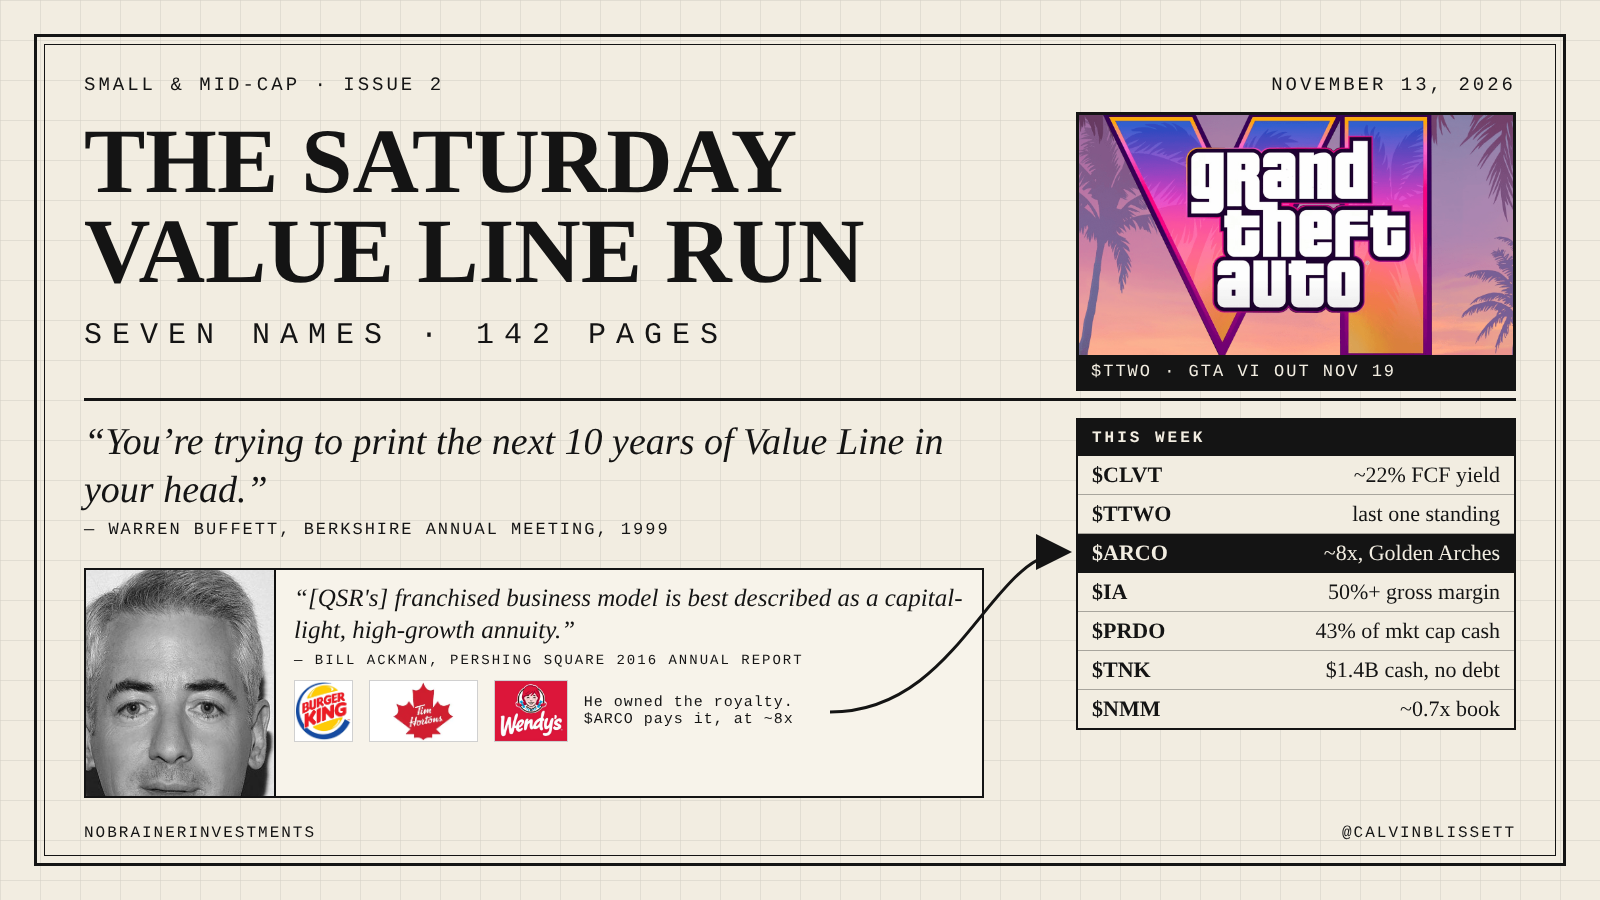
Clarivate, Take-Two and Arcos Dorados lead a seven-stock Value Line screen focused on debt paydown, GTA VI economics and Latin American…
S Calvin Blissett 41h ago 5 clicks
Net Lease Office Properties has distributed $24.19 per share, including a $1.50 special dividend, while liquidation risk centers on its…
SA Kingdom Capital 43h ago 1 click INTR · long Inter & Co, a Brazilian digital bank, grew net revenue 32% year over year while trading at 1.4 times tangible book and 7.9 times earnings.
BL Value Investors Club Aug 17 1 click
BL Clark Street Value Nov 14 6 clicks
BL Clark Street Value Nov 14 4 clicks
Brookfield trades at about 17 times trailing distributable earnings, while its 73% BAM stake accounts for $63 billion of its $94 billion…
SA Secret Compounders Nov 14 3 clicks JFrog CFO Ed Grabscheid says soaring AI usage is converting into larger customer deals after an upbeat earnings report.
BL The Technology Letter Nov 14 5 clicks
OTC Markets CEO Cromwell Coulson says the SEC’s proposed offering reforms could let OTCQX and OTCQB companies raise capital through…
YT The Monetary Matters Network Nov 14 5 clicks
Q3 updates cover Crocs, Entravision and Fiserv beats, coal and oil weakness, and Xerox’s sharp decline, testing the underlying cases for…
S Hidden Rock Capital's Newsletter Nov 14 5 clicks