QXO Inc Earnings Update: Q3 2026
QXO's Q3 sales rose 79% to $4.9 billion after TopBuild and Kodiak acquisitions, while acquisition debt lifted interest expense to $163 million and adjusted EPS fell.
QXO's Q3 sales rose 79% to $4.9 billion after TopBuild and Kodiak acquisitions, while acquisition debt lifted interest expense to $163 million and adjusted EPS fell.

@_99Paul99 I've been patiently waiting for it. Hopefully a deal for $LION comes in high enough to satisfy Feltheimer, Mnuchin and Rachesky.

What's wrong with $BSP ?
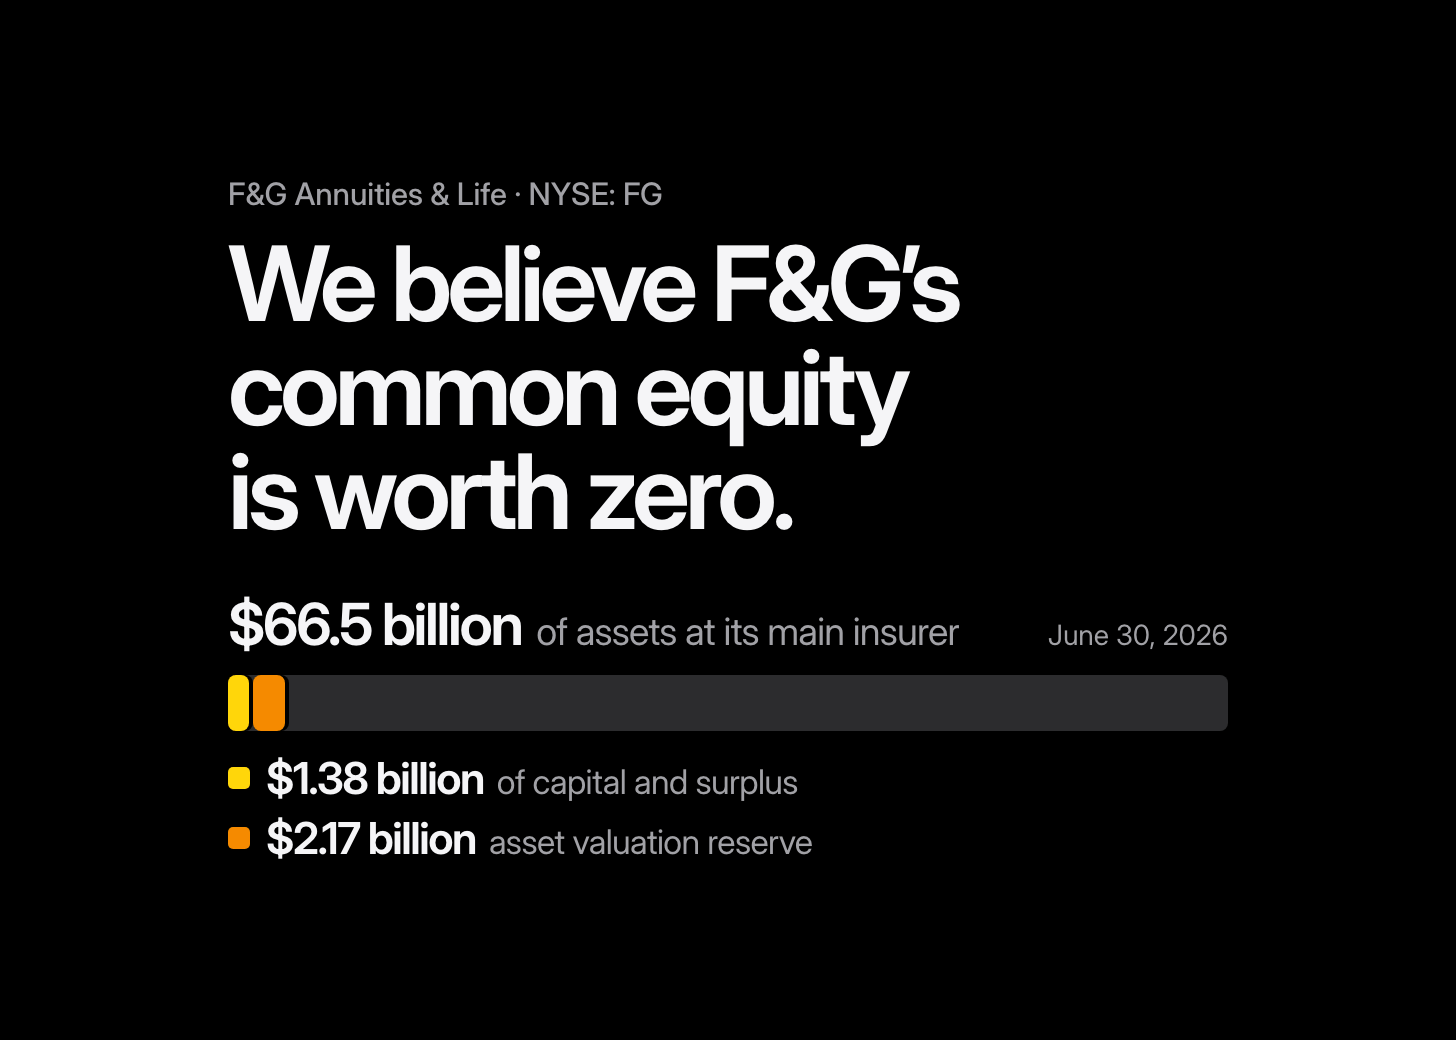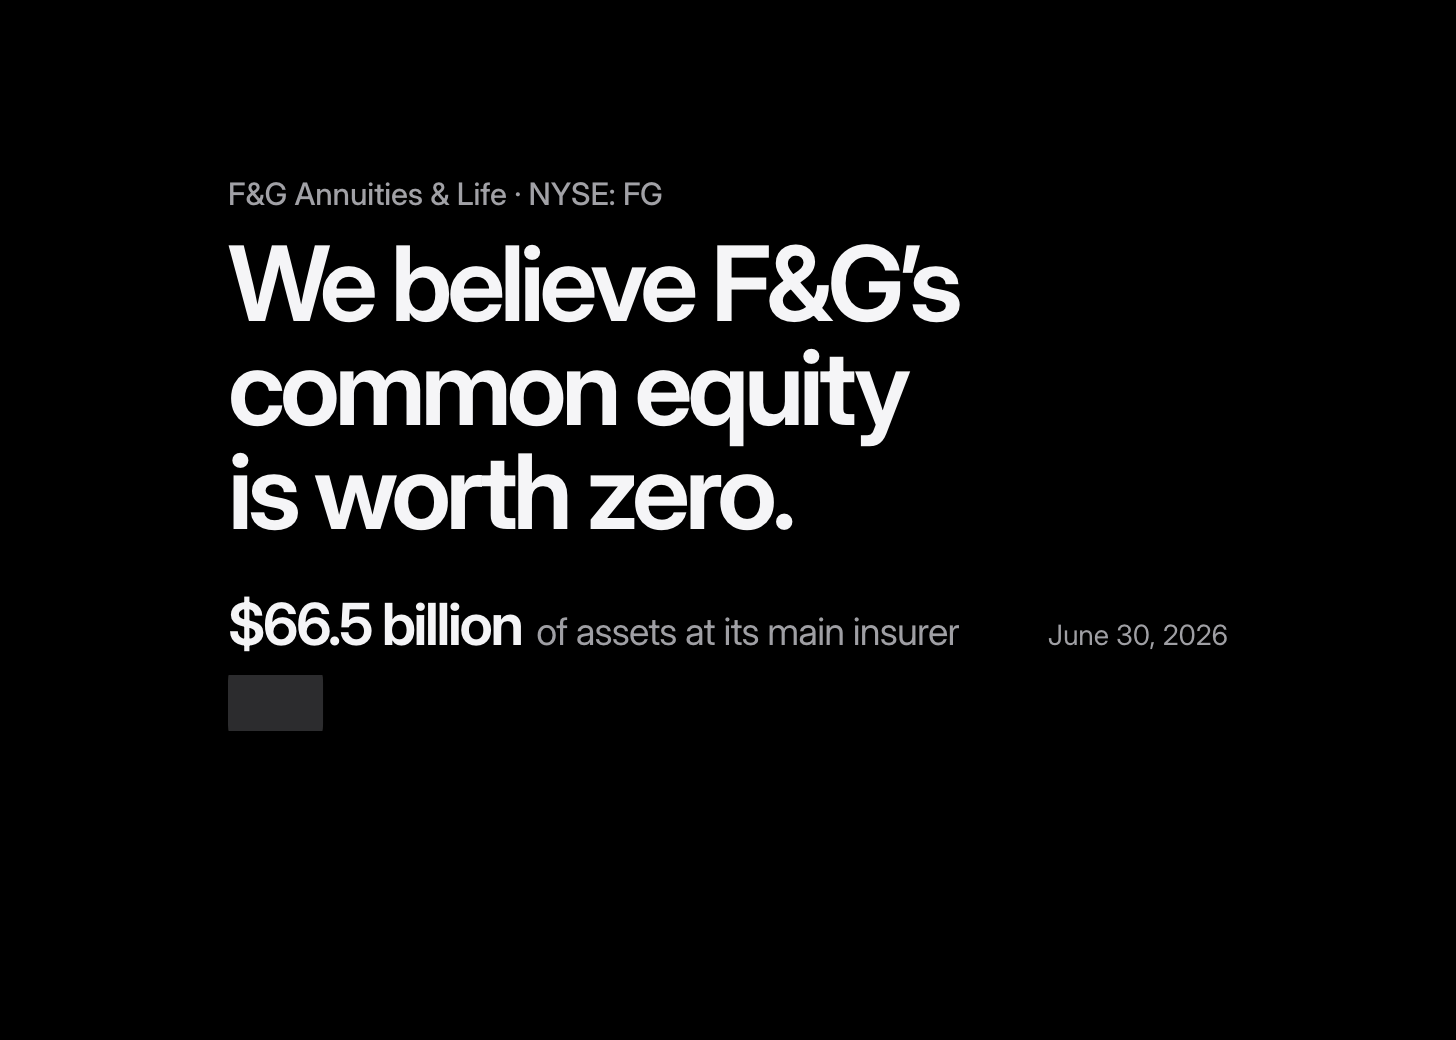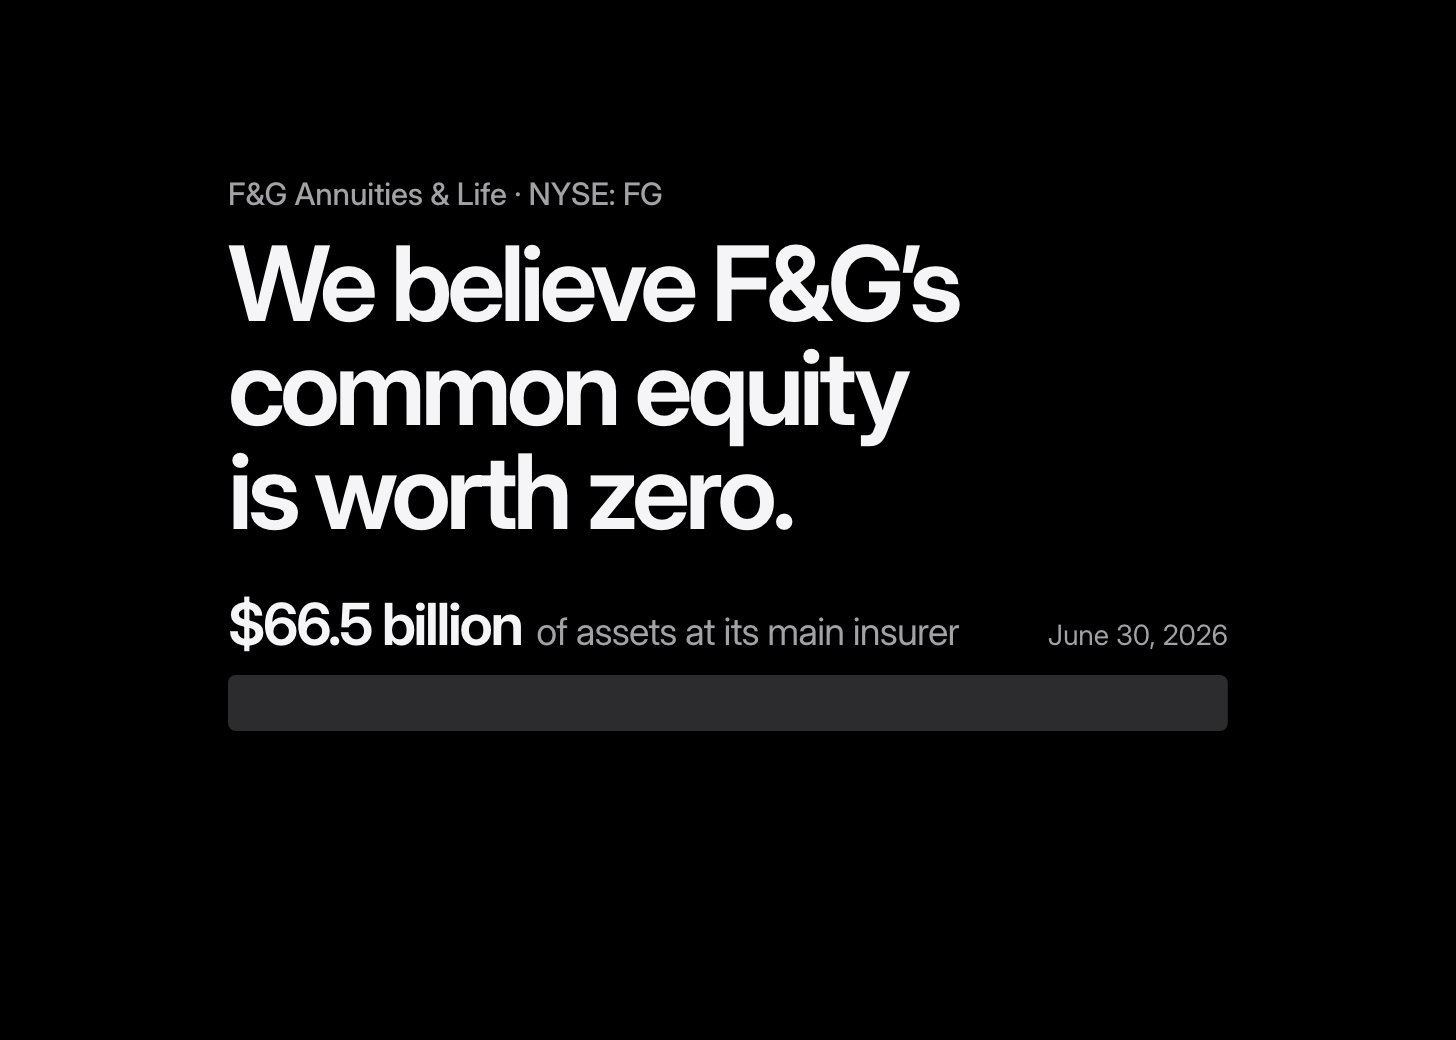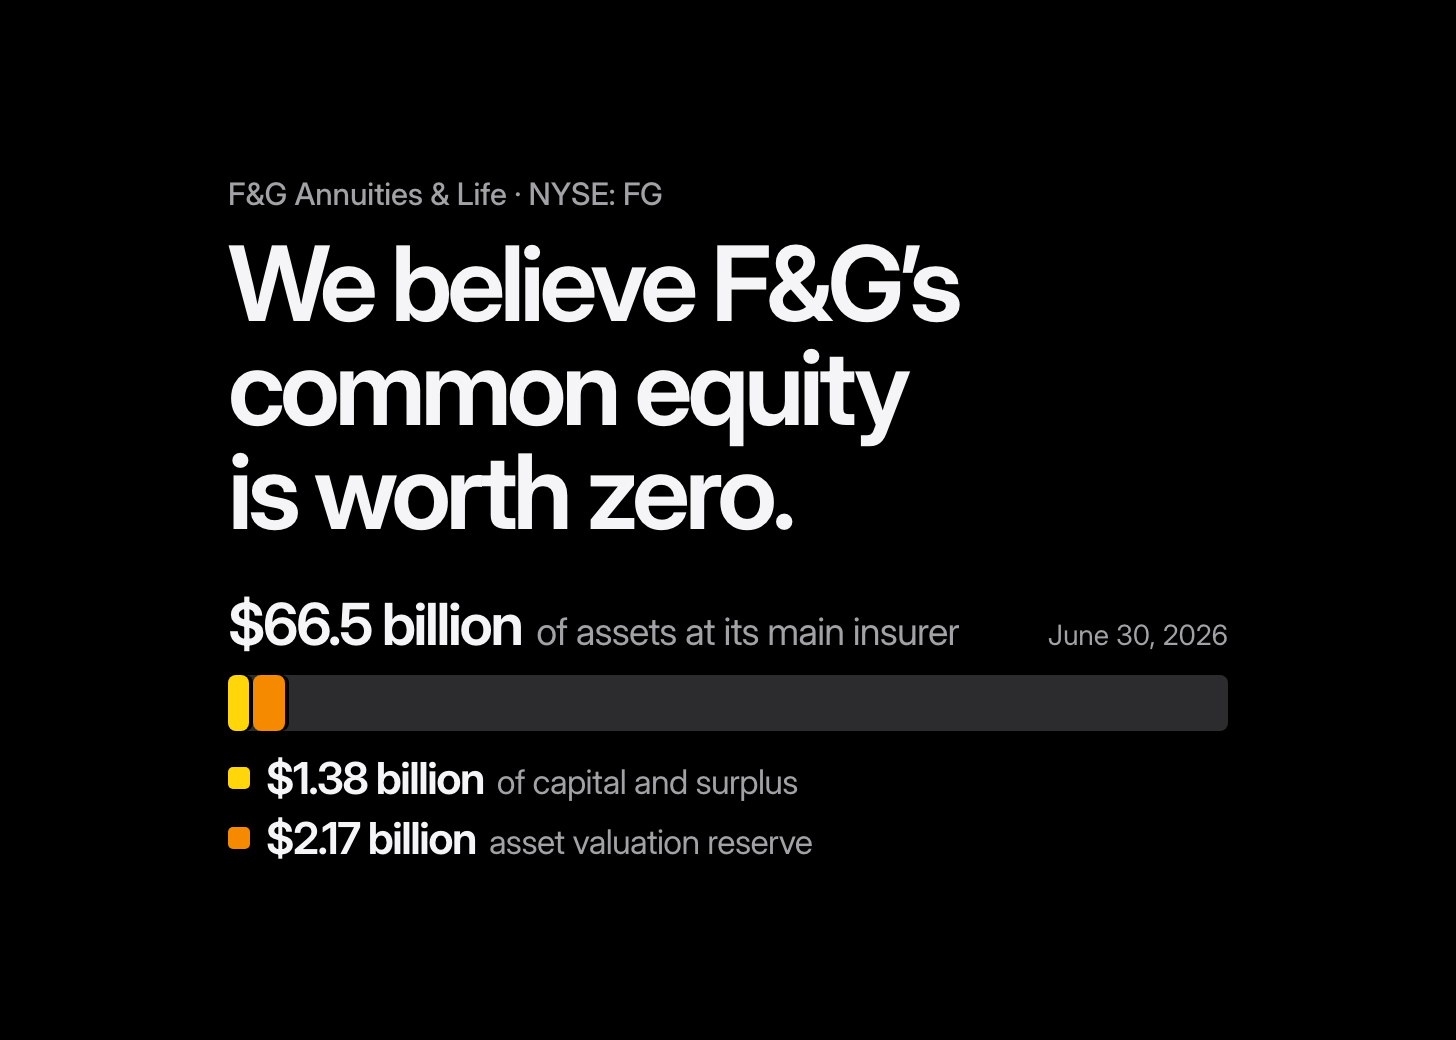
F&G’s main insurer held $66.5 billion of assets against $1.38 billion of statutory capital, while private credit, reinsurance dependence…
AutoNation’s new CEO Mike Manley brings Jeep and Fiat Chrysler experience after the dealer chain cycled through three leaders in 30 months.
Quanta Services' backlog rose 63% year over year to $64 billion as shares fell 30%, with AI and power-infrastructure demand driving revenue…
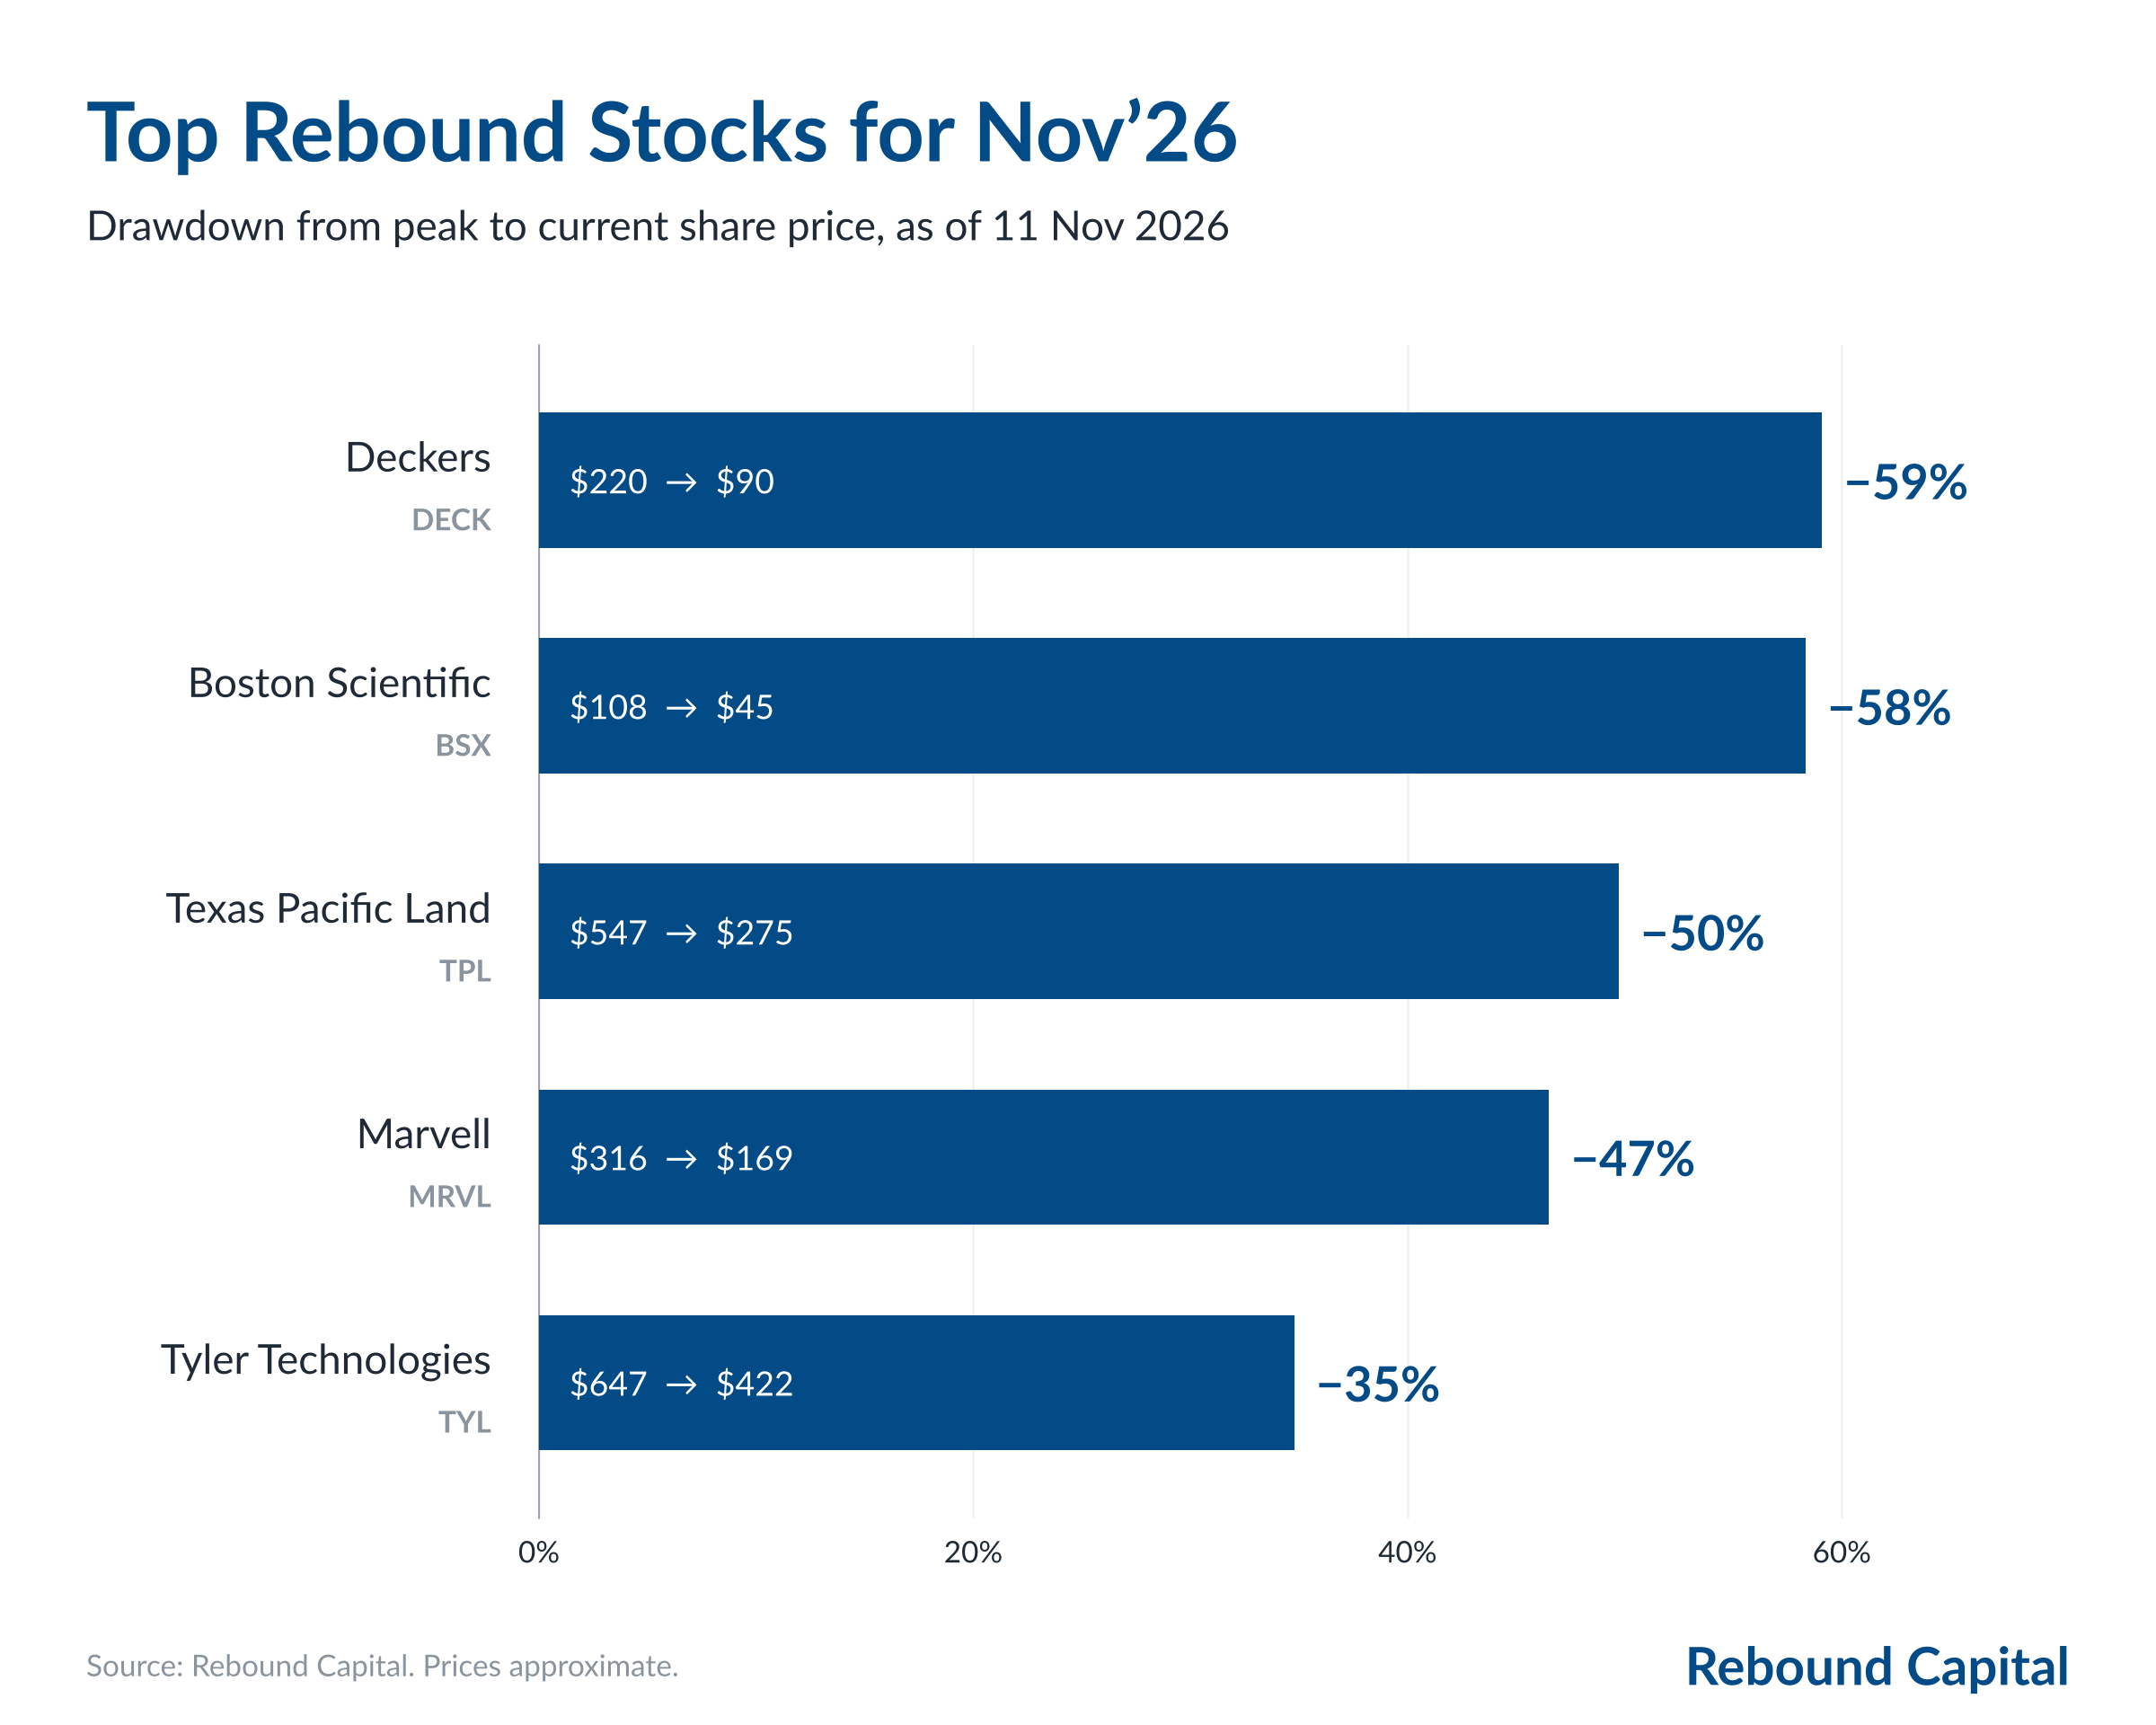
Texas Pacific Land's 50% selloff reflects faded data-center expectations, while its Permian royalty business generated $498 million of 2025…
International Seaways reported $291.4 million of Q3 adjusted net income and has 53% of Q4 booked at strong spot rates, supporting projected…
 Kevin Avroutskii 3 clicks
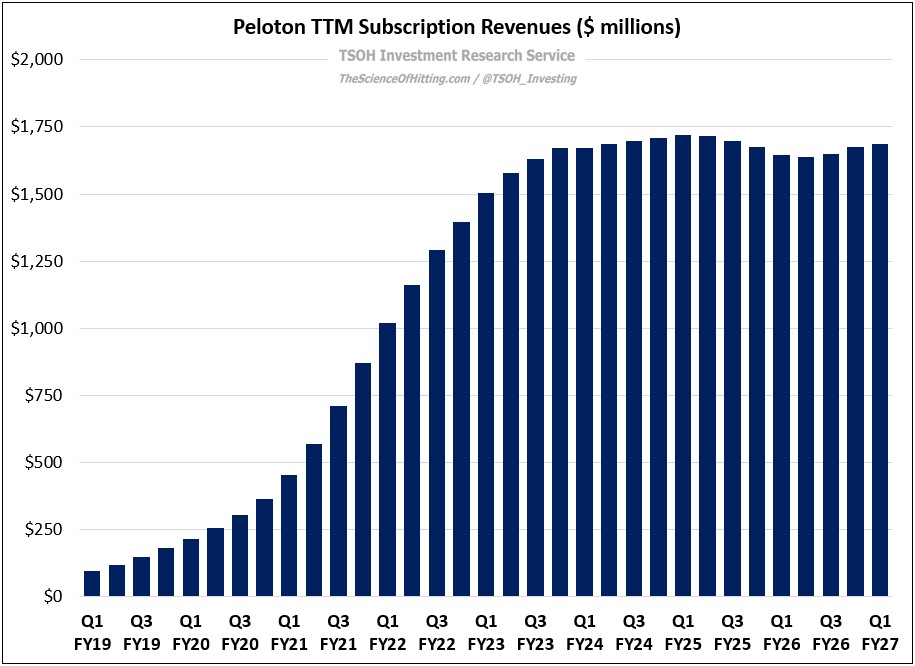
Peloton’s connected-fitness subscribers fell 9% year over year to 2.475 million, with another high-single-digit holiday decline forecast as…
DHT Holdings earned $1.68 per share in Q3 and projects Q4 EPS of $4.25, supporting a single-quarter dividend above 20% at projected spot…
 Melissa Tucker 4 clicks
Roblox CEO David Baszucki says AI can make game creation accessible to anyone, expanding Roblox’s role in discovery, cross-platform play…
Marvell’s all-stock acquisition of Lumentum targets optical supply, DSP synergies and AI data-center demand, while adding fab integration,…
Hewlett Packard Enterprise offers lower valuation and better memory-price downside protection than Dell, backed by higher-margin…
 Benjamin C. Barry 2 clicks
 MONOY · long
MonotaRO, traded as MONOY in the U.S. and 3064 in Japan, is a Japanese MRO distributor recommended as a long.
Coherent, Applied Optoelectronics and MaxLinear are pitched on AI optical-networking demand and earnings growth, alongside Bank of America,…
 The Undercovered Dozen 9 clicks
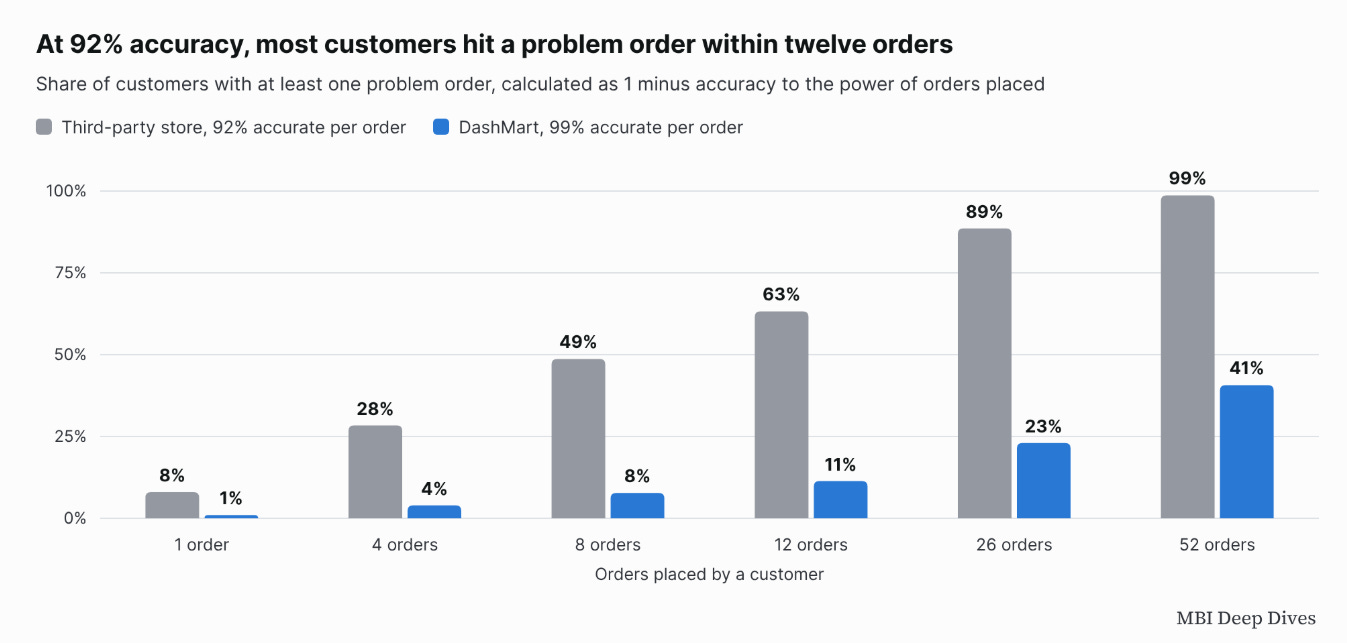
DoorDash’s $17 billion Instacart deal targets DashMart warehouse scale, where 99%+ order accuracy and faster delivery address the limits of…
WaterBridge grew Q3 revenue 16.9% year over year as Speedway Phase I lifted produced-water volumes, while pursuing large-scale data center…

Lumen was upgraded to Accumulate after Q3 revenue fell 12% to $2.7 billion, while strategic business revenue rose 10% and reached 55% of…
TransMedics targets multi-organ transplant growth through 2027 trials, OCS Kidney and European expansion after Q3 revenue rose 41% to $203…
 Conviction Queue

FICO is licensing mortgage scores directly to resellers, seeking pricing control as VantageScore competition and regulatory scrutiny…
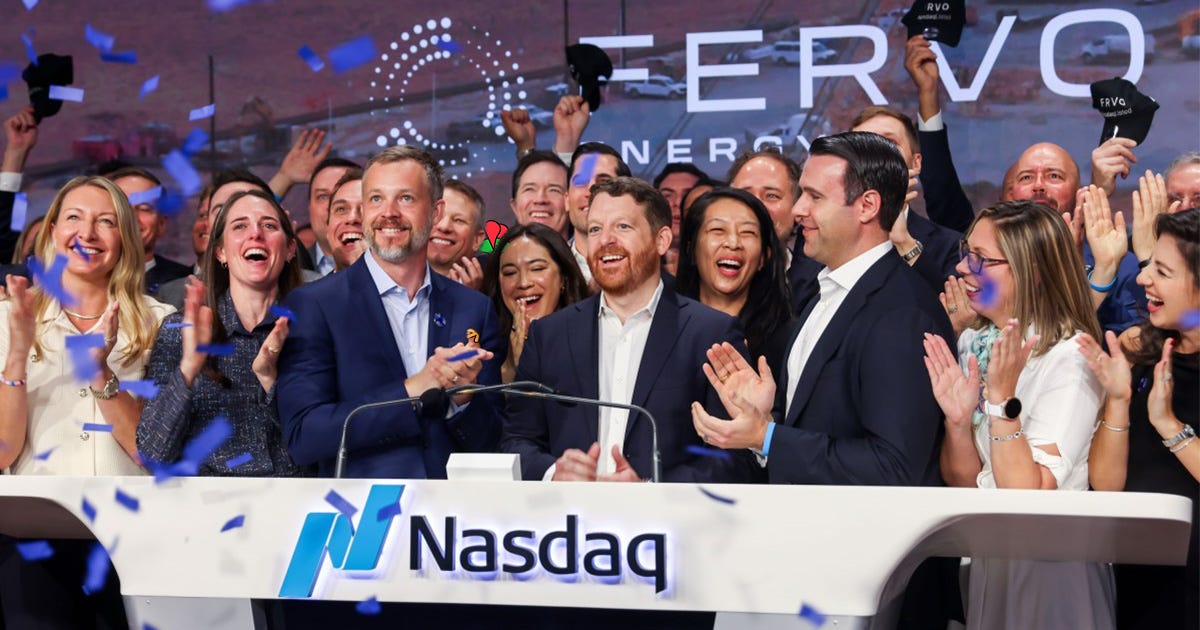
Fervo Energy raised $2 billion in its May IPO, then fell nearly 70% below issue price after a Morpheus short report, despite targeting 1 GW…
Adobe's compressed 10x non-GAAP EPS multiple reflects AI monetization and ARR-growth concerns; cash-secured puts at $210 or $200 target a…
 Tim Travis 4 clicks
Sea Ltd reported Q3 2026 revenue of $8.6 billion, up 43.4% year over year, while net income rose 34.0%.
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas Benjamin C. Barry
 Bernard Zambonin
 Blake Winiecki
 Capital Connoisseur
 Chetan Woodun
 Crimson And Gold Research
 Cypriot Invests
 Dane Bowler
 Daniel Bell
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian Kevin Avroutskii
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Louis Gerard
 Marc Gerstein Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Oakoff Investments
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Sanjay Swamy
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor The Undercovered Dozen Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.