Big Short Investor Explains How the AI Bubble Could Burst
Steve Eisman argues the AI boom rests on a handful of companies and hundreds of billions in infrastructure spending, risking recession and a sharp market correction.
Steve Eisman argues the AI boom rests on a handful of companies and hundreds of billions in infrastructure spending, risking recession and a sharp market correction.
Could’ve bought the 7.2% $PSA preferred with half of the money at the peak The annual dividend would be $1.0 mm which would be about $362k more than the current balance $1 mm per yr forever
*INSTACART EXPLORING A SALE: INFORMATION Sale could value $CART at $16 - $17B and they've had preliminary talks with $DASH and $UBER
$HAWK came public with MS and GS at the peak of the $PL and $SPCX space pump cycle. Investors likely bought the stock blindly without really understanding the business. Alas, the shareholder base is now transitioning into strong hands. I think those buyers will be rewarded.
BMO on $CENX: “Discussions centered on tariff uncertainty, Oklahoma smelter progress, current operations, improving free cash flow conversion & Hawesville monetization. Meanwhile, with CENX trading at 2.5x current spot-based EBITDA, valuation is compelling in our view.” 2.5X!
@trades021 I think Curtis at $BHB would like to be an acquirer. $LFGP is a logical target but Josephine will only sell if she can run a combined bank. Curtis has other targets. I’ve been a small holder only from back when Joe Murphy more thoughtfully ran this bank. He retired in 2013.
Dana is combining with Eaton’s Mobility unit via a 1Q27 Reverse Morris Trust after selling a division, delevering and accelerating buybacks.
 Daniel Bell 1 click
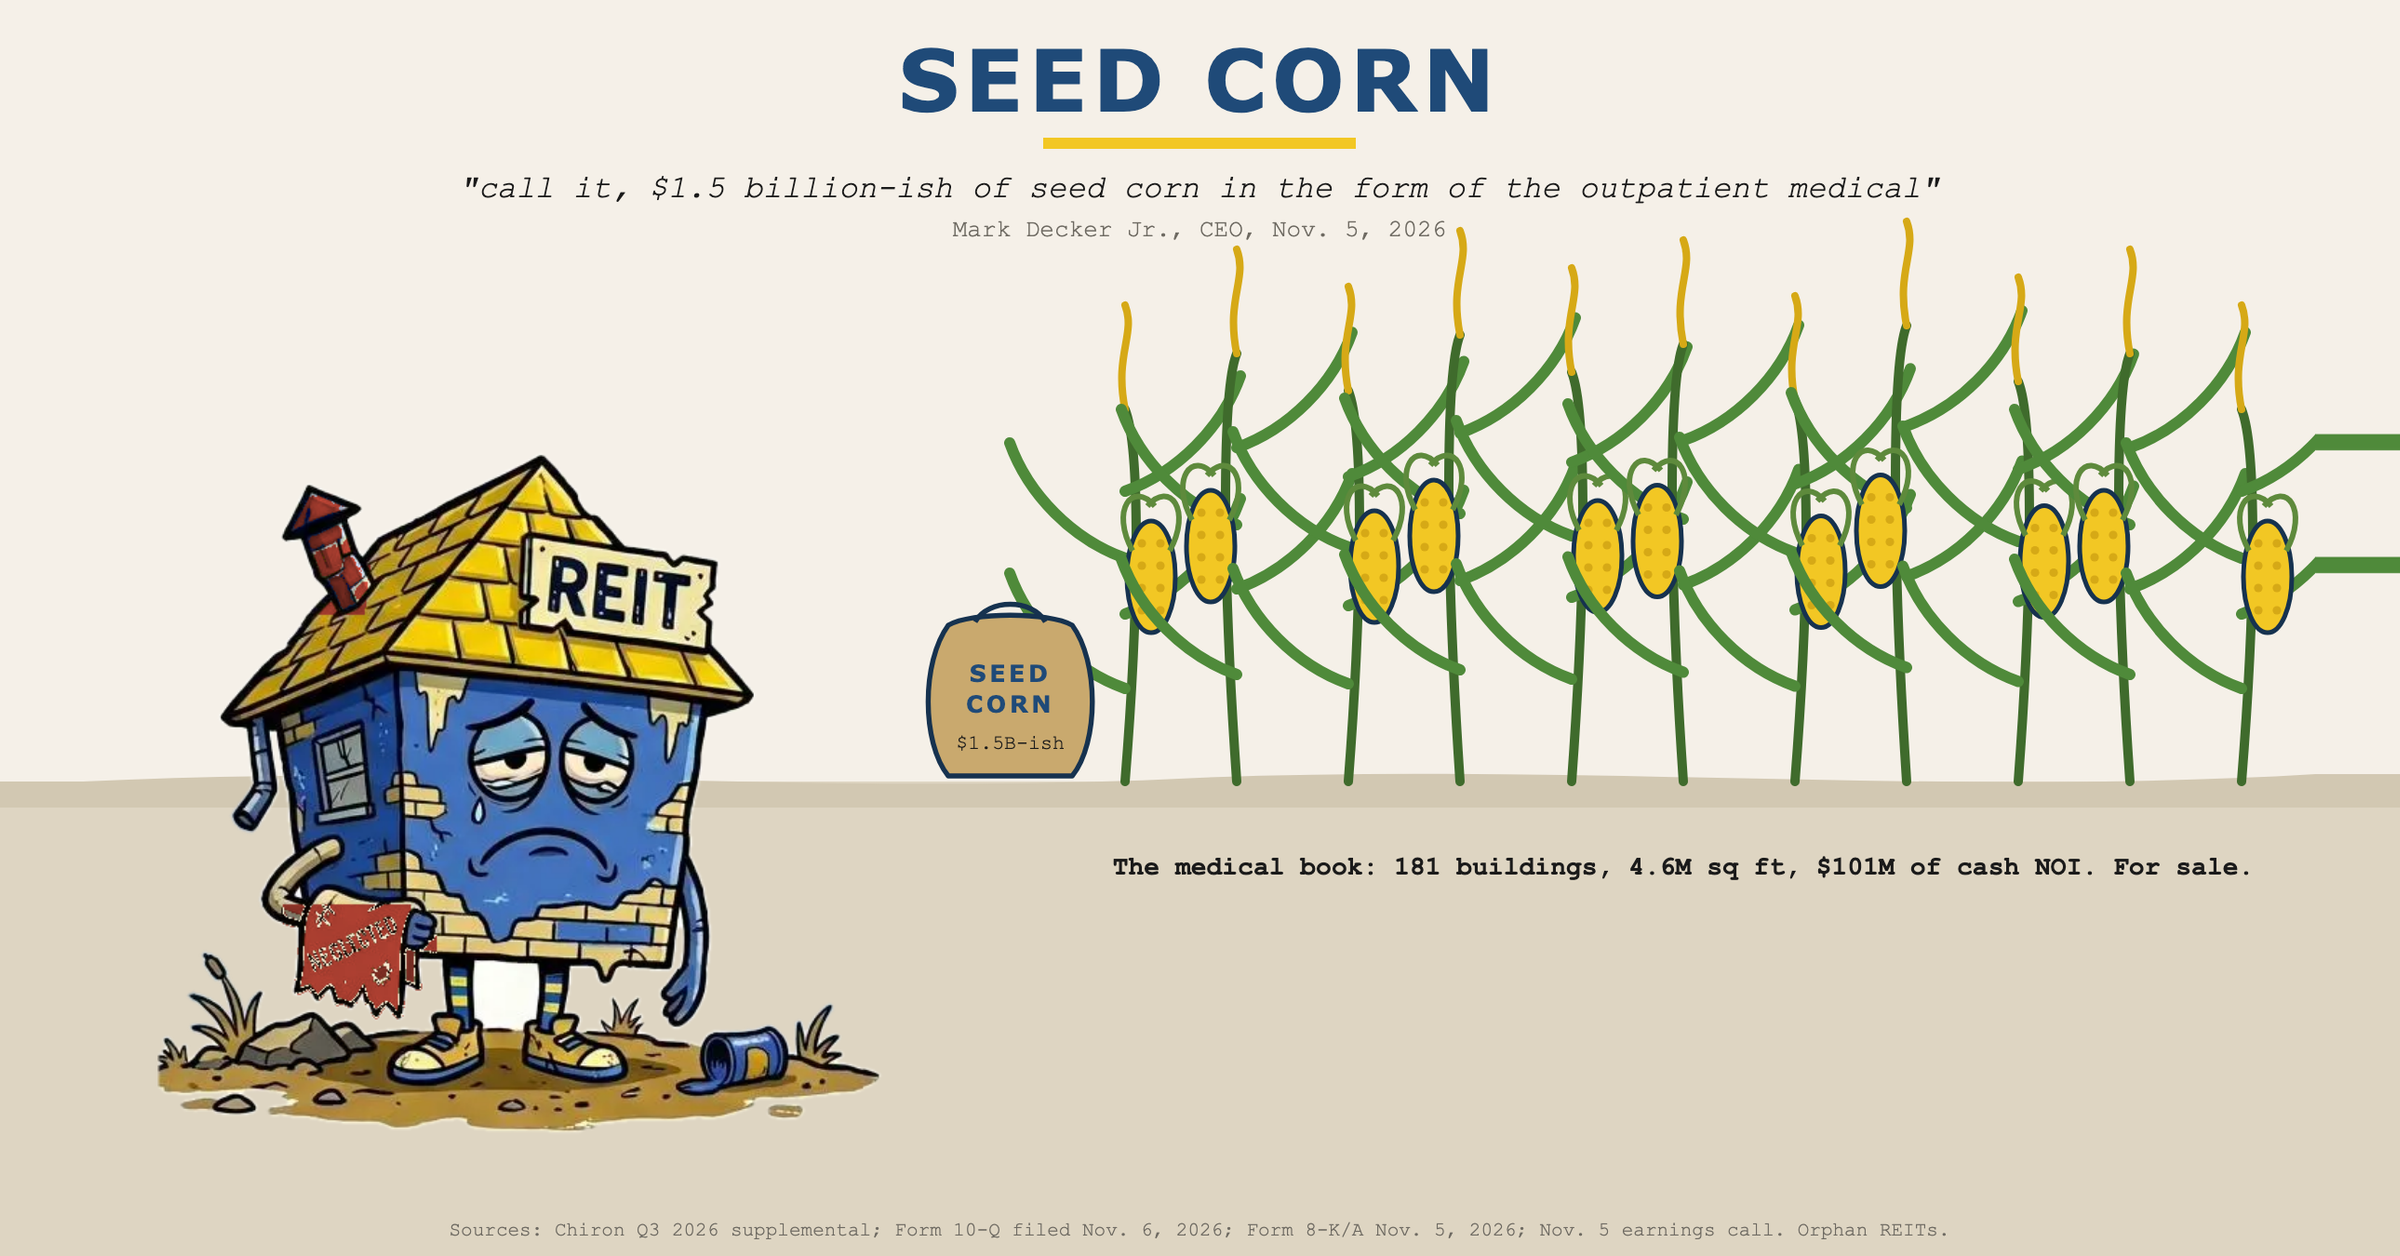
Chiron’s failed $49 million Beaumont sale and $178 million Pinnacle acquisition leave XRN with $70 million of liquidity and medical-office…
Sterling’s $4.1 billion backlog faces Texas permitting risk after a governor proposed a moratorium, while Connexion, Capital Asset Planning…
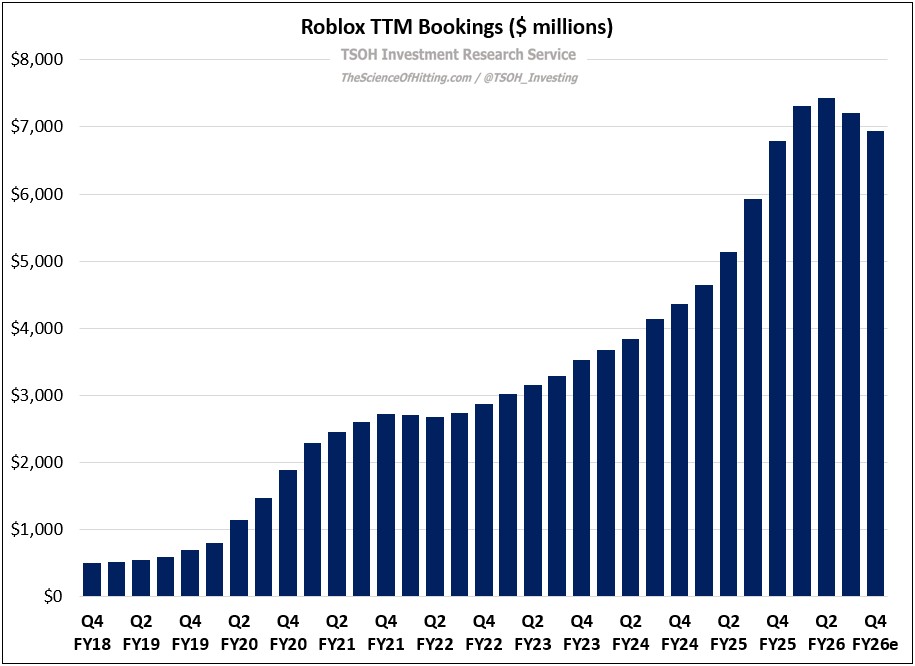
Roblox’s Q3 FY26 DAUs fell year over year for the first time, while bookings declined 12% to $1.7 billion.
Nextracker's $6 billion order book supports cross-selling battery storage and inverters, now 22% of revenue, though acquisition-led growth…
 Investor Overview 2 clicks
DoorDash and Google.
 Crimson And Gold Research 2 clicks
Blue Dolphin Energy trades near 1.3 times earnings as its Texas refinery benefits from diesel shortages, with projected 2026 EBITDA of $111…
Diamond Estates converts $4.7 million of Lassonde debentures at a 69% premium, cutting debt to $10.9 million and raising Lassonde ownership…
 FND · long
Floor & Decor operates 281 warehouse-format stores selling hard-surface flooring and accessories nationwide.
Vicor’s Federal Circuit hearing put Foxconn’s disputed patent license under pressure, reinforcing its AI server royalty model and licensing…
Moody’s ratings business faces potential deceleration, while AI-related debt issuance and anti-data-center politics pose less risk than…
IREN has fallen 71% despite AI Cloud revenue rising from $7.3 million to $200 million quarterly and more than $20 billion in contracted…
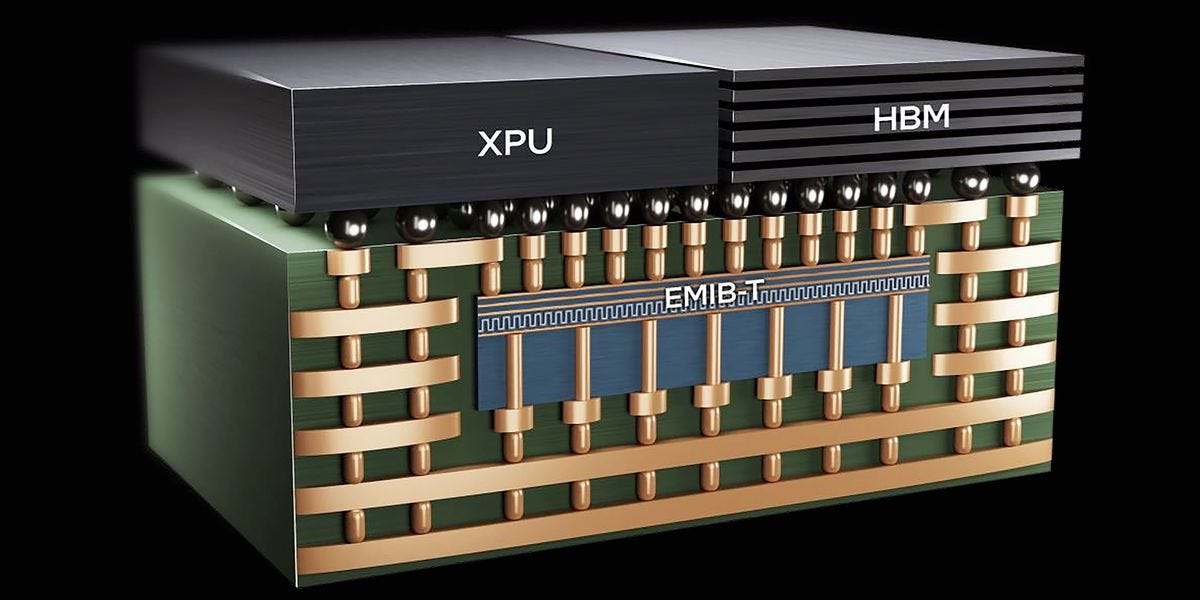
Intel’s EMIB-T, glass-core roadmap and 2027 ABF substrate supply outlook are the focus of an expert call.
Ouster grew Q3 revenue 50% to $59.3 million, shipped 27,000 sensors and guided Q4 revenue to $61 million to $64 million while posting a…
Floor & Decor’s 3Q26 sales rose 3% while comparable sales fell 1.4%; it cut 2027 openings to 10-15 as high mortgage rates pressure…

Floor & Decor's 3Q26 sales rose 3% while comparable sales fell 1.4%; it slowed 2027 openings to 10-15 as high mortgage rates pressure…
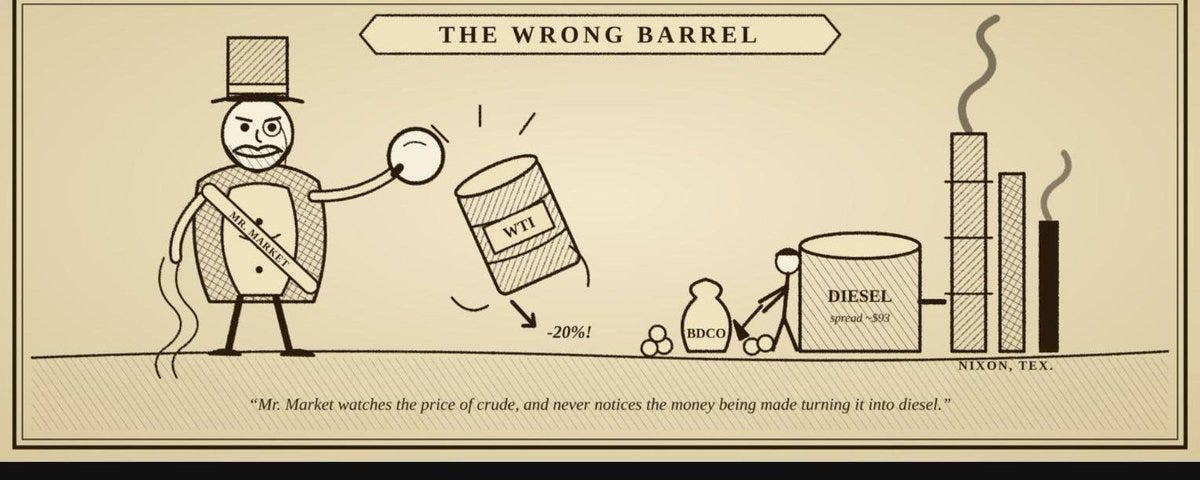
Blue Dolphin’s 15,000-barrel-per-day Texas refinery earned $2.18 per share in first-half 2026 as diesel shortages widened crack spreads,…
Blackbaud CEO says AI will be a tailwind for the nonprofit software and services provider.
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur Crimson And Gold Research
 Cypriot Invests
 Dane Bowler Daniel Bell
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.