Diageo: First Quarter on Dave’s Plan Wasn’t Too Drastic
Diageo’s first quarter under CEO Dave Lewis showed modest price changes and regional growth outside North America, supporting a turnaround without drastic further cuts.
Diageo’s first quarter under CEO Dave Lewis showed modest price changes and regional growth outside North America, supporting a turnaround without drastic further cuts.
random $GLD and $LQD (IG corp) are both in a 24.88% drawdown
@cannibalstocks $DDS
@Pickle_Trader Anything’s possible in financial markets. An 80-90% drop in $BE is highly unlikely but i accept it as a possible outcome. Investing is a game of probabilities not certainties.
Decent week for HY, driven by rally in rates and beta outperformance. CCCs (heavily bifurcated market) still at 1,000bps+. High yield sitting at 8.21% YTW; spreads near YTD wides $HYG $JNK https://t.co/rQtoY0inUY
Brookfield Asset Management Fundraises $25 Billion in Quarter, Led by Infrastructure Strategies $BN https://t.co/EUs4qHwmvW
Marvell Technology’s Google custom-silicon win and upgraded long-term guidance lift its fair value to $187.35 standalone, or $199.48…
 Zbigniew Budzinski, CFA

Steve Eisman links a Democratic midterm sweep and CoreWeave concerns to an AI narrative shift as the S&P 500 fell 4.4% and Nasdaq 5.5%.
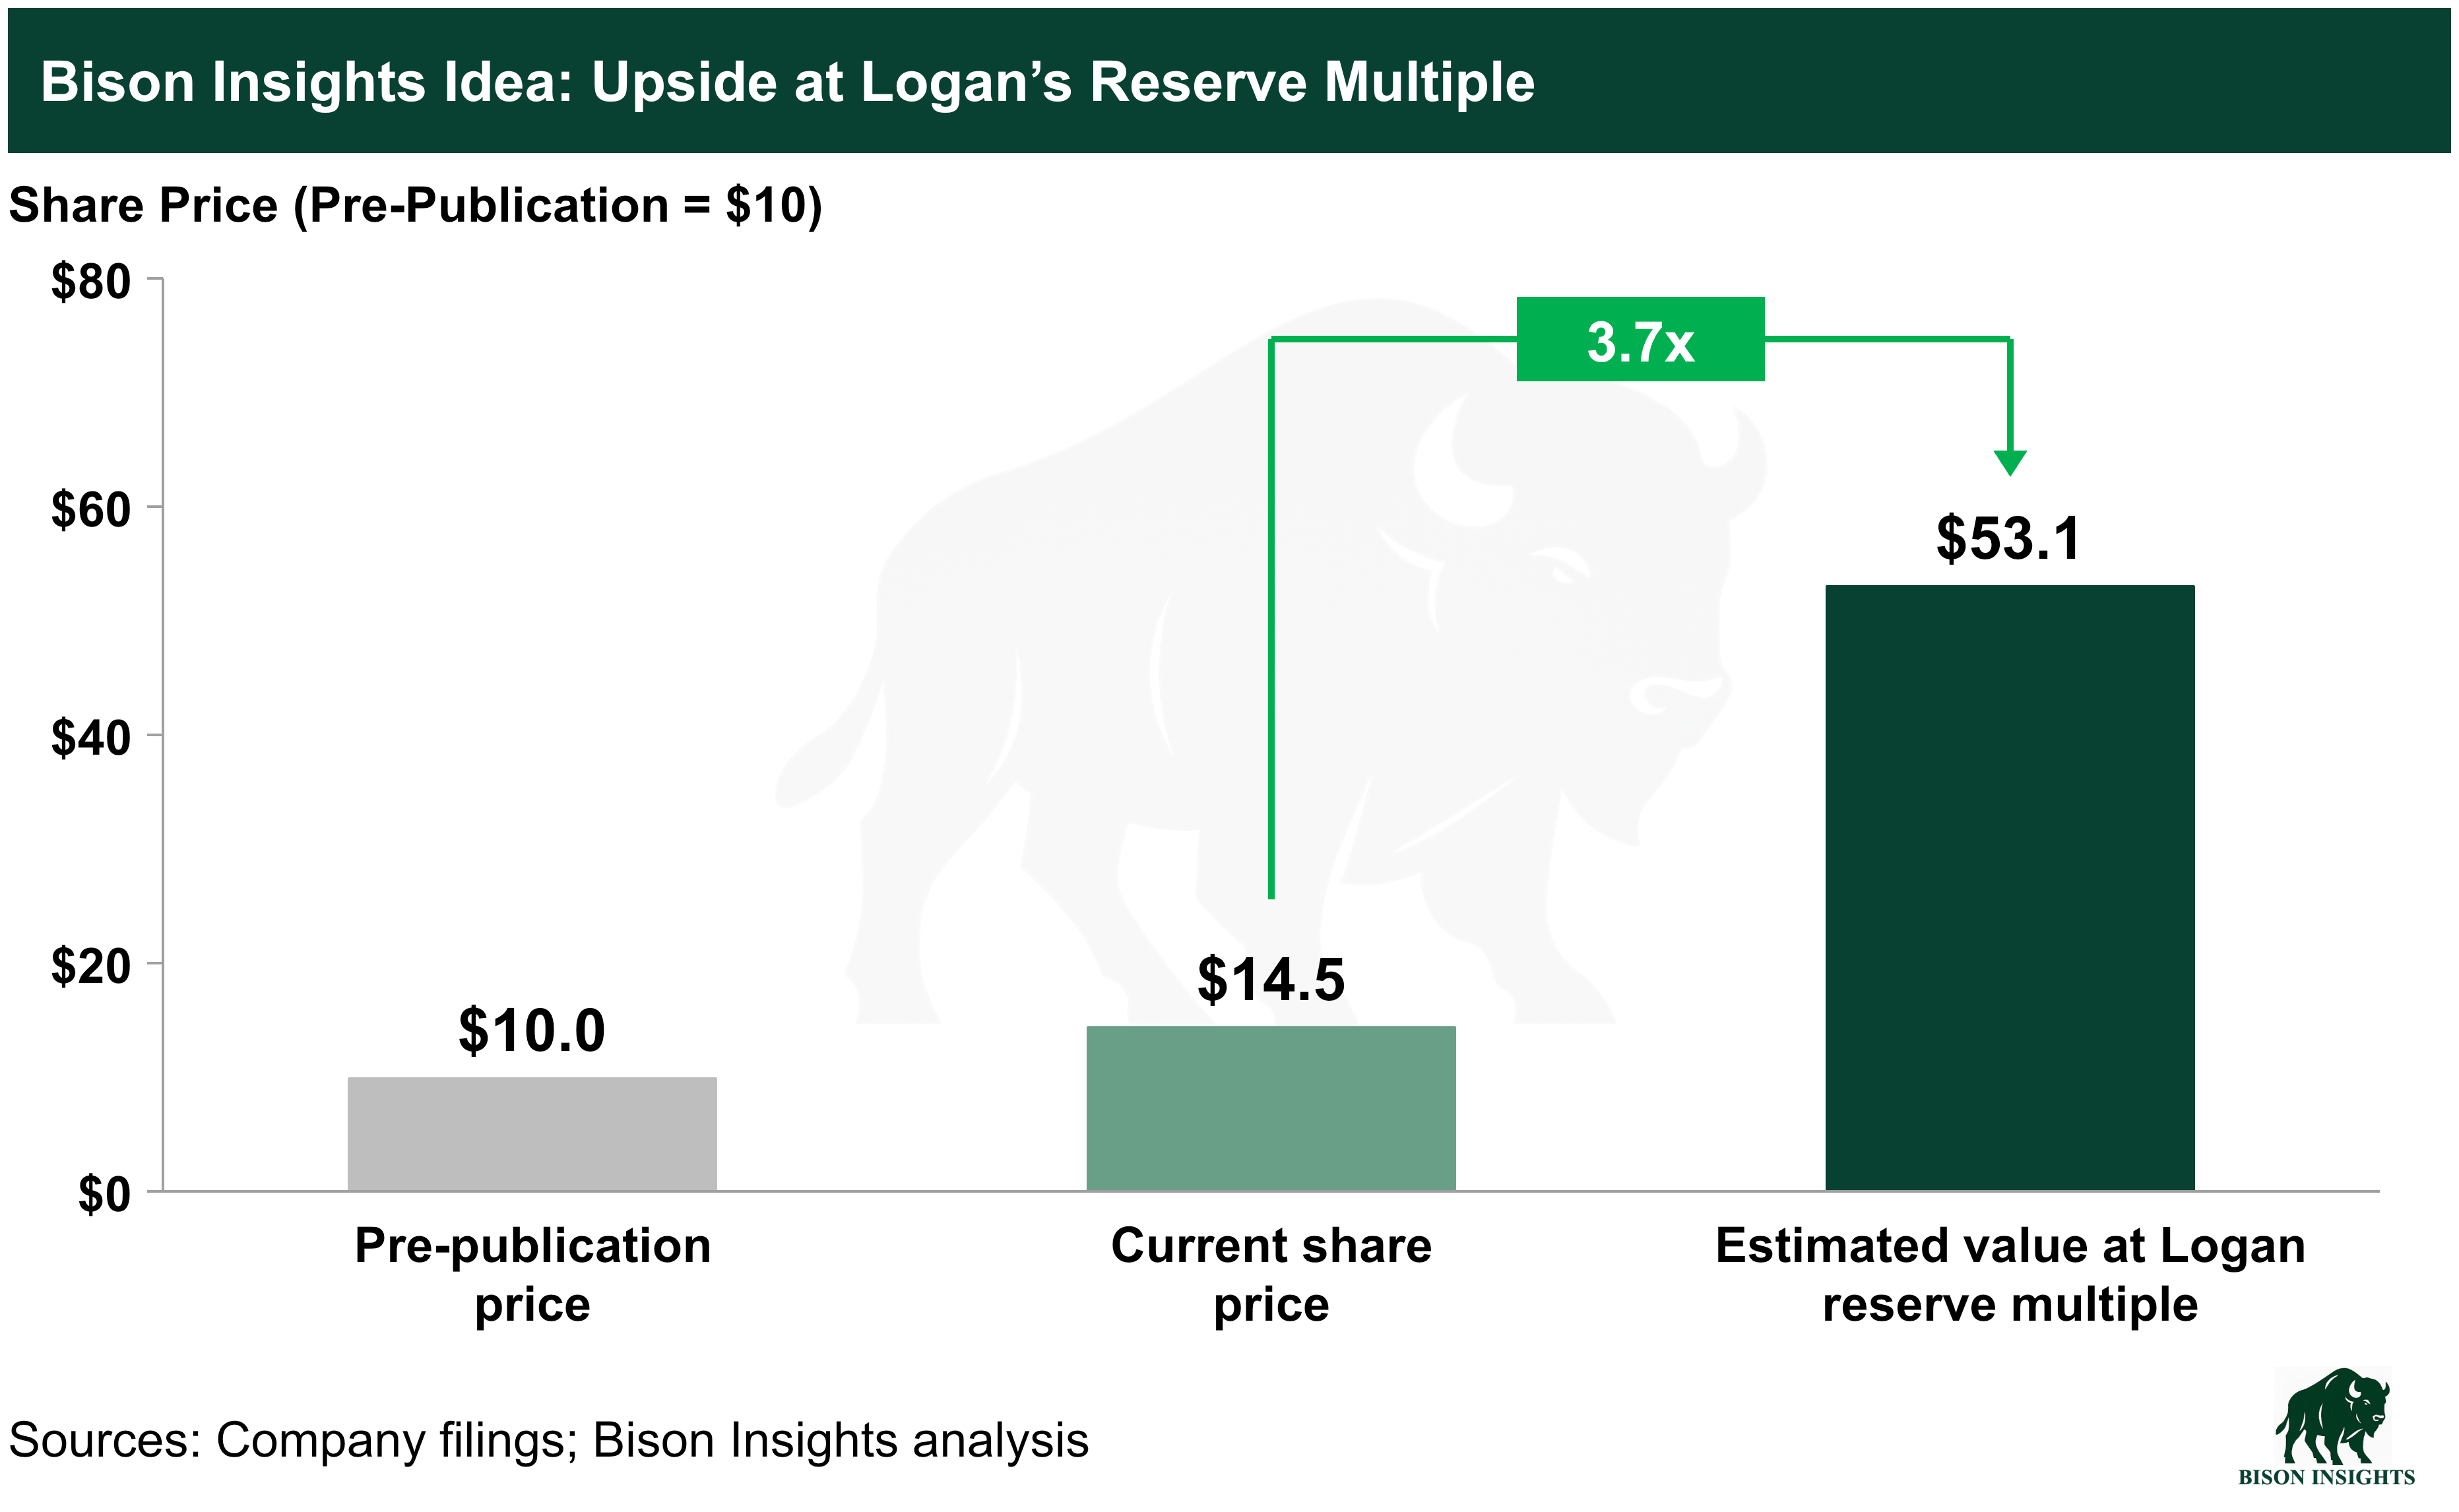
Ovintiv’s C$1.26 billion purchase of Logan Energy at roughly 2x proved reserve value points to further consolidation among Canadian oil…
Axon cut full-year guidance after delayed federal Dedrone contracts slowed 3Q revenue growth to 28%, while software and services grew 43%.

Axon’s 3Q26 revenue growth fell to 28% after delayed federal Dedrone contracts, while software grew 43% and its $1.2 billion Skydio…

Datadog beat Q3 revenue guidance by $52 million, but guided Q4 revenue flat as its largest AI-native customer reduced usage after renewing.
Moderna reported $1.313bn in Q3 revenue, up 29%, and $130m in operating income versus a $260m loss, while operating cash flow was negative…
Vicor earns a Strong Buy after record Q3 results and AI gains, while QXO falls to Hold over capital structure and execution risk.
 The Undercovered Dozen 1 click
Cloudflare’s Q3 revenue rose 39% to $782.5 million, its fastest growth in nearly four years, while a $67.9 million GAAP operating loss and…
Airbnb’s 3Q’26 revenue grew 16% ex-FX as bookings accelerated, but consumer travel agents remain a long-term competitive threat.
 HKTGF · long
Hikari Tsushin compounded shareholder equity at 17% annually over 15 years while its shares declined modestly in the past year.
FTAI’s Aerospace Products margin rebounded to 31% as CFM56 module output rose, while Power deposits and contracted deliveries fund its 2027…
SoFi raised its 2026 guidance after a blowout Q3 and issued a strong 2027 outlook, with revenue projected to reach $5 billion by Q4 2030.
 Riyado Sofian
Chevron’s Q3 revenue rose 35% to $65.2 billion and EBITDA 75% to $20.2 billion, while production trailed guidance and refining margins…
Sanofi raised FY26 guidance after Q3 sales grew 14.3% at constant currency, led by 34.8% Dupixent growth; vaccines declined 6.6%.
Bloom may have reopened imports of scandium-containing components from China to the United States, according to new trade data.

Markel spent $315 million repurchasing shares in Q3 as Thrive agreed to buy ADT for $7.6 billion and Hasbro cited rising adult toy demand.
Verisk Analytics’ 40 petabytes of proprietary insurance data and regulatory infrastructure shield its underwriting business from generative…
Applied Materials posted 51% growth while trading near 23 times forward earnings; memory spending and fab construction support orders, but…
 Capital Minded 1 click
Marvell’s reported Lumentum bid would combine DSPs, lasers and optical modules, but $4 billion of cash and $5 billion of debt point to a…
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Cypriot Invests
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.