AppLovin 3Q26 Business Update: No Notes
AppLovin’s Q3 revenue rose 55% year over year as AXON model gains expanded margins, while ad take-rate compression remains the key competitive risk.
AppLovin’s Q3 revenue rose 55% year over year as AXON model gains expanded margins, while ad take-rate compression remains the key competitive risk.
@_Housing_Guy_ Structural deficit in houses will need to balance eventually. Cycle will cycle eventually (rates, inflation economy ect). Company won’t go bankrupt and will chug along until then. Transition to capital light $NVR model not fully priced in.
@SW_Resurgo I dunno, I see lots of very real cases of people doing shit like this. Remember the guy who went all in on $PDD and then had a royal crash out?
$CXW got a new President/CEO today. https://t.co/7WpulDuHkg
@srg444 Me looking at $MGM trading at $32 when Osaka asset is worth 💰 https://t.co/jvVZZ37LP0
@WaterworldCapi1 $fds decent short, very big and liquid, not showing deterioration yet, still an opportunity to short into earnings revisions (if they happen)
MercadoLibre’s logistics expansion cut margins by 60 basis points, while Mercado Pago grew credit 62% with 7% NPLs.
 Luca Socci 4 clicks
Intel's Q3 2026 results were hit by memory costs and an Israel shutdown, but enterprise AI inference could lift CPU demand as server…
Twist Bioscience’s $200 rebound followed an Anthropic-linked short squeeze, yet its DNA and protein services face broad competition while…

Vishay reported record Q3 revenue of $979 million, up 24%, and guided Q4 to about $990 million as rising backlog and margins contrast with…
AutoNation, Lear, NexPoint, AudioCodes and Xponential Fitness lead a 52-situation screen spanning buybacks, insider purchases, M&A and…
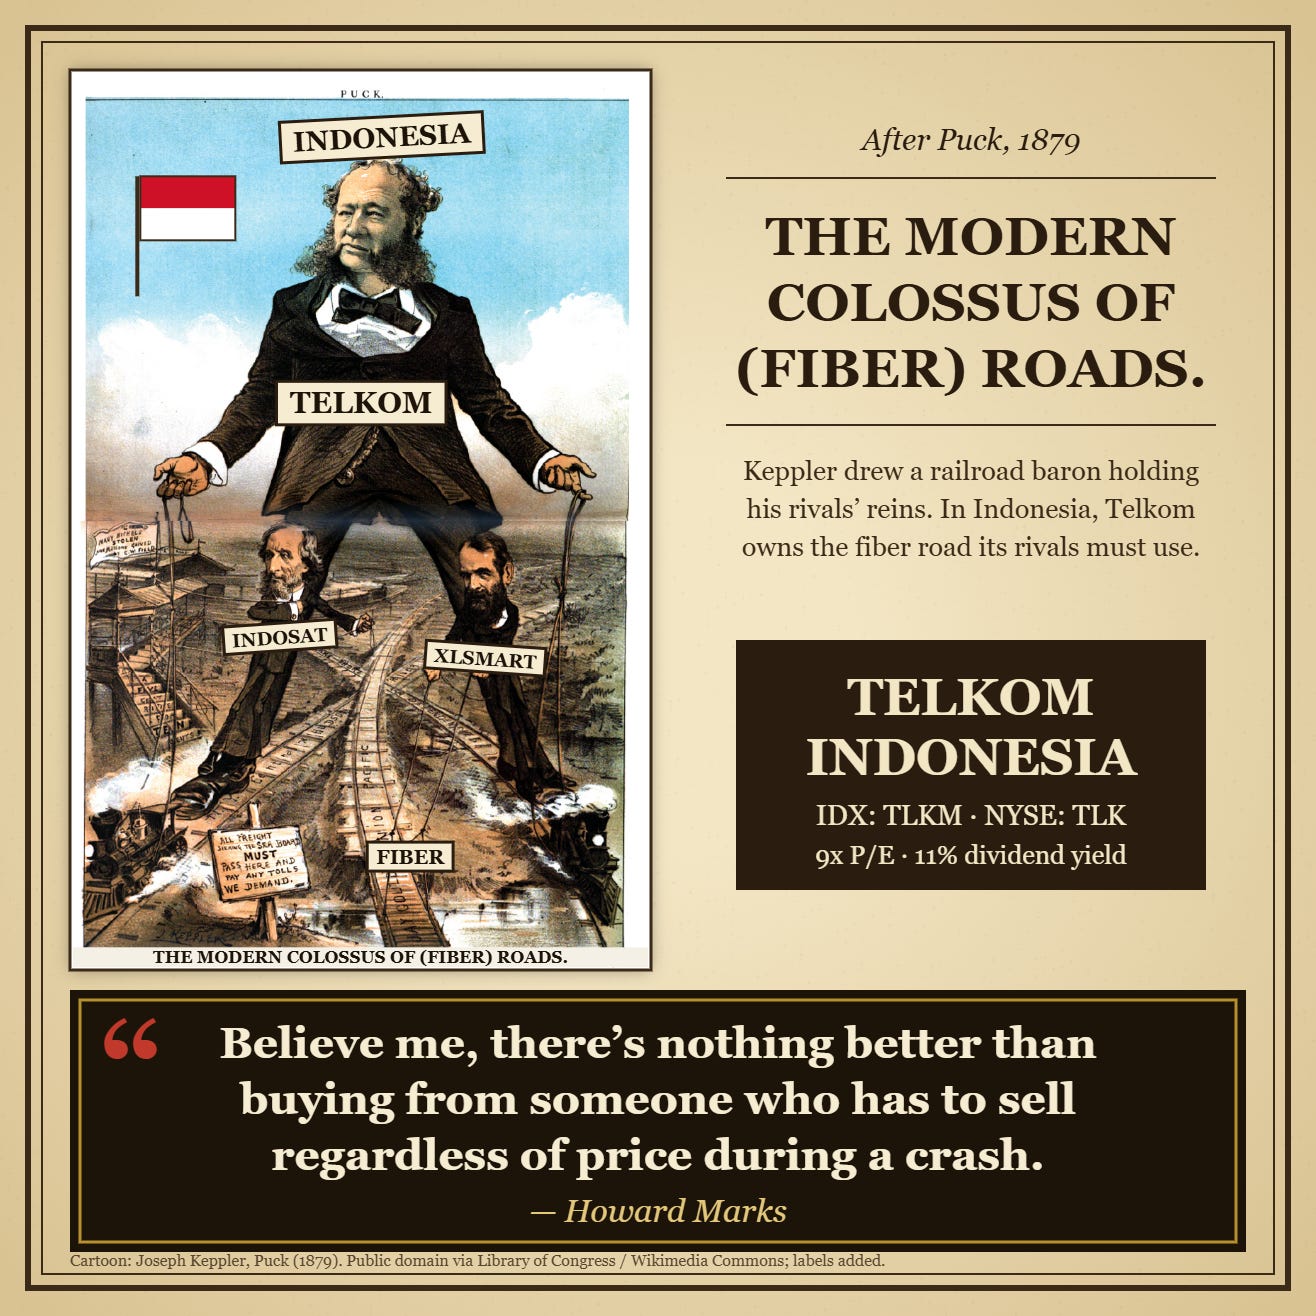
Telkom Indonesia trades at 9x earnings and an 11% yield as MSCI-driven selling obscures telecom consolidation, price increases and…
Florida marinas are 92% full as boat counts rise and permits constrain new supply, creating pricing power for existing operators such as…
Delta Air Lines' premium, loyalty and ancillary businesses generate 61% of revenue as cash flow supports debt reduction despite fuel and…
 Motti Sapir
Warrior Met Coal’s Blue Creek mine cut costs to about $93 a ton, offsetting a wider discount for High Vol A coking coal as US supply…
 CHWY · long
Chewy (CHWY) is presented as a long opportunity after a prior 2022 short thesis played out.
 Motti Sapir 2 clicks
GPC’s NAPA commercial sales grew 4% in Q3, trailing AutoZone and O’Reilly as freight, fuel and rent cut North American Automotive margins…
AMSC and Datadog will be fine, while SiTime is worth a closer look.
Intuit CEO Sasan Goodarzi discusses using AI to turn accountants from customer-acquisition partners into customers, alongside QuickBooks,…

DigitalOcean reported Q3 revenue up 40% to $321 million and lifted Q4 guidance above consensus, while GPU and data-center expansion cut…
Aurelion Research increased healthcare exposure and sees opportunities in banking and defense, alongside research on Alcoa, Nike, ONON and…
L3Harris booked $19.3 billion of Q3 orders, lifting backlog to $53.2 billion, raised FY26 guidance and cut its 2028 free-cash-flow target…
Oracle’s CDS spreads exceed 320 basis points as debt approaches $135 billion and fiscal 2027 capex targets $95 billion, amid heavy reliance…
 David Desjardins 1 click
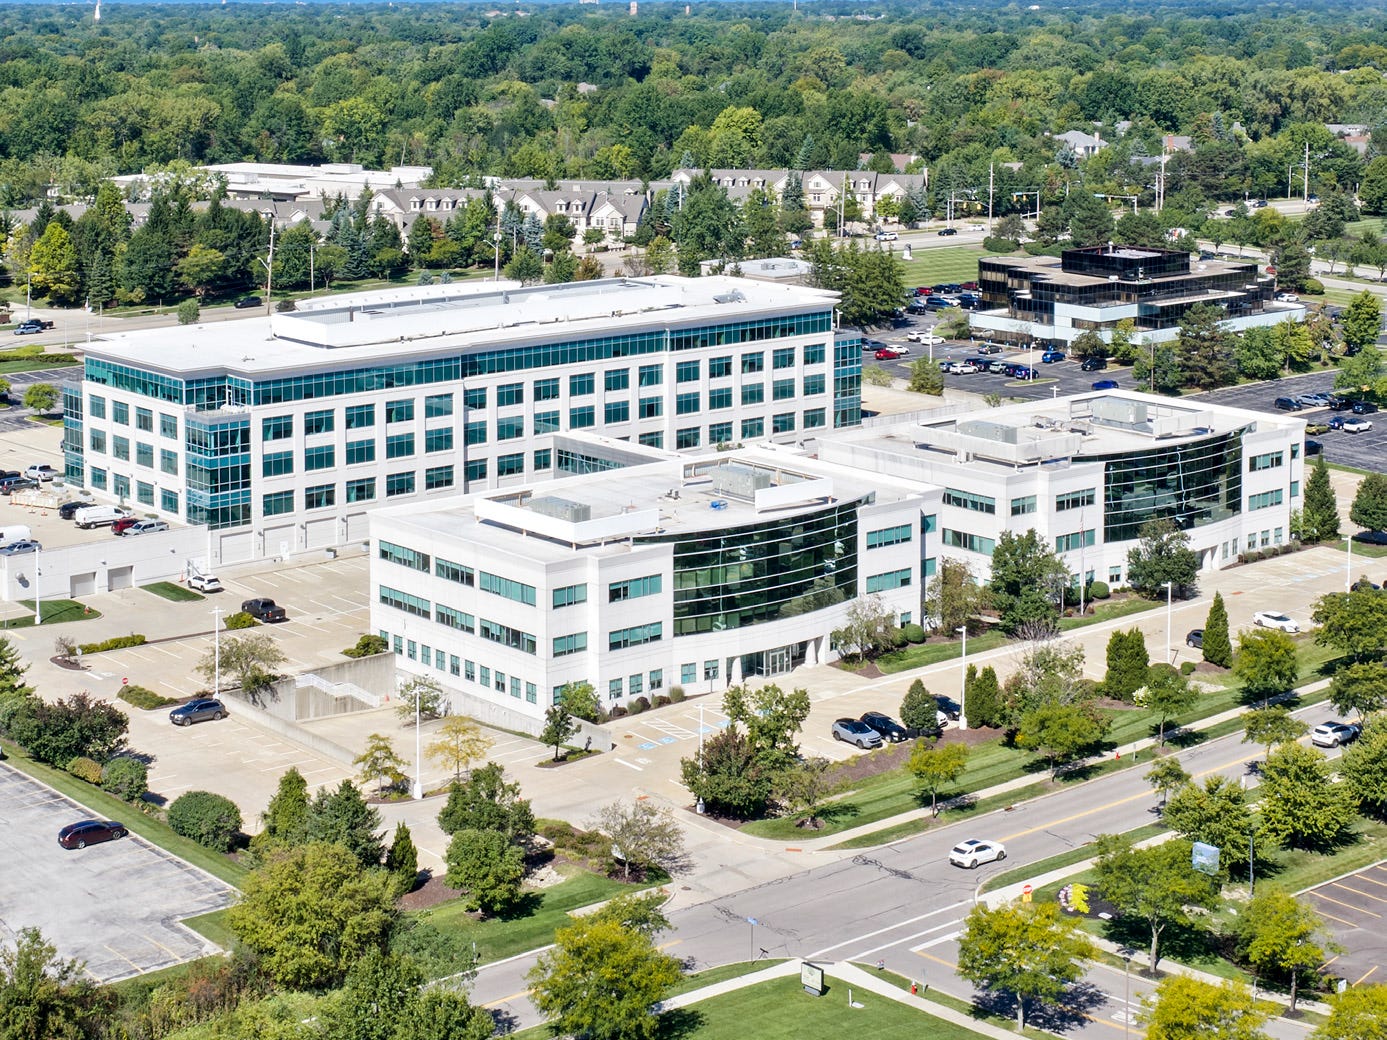
Site Centers' $3 per-share return-of-capital distribution and December delisting leave a discounted liquidation stub, with two properties…
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Cypriot Invests
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.