TWLO Q3 FY12/26 Earnings Review
Twilio's Q3 revenue rose 20% to $1.56 billion, but Q4 organic growth guidance fell to 11% to 12% and RPO declined 28%.
Twilio's Q3 revenue rose 20% to $1.56 billion, but Q4 organic growth guidance fell to 11% to 12% and RPO declined 28%.
D.A. Davidson analyst Gil Luria (has a $100 price target and a neutral rating on $CRWV ) says “the equity value is going to be zero” on a podcast released today A bit conflicting there Gil https://t.co/aKJmqVZlZ5
D.A. Davidson analyst Gil Luria (has a $100 price target and a neutral rating on $CRWV ) says “the equity value is going to be zero” on a podcast released today A bit conflicting there Gil https://t.co/ZLEqfmpE8i
$CRDO Interesting. Credo might help with memory shortage. https://t.co/ZIzLU7aPKO
@valuemaverick1 I have no view whether $33 is a good price for $BSP, but I'm comfortable selling calls in the 70s.
@Musecases I took the "L" at the open on $BSP. It was small so lost ~50 bps. No borrow at IBKR, could continue to squeeze until the lock up in late Dec. Can't believe Berkshire owns this POS. Makes me question Greg.
Berkshire or no Berkshire, $BSP is awfully rich here. I'm a seller of far dated otm calls. https://t.co/JkugYB6LOg
*BERKSHIRE HATHAWAY INVESTS ADDITIONAL $330M IN BENDING SPOONS Today I learned $BRK.B had a stake in $BSP (now 4%) https://t.co/OK86G4kZCP
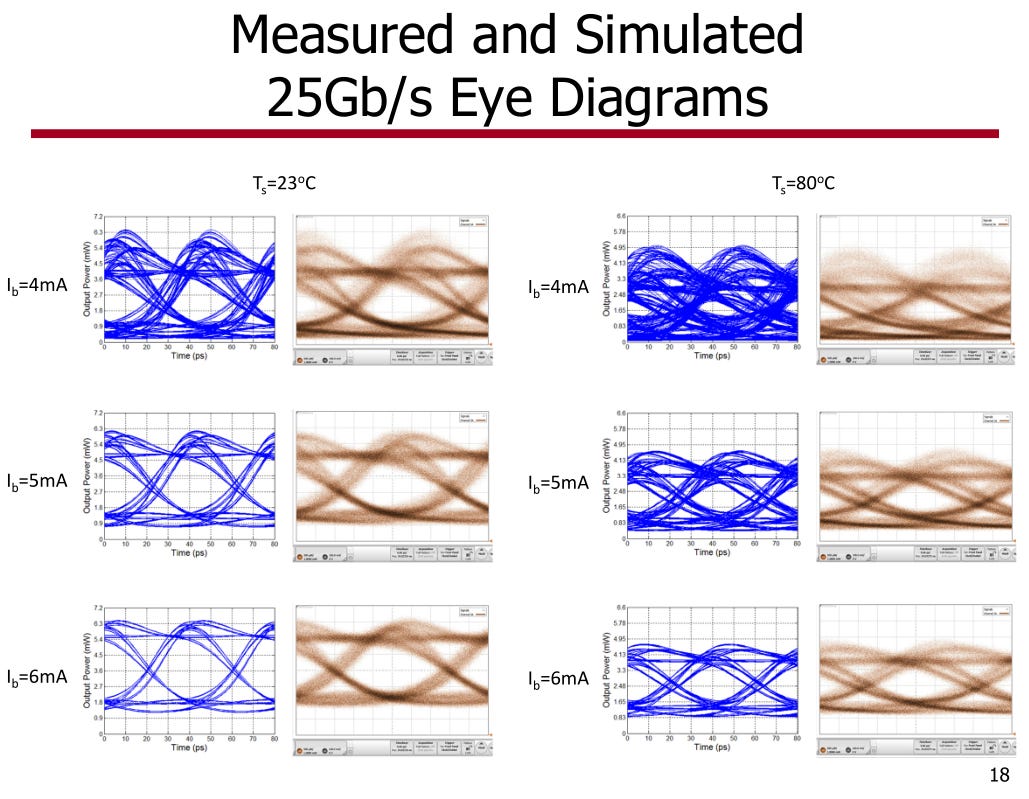
Marvell and Lumentum’s merger targets uVCSEL scale-in optics, combining Marvell’s DSP and analog IP with Lumentum’s laser manufacturing for…
Marvell’s all-stock Lumentum deal exposes LITE holders to MRVL volatility while paying peak-cycle AI multiples, with US and China antitrust…
 Dustin Quasney 2 clicks
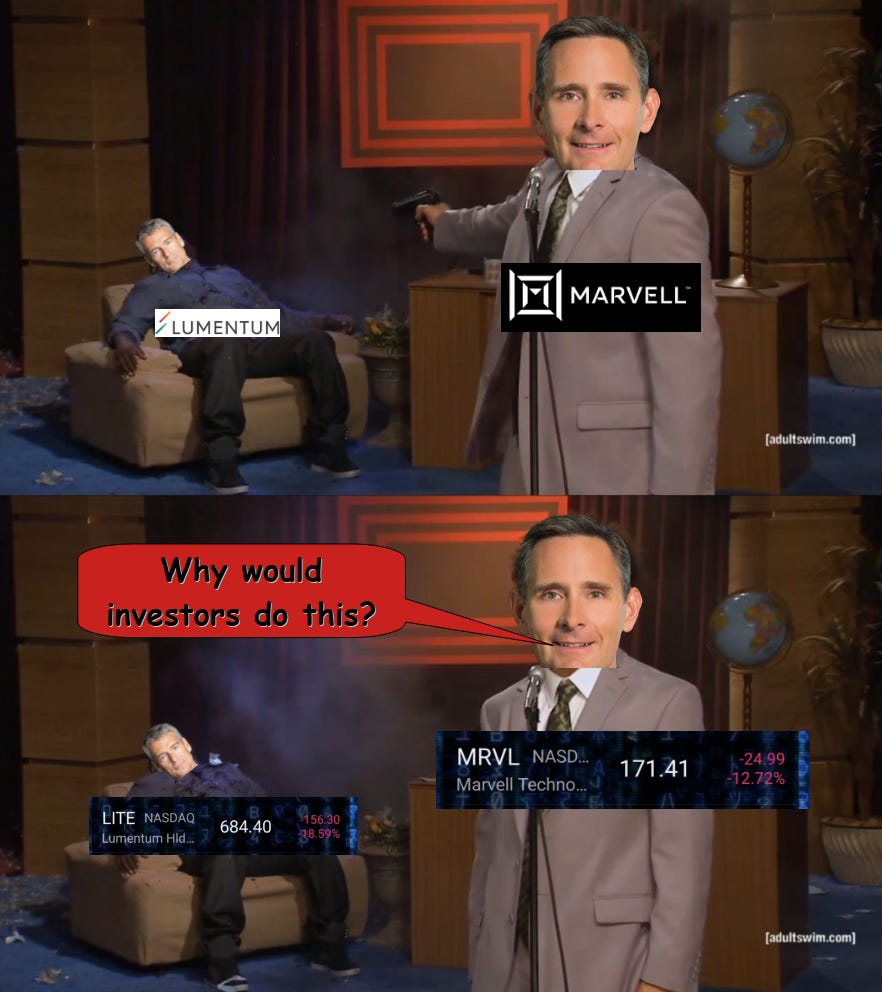
Marvell’s proposed Lumentum deal risks alienating Cloudlight customers and losing engineering talent, despite limited optical integration…
Nebius faces refinancing and dilution risks from short-term borrowing and heavy GPU infrastructure spending despite higher rental prices…
 Hunting Alphas 2 clicks
Marvell Technology and Lumentum fell sharply after announcing a historic merger, reviving comparisons with JDS-Uniphase.
FTAI Aviation’s $234 million Jereh JV deposit funds Power inventory, while customer concentration, lower cash guidance and pending U.S.
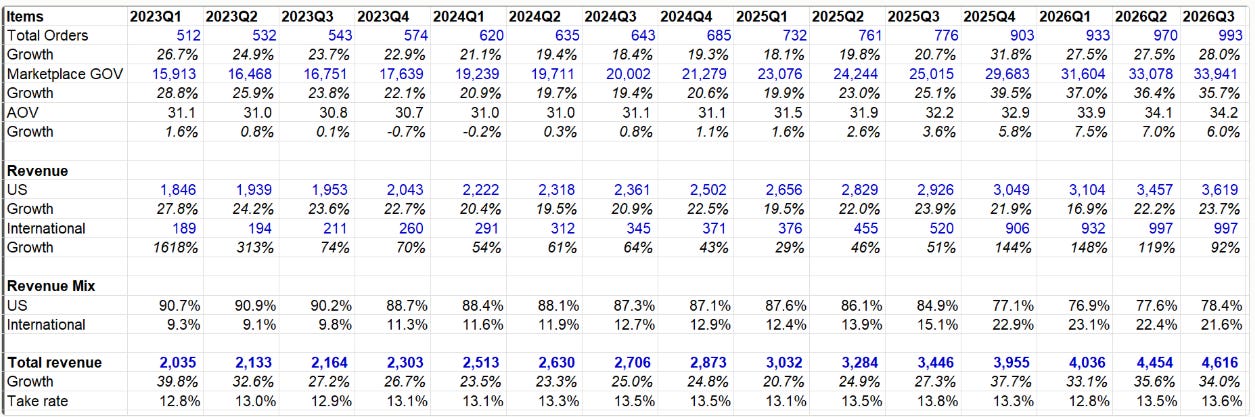
DoorDash’s 3Q orders rose 28% as it announced a $17 billion Instacart acquisition, expanding its grocery basket strategy after buying…
Kinross faces a roughly 6% 2026 guidance miss after lower Round Mountain and La Coipa output, while costs rose 20% year over year.
 Taylor Dart 1 click
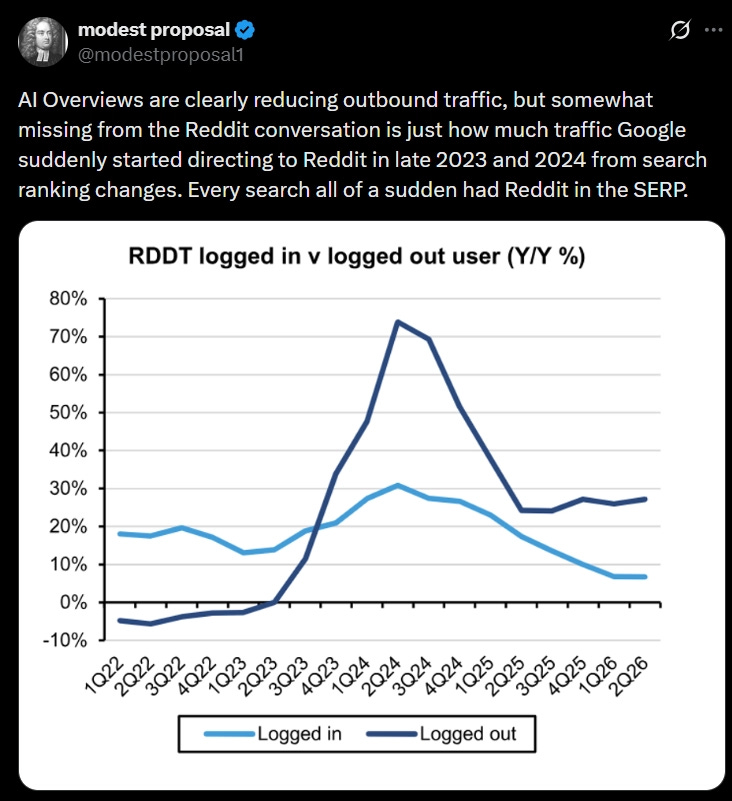
Reddit’s Google referrals fell by more than 1 million a week as AI search expands, prompting a logged-in-user push to protect ad yield and…
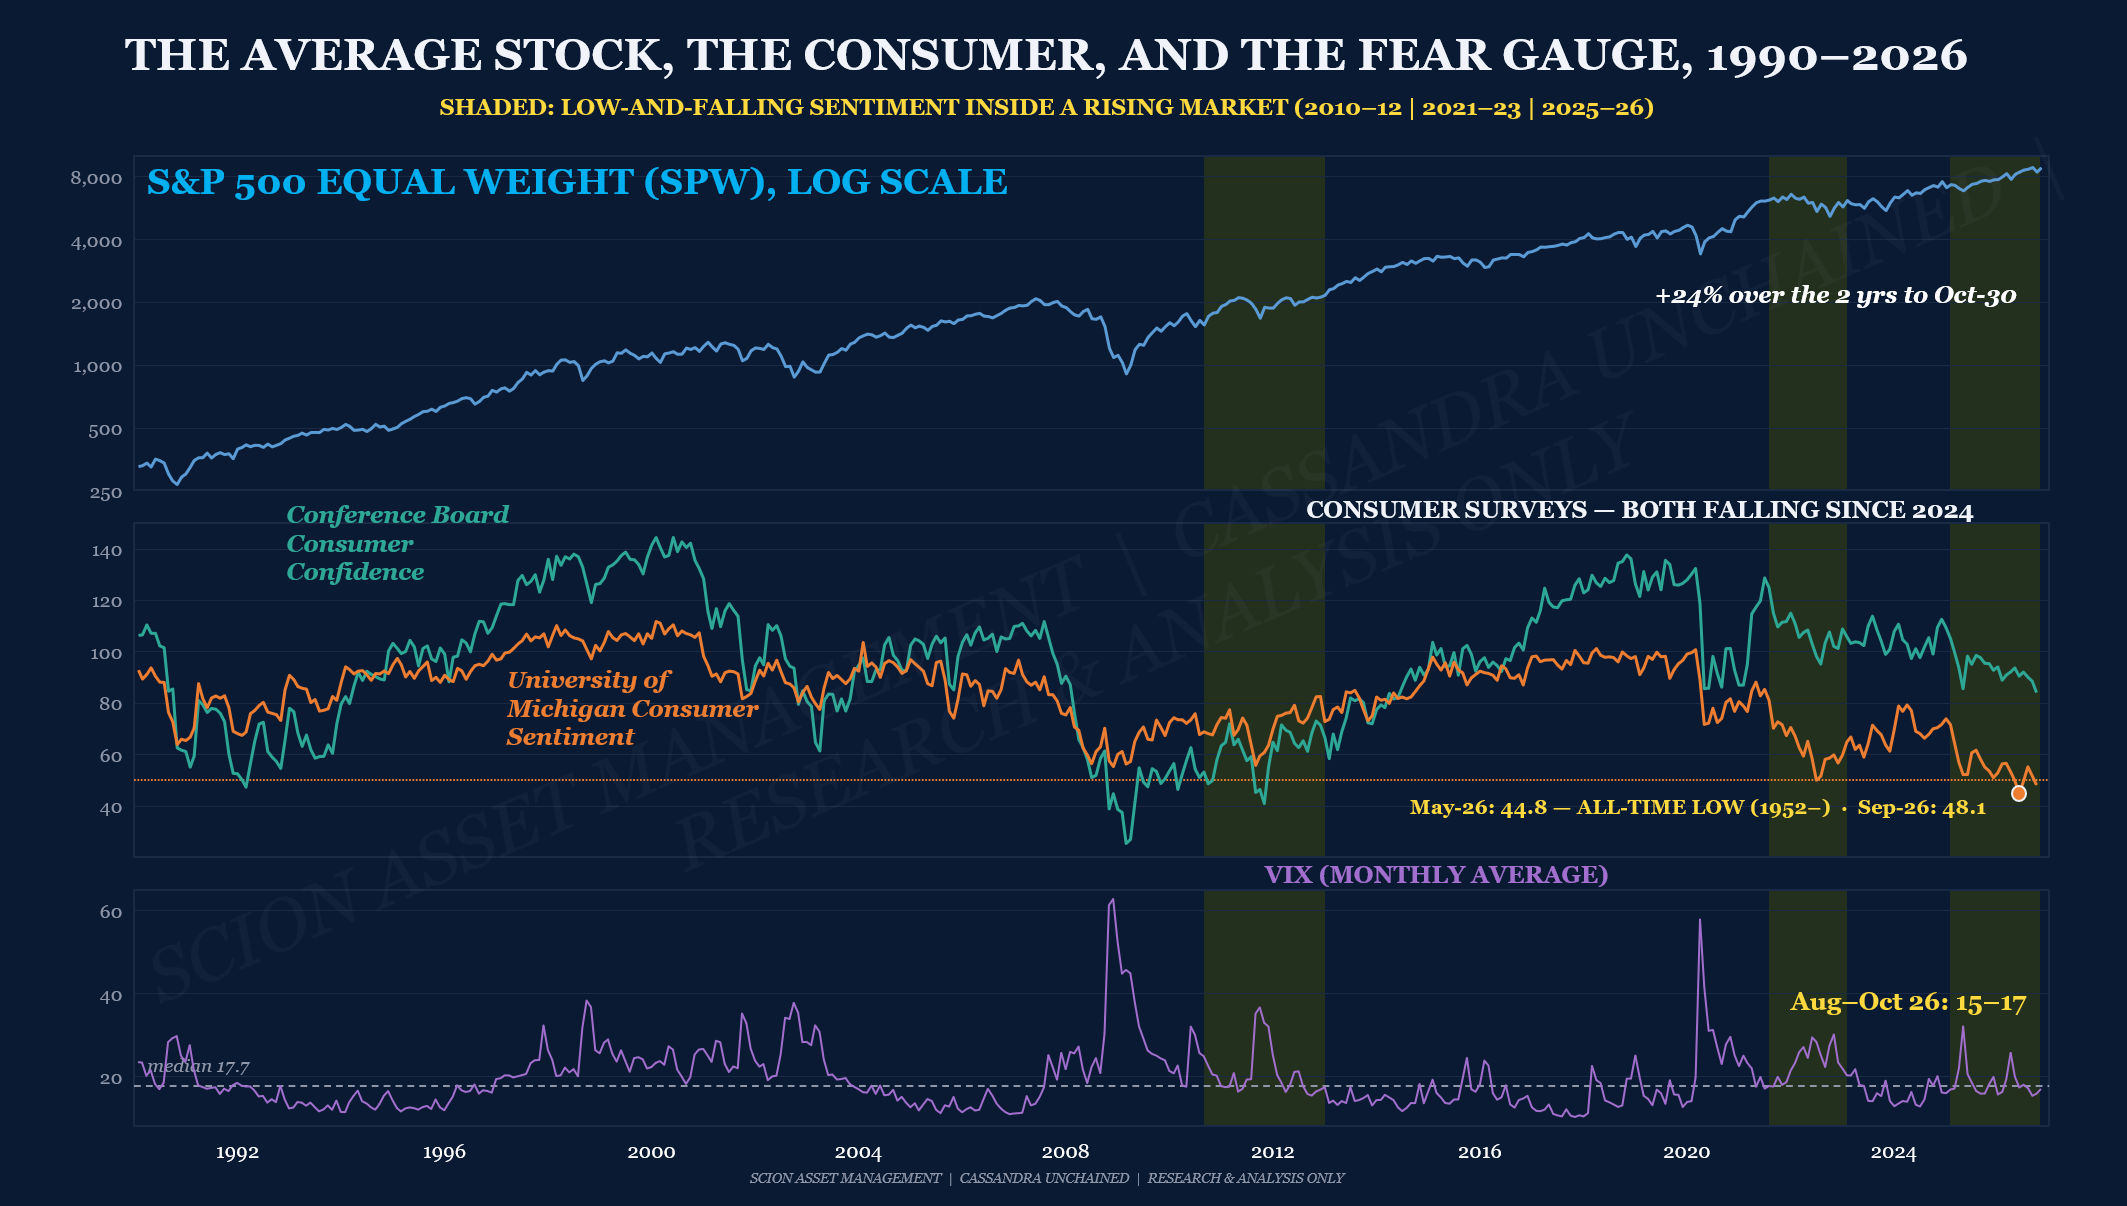
Global Payments rose 18% on a reported CD&R and GTCR take-private bid, while estimated control value is $45-$60 versus a $96.84 share price.
BioNTech's Q3 revenue beat consensus on €613 million of BMS partnership revenue, while COVID vaccine sales fell 35% and net cash totaled…
Onsemi's Q3 revenue rose 11% to $1.72 billion, driven by 175% AI data-center growth, while automotive revenue fell 1% and net debt dropped…
Enterprise Products Partners has pulled growth spending into 2026, while Energy Transfer’s contracted projects offer clearer EBITDA growth…
 BSP · short
Bending Spoons is a software and digital-assets holding company that has completed more than 50 acquisitions since 2013.
BioMarin’s Q3 revenue rose 32% to $1.02 billion after the Amicus acquisition, while lower 2026 guidance and $2.8 billion of net debt…
Grab’s Southeast Asian delivery business nears a profitability inflection point, while consolidation and a potential GoTo deal challenge…
 Wavelength Research 2 clicks
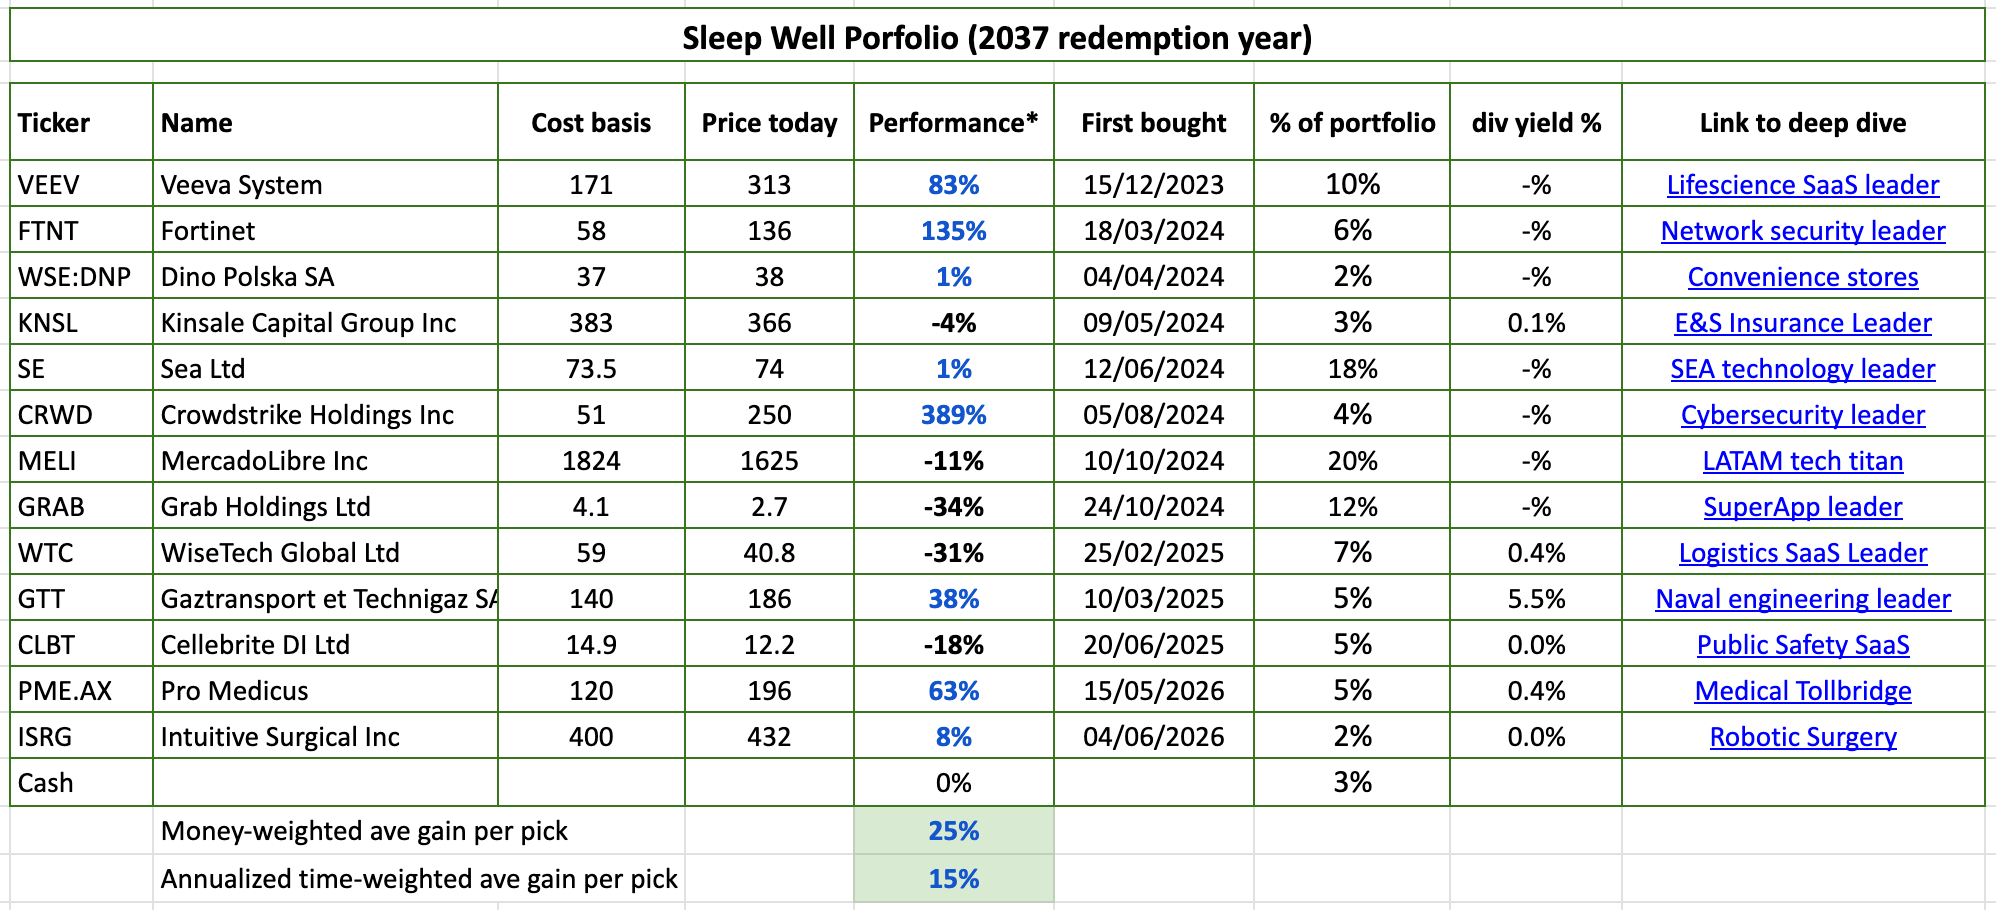
Sleep Well Portfolio adds two AI infrastructure suppliers and trims CrowdStrike at a 140x free-cash-flow valuation and $270 billion market…
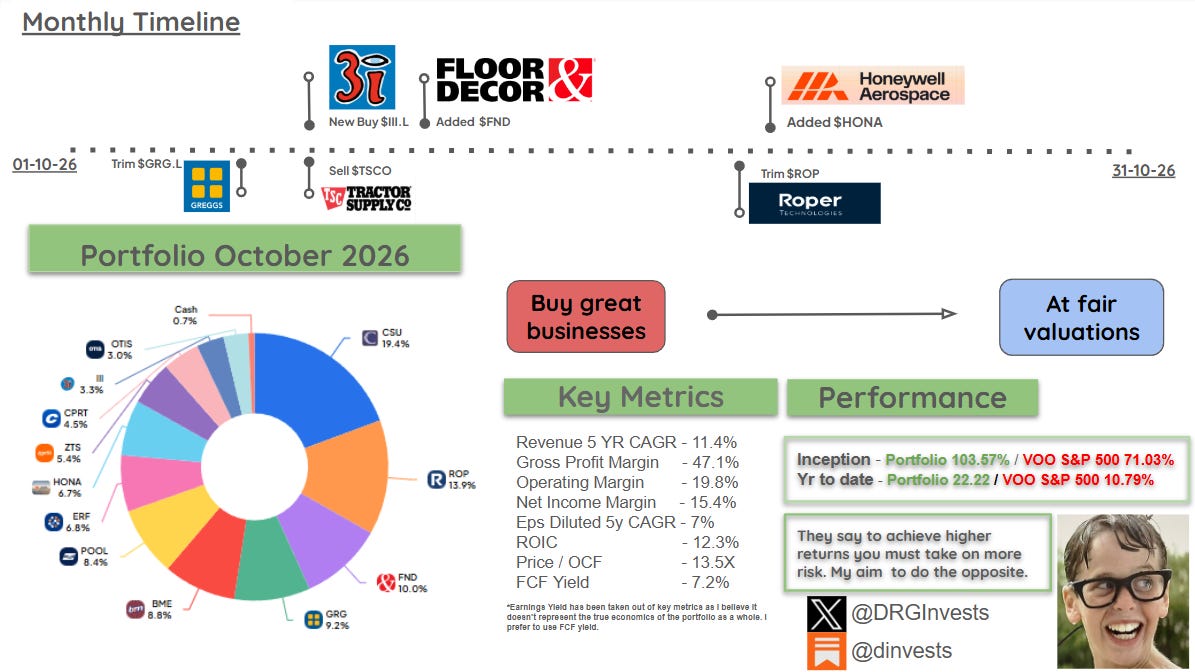
Portfolio returned over 15% in October, lifting cumulative gains to 103.5%, while adding 3i Group and increasing Floor & Decor and…
Agnico Eagle expects low-end 2026 guidance despite Barnat setbacks, while Hope Bay, Upper Beaver and Odyssey support production above 4…
Taylor Dart 3 clicks
AAOI, Lumentum and Coherent 800G ramps, NVIDIA Rubin timing, and AMD, Intel and Arm server CPU demand frame an expert call on AI…
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Cypriot Invests
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.