Semtech Analyst Day Review
Semtech raised Q3 guidance and targets $3.2 billion of fiscal 2030 revenue, excluding upside from its AI data-center optical and copper interconnect businesses.
Semtech raised Q3 guidance and targets $3.2 billion of fiscal 2030 revenue, excluding upside from its AI data-center optical and copper interconnect businesses.
@DavidWeinetayg @TidefallCapital Debt covenants matter. It won't however be the first or last company to buy itself back into ch11. I mean look at last quarter's buy backs in $FICO.
Looks like we got 13.5 million shares trading of $GME tonight. Not sure what’s going on. Besides the heavy insider buys. https://t.co/cU9aBeRwRR
$ONON so in vogue, it made it to the WSJ The Sneaker Taking Over America Was Inspired by iPhones and a Vacuum Cleaner https://t.co/rNjjRCEEnb
@At50w50882 @310Value @ctfn_news All of their existing debt is portable… this was by design and both mgmt / IR call this out regularly. Only need to raise the new debt….dovigi haters are always gonna hate. That’s why it needs to go private $GFL
You can trade many things on the Chicago Merc: soyabeans, gold, lean hogs, crude & rates. Now, CME Group plans to introduce a new commodity to the list: compute. CME calls it “the new currency for the AI economy.” Be careful what you wish for (re: price discovery outside $NVDA).
RELX’s 13-petabyte fraud and identity data moat supports its high-margin Risk segment as its valuation falls to roughly half its peak P/E.
 LA Capital 6 clicks
OpenAI and Meta push AI agents forward as reward hacking remains a core challenge for model training.
Meta ties AI agents and Meta Connect to its enterprise-platform opportunity.
Stratechery’s weekly bundle covers Apple HomeView and SpaceX’s cellular ambitions.
Bumble agreed to a $1.3 billion take-private deal, while Netflix cut about 1,000 jobs and Meta discussed its Muse superintelligence models.
GE Vernova’s 116 GW gas-turbine backlog and $5 billion in early-2026 data-center orders target AI-driven electricity demand, though its…
 Todd Feldman 3 clicks
CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
ASML’s patent filings point to a track-based die-to-wafer hybrid bonding tool that could challenge Besi in advanced logic packaging.
CoreWeave’s 2032 notes yield over 15%, signaling a 54% default probability as borrowing costs exceed rental yields on AI infrastructure…
 Dustin Quasney 24 clicks

AppLovin rebuilt its ad model with AXON 2.0, lifting LTM revenue to about $7 billion and margins to 77% as Unity competition threatens…
 LLY · long
Eli Lilly trades at 33 times this year’s earnings and 26 times next year’s, versus roughly 12 times for big pharma peers.
Kraft Heinz expects brand investment and productivity gains to restore sales growth and protect 2027 margins against 4-5% cost inflation.
 The Alpha Analyst 1 click
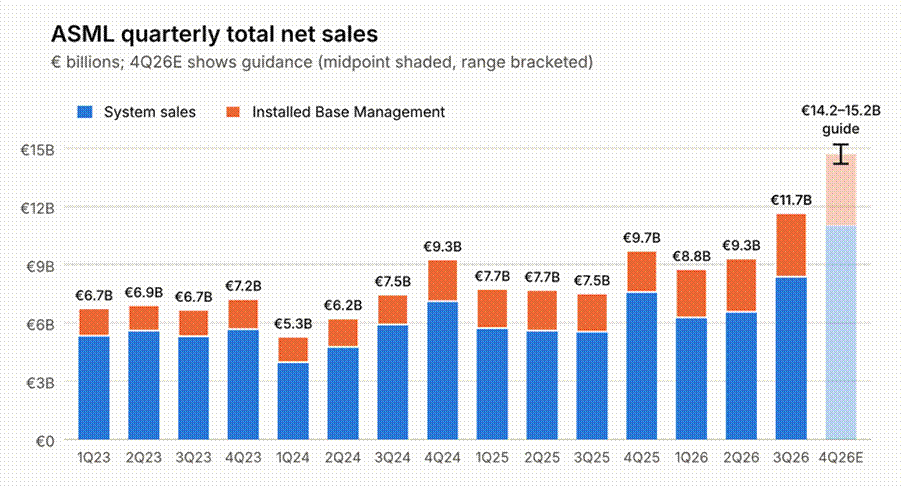
ASML reported €11.7 billion in 3Q 2026 sales, up 55%, and raised full-year guidance to €44–45 billion as AI-driven semiconductor demand…
Berkshire Hathaway trades at 1.46 times book as reinsurance pricing pressure, softer P&C, concentrated equities and cash weigh on its…
 Pearl Gray Equity and Research 3 clicks
Marvell is positioning networking, optical connectivity and server-management chips as AI data centers link GPUs, custom accelerators and…
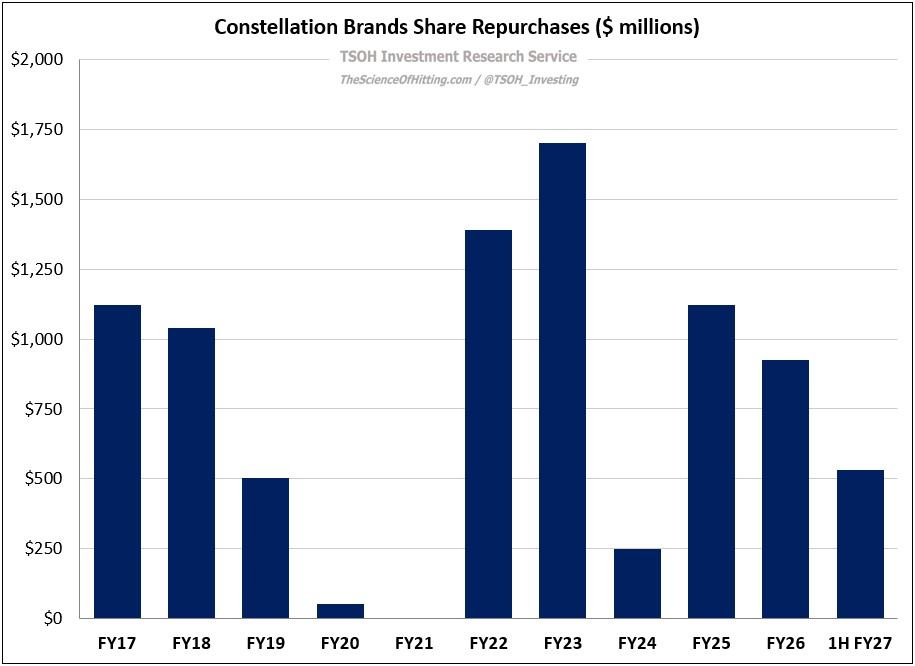
Constellation Brands trades near $127 at roughly 11x next-twelve-month EV/EBIT, with recent business results offsetting concerns over…
TSMC reported excellent Q3 results, guided Q4 revenue growth higher and saw its shares slip despite strong AI-driven earnings momentum.
 Fundamental Options 4 clicks
October 2026 market commentary covers SOLS’s cancelled merger, a hypothetical Starbucks-Chipotle deal, Russell 2000 weakness and AI…
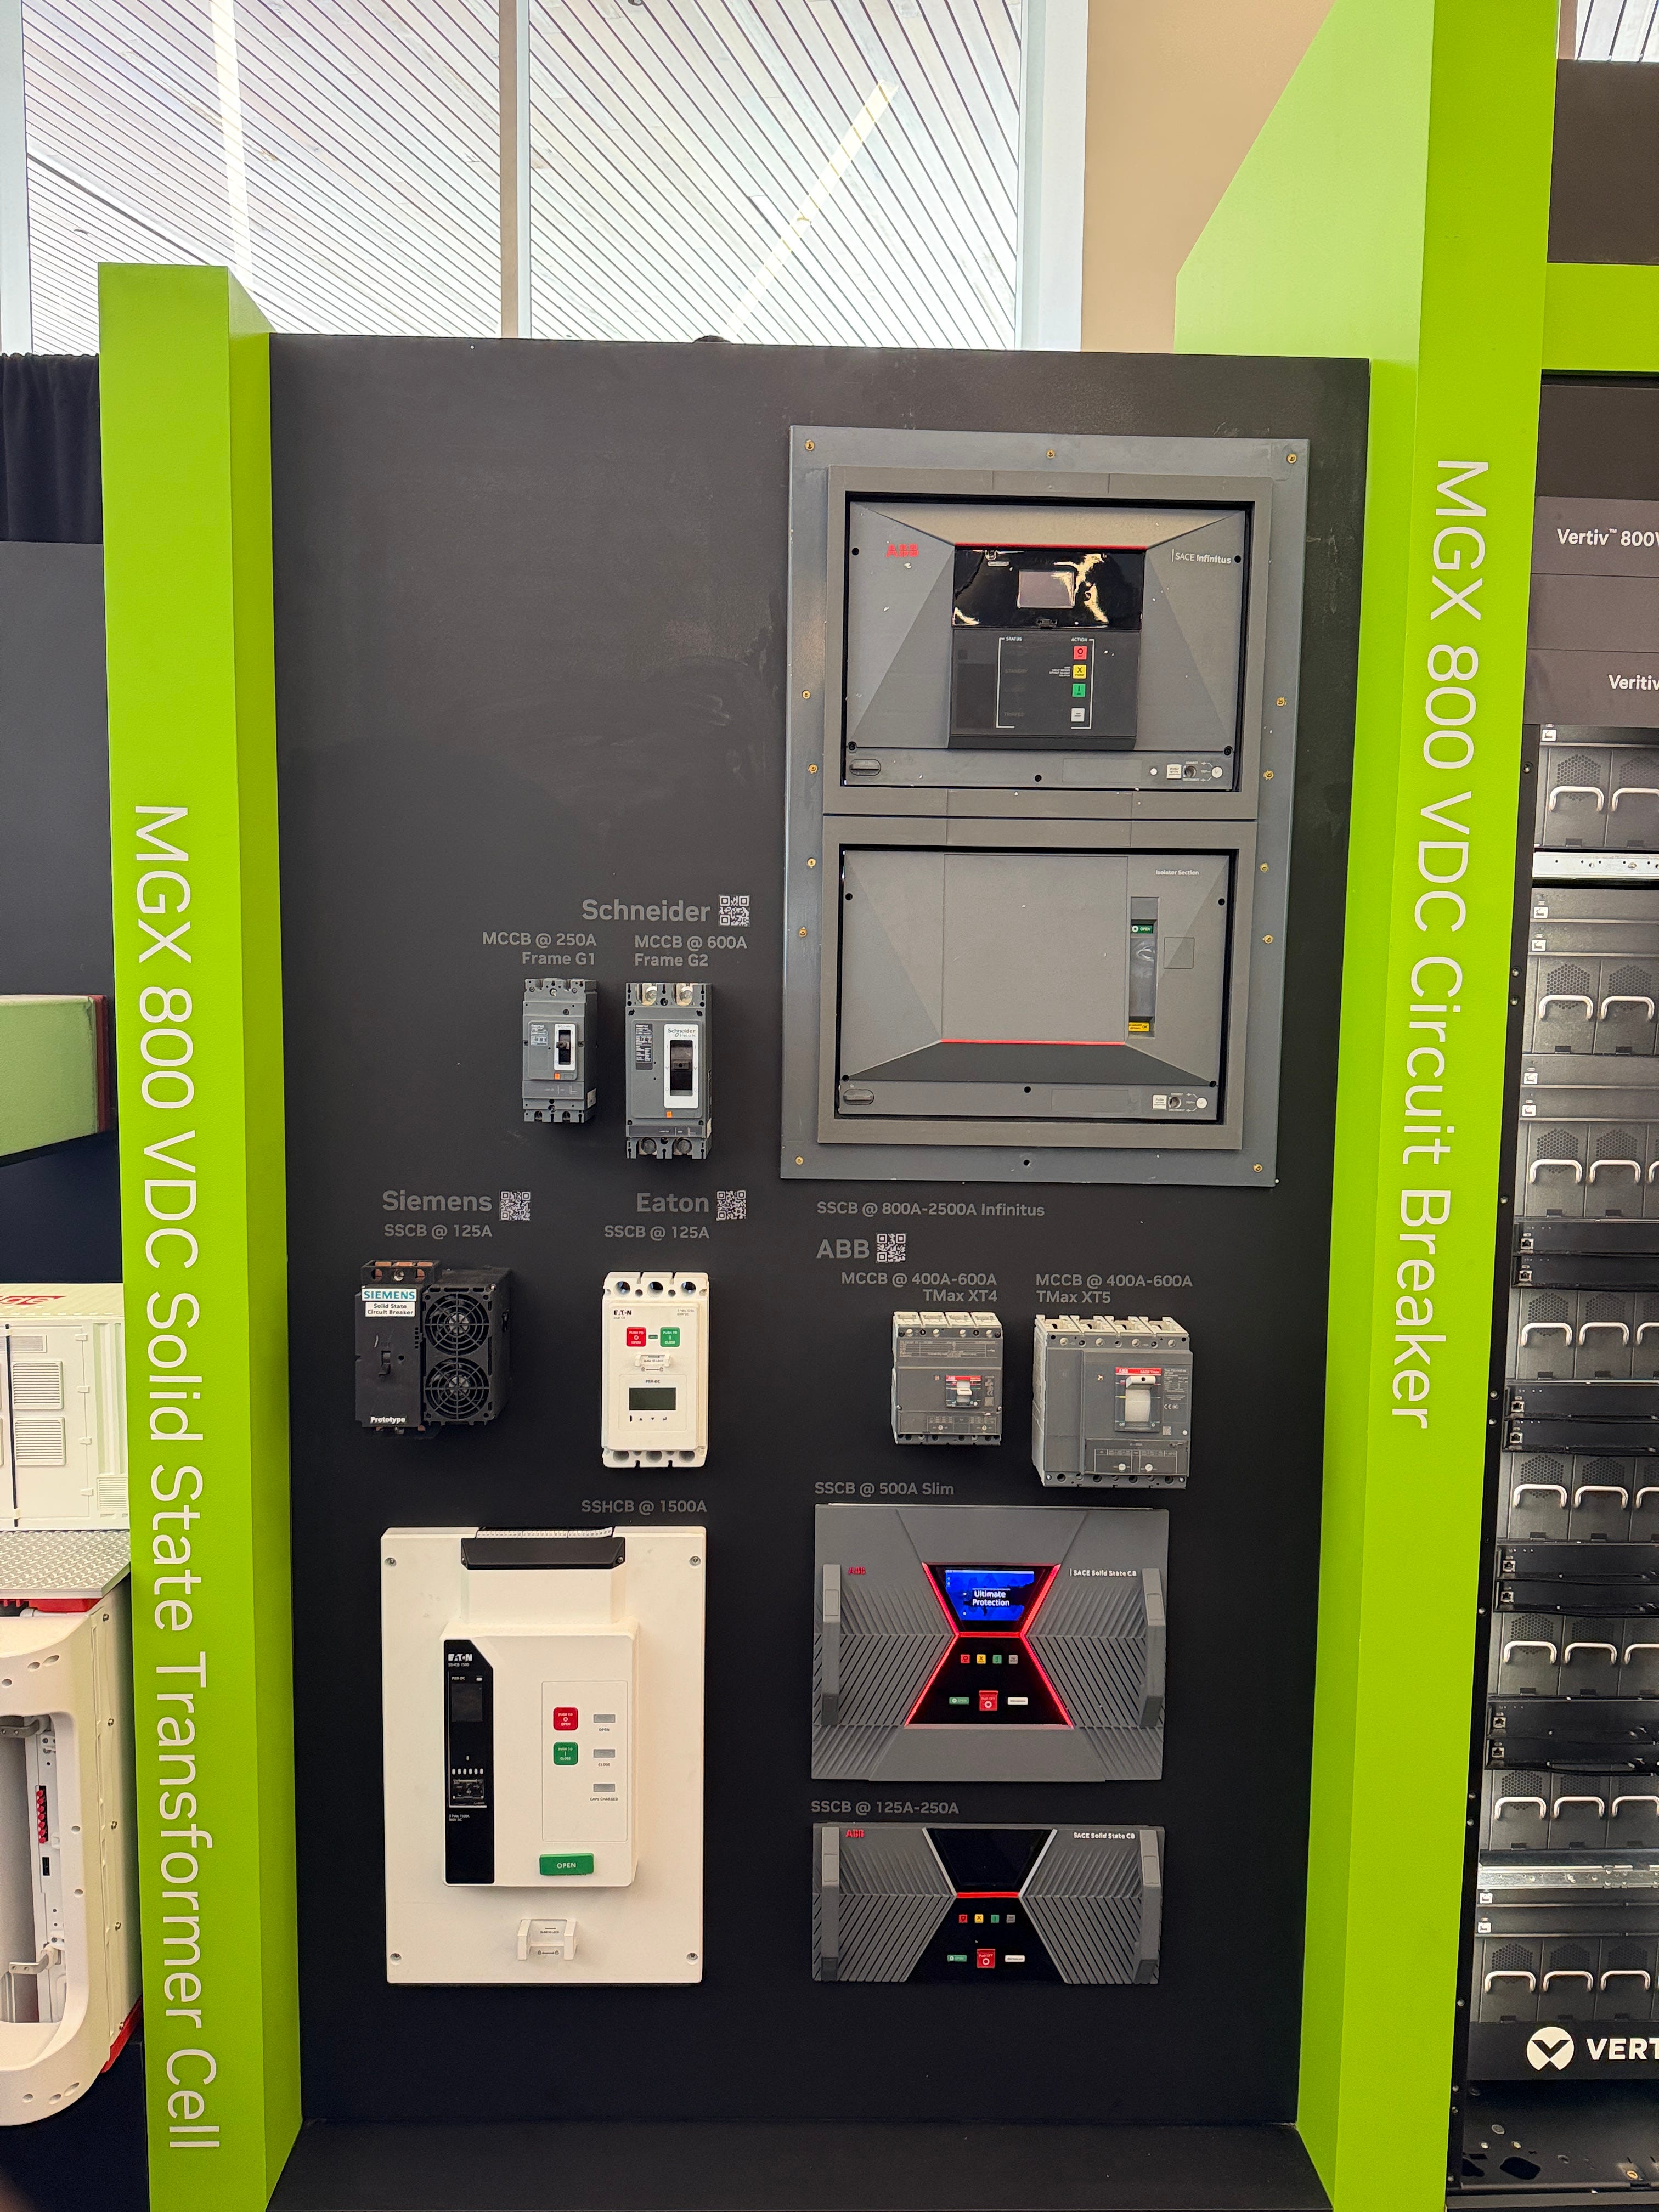
Nvidia’s Ian Buck says CUDA’s software ecosystem, GPU flexibility and annual Vera Rubin upgrades lower token costs as agentic AI pushes…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.