Monday, October 12, 2026

Back to today

From X

@calvinblissett 3 clicks

Calvin Blissett on X

$CHRD: 6.5x FCF, Good CEO, buying back lots of stock, low-cost pure play EP. 8% FCF yield at $60 WTI. No meaningful leverage CHRD trades at ~$142, market cap ~$7.74B, enterprise value ~$8.63B. Dividend yield ~3.7% ($5.20 annual base). Buyback/total shareholder yield is higher: policy returns ≥75% of adjusted free cash flow (mostly buybacks after the base dividend) at current low leverage (<0.5x). On 2026 guidance of ~$1.3B Adj. FCF, this implies a potential total cash return yield in the low-to-mid teens. Valuation is low: ~9.5x TTM P/E, ~7.6x forward P/E, EV/EBITDA ~3.2-3.6x, P/FCF ~6.5x. Analyst consensus PT ~$166-174 (~20%+ upside); highs to $193. Marcellus non-op sale (to POSCO, expected Q4 2026 close) provides ~$550M gross proceeds, sharpening pure-play Williston focus, boosting cash/flexibility for returns or balance-sheet strength, and removing a non-core asset. Reasons for future growth: Flat-to-low absolute oil volumes (maintenance program ~161 MBopd oil) but rising per-share metrics via efficiency and buybacks. Longer laterals (majority of program, including 4-mile) cut costs/breakevens and improve recovery; base production enhancements and lower declines support volumes with less capital. Pure-play focus post-sale plus disciplined consolidator role in the Bakken. Efficiency gains already drove material FCF improvements. LTM Owner’s Earnings (Buffett-style): Roughly Net Income + DD&A + other non-cash charges − maintenance CapEx (and normalized for WC/one-time items). For this E&P, nearly all CapEx is maintenance to offset natural declines, so Owner’s Earnings approximates free cash flow. TTM (to ~Jun 30, 2026): Operating cash flow ~$2.59B, CapEx ~$1.40B → FCF ~$1.19B. DD&A ~$1.54B; Net Income ~$841M. Company-reported adjusted FCF (preferred operational proxy) was strong in 1H26 (~$738M combined Q1+Q2) and has been running at an elevated rate. This is a rigorous, cash-based measure after the capital required to sustain the business. Expected next-12-months Owner’s Earnings: ~$1.3B adjusted free cash flow (company 2026 guidance, including derivatives, at $75 WTI / $3 HH for 2H). Why higher than LTM: stronger realized oil prices vs. prior periods, operational efficiencies (longer laterals, cost controls, base enhancements), volumes at/above high-end of prior guidance, and capital discipline (CapEx held ~$1.4B midpoint). The $550M Marcellus proceeds is one-time cash (not recurring earnings) that further supports returns and balance-sheet optionality. At ≥75% payout, this supports substantial shareholder distributions while maintaining a strong BS. Business simply: Pure-play Williston Basin (Bakken) E&P—largest operator there. Drills oil-focused horizontal wells, produces/sells crude, NGLs, and gas. High-quality inventory; shift to longer laterals improves economics. Management: Danny Brown (CEO; prior Oasis/Anadarko). Track record of efficiency, synergies, disciplined capital allocation, and per-share value creation. Capital allocation: Base dividend + aggressive buybacks under the 75%+ Adj. FCF framework (leverage-dependent). Share count reduced meaningfully; cumulative returns large relative to market cap. Maintenance production focus. Risks: Oil price sensitivity/volatility (primary driver), basin decline/inventory longevity, execution on laterals or M&A, regulatory factors in ND/MT, energy transition headwinds. Margin of safety & upside: Low leverage, high cash generation even at moderate oil prices ($60-70 WTI still supports solid FCF/returns), conservative CapEx, and efficiency gains provide protection. Upside from multiple expansion toward peers/history, continued buyback accretion to per-share metrics, operational outperformance, oil strength, and pure-play clarity. Consensus implies ~20%+ near-term upside; higher in stronger commodity scenarios. Attractive FCF yield + value profile in E&P. Figures based on company results/guidance, market data, and analyst notes as of early October 2026. Oil prices and execution remain key variables.
@StableBread

Fajasy on X

BWX Technologies $BWXT is in military base power three ways, through (1) Project Pele, a prototype reactor it’s building for the Pentagon, (2) the TRISO fuel its microreactors run on, and (3) Janus, the Army program that chose $BWXT’s commercial reactor for Fort Campbell, Kentucky. Pele is a 1.5-megawatt (MW) transportable, gas-cooled microreactor built for the Pentagon’s Strategic Capabilities Office under a 2022 award. $BWXT delivered its full TRISO fuel core to Idaho National Laboratory (INL) in December 2025, received the Department of Energy’s (DOE) preliminary safety approval in September 2026, and targets delivering the reactor to INL in 2027. TRISO (tri-structural isotropic) fuel, which the Department of Energy calls “the most robust nuclear fuel on earth,” packs uranium into particles coated in carbon and ceramic layers. $BWXT produces TRISO at Lynchburg “in the hundreds of kilograms quantities,” Joe Miller, president of Government Operations, said at its Investor Day on September 29, 2026. It also supplied the fuel for Antares, a microreactor startup whose reactor was the first new reactor to reach criticality (a self-sustaining chain reaction) under DOE’s reactor pilot program in June 2026. POWER magazine, a power-industry trade publication, reports $BWXT is “the only Janus vendor that self-supplies its TRISO fuel.” $BWXT is also negotiating a commercial TRISO plant in Wyoming with Kairos Power, an advanced reactor developer, at up to $500M of capex. CFO Mike Fitzgerald said at Investor Day that $BWXT needs to see high-assay low-enriched uranium (HALEU, the 5-20% enriched uranium most advanced reactors need) become available before committing to the plant, and “probably will not make a decision on that for a little while.” The Army chose BANR (the BWXT Advanced Nuclear Reactor), a 20 MWe (megawatts of electricity) gas-cooled design scaled up from Pele, for Fort Campbell. $BWXT plans to start construction at the site in late 2028 and have the reactor running in the early 2030s. Three details matter here: 1) No contract value: $BWXT’s release describes “a phased contracting approach.” For comparison, the Janus agreement for Radiant, a microreactor startup, is worth up to $750M. 2) $BWXT will own the reactor: The Army chose vendors “to own, construct and operate nuclear microreactors” ($BWXT’s release), under fixed-price, milestone-based agreements in which the Army pays at milestones rather than buying power. 3) Not first in line: With operation in the early 2030s, $BWXT’s reactor won’t meet the September 30, 2028 deadline a May 2025 executive order set for an Army-regulated reactor running on a U.S. military base. Radiant and Antares, two of the other Janus vendors, both target 2028 for their first reactors. After Radiant’s agreement, $1.45B of the program’s $2.2B is left, and an even split among the other four vendors would give $BWXT ~$360M over fiscal 2027-2031, or $72M/year, under 2% of 2026 revenue guidance.
@StableBread 6 clicks

Fajasy on X

The S&P 500 lost 18% in 2022, and the Bloomberg U.S. Aggregate, the main U.S. bond index, lost 13%, its worst year since it began in 1976. Over the same year, $XLE, the S&P 500 energy sector ETF, returned 64%, gold was flat, and cash earned ~1.5%. Now what if I told you there's a framework that would've said to own cash and energy in 2022, not stocks and bonds? That framework is called Gave's Four Quadrants, after Charles Gave, co-founder of Gavekal, a macro research firm. It uses two ratios built from market prices, the S&P 500 vs. Oil and Gold vs. Treasuries, to place the economy in one of four environments, and it describes what to own and what to avoid in each. Here's how stocks, bonds, gold, and cash tend to perform in each environment: → Deflationary boom: Stocks, bonds, and cash rise, and gold underperforms. → Inflationary boom: Stocks and gold rise, cash does very little, and bonds fall. → Deflationary bust: Bonds and cash rise, gold stays fairly stable, and stocks fall. → Inflationary bust: Gold and cash rise, while stocks and bonds fall. In my backtest of Gave's rules from 1970 to September 2026, a portfolio split equally between cash, the S&P 500, and either 10-year Treasuries or gold, whichever the framework favored, would have returned 5.7% per year after inflation. Its max drawdown was 28%, vs. 54% for the S&P 500. As of the end of September 2026, the two ratios place the U.S. in an inflationary boom phase. But since January 2025, the S&P 500 to gold ratio has been below its 7-year average, which has often come a few months before the S&P 500 to oil ratio drops below its own 7-year average. If that happens, the U.S. is back in an inflationary bust phase, like 2022. So how do you read the two ratios yourself, and what do they say to own today? That's what I walk through in my new ~20-minute video!
@StableBread

Fajasy on X

The Navy plans to buy more ships, and BWX Technologies $BWXT doesn’t charge a set price per reactor. $BWXT makes the fuel, reactor cores, steam generators, and other reactor components for the Navy’s Virginia- and Columbia-class submarines and Ford-class carriers. $BWXT now produces two to three of these reactors/year, Joe Miller, president of Government Operations, said at its Investor Day on September 29, 2026. The Navy buys under multi-year pricing agreements, so orders arrive in large blocks: → February 2025: $2.1B of naval reactor component contracts. → July 2025: $2.6B, including options. → May 2026: $1.45B, mostly long-lead material (parts ordered years before a ship is built) under the first of five annual task orders through 2030. → October 2026: $189M of naval fuel, to be completed by August 2027. $BWXT’s plants carry large fixed costs, so final pricing depends on how many ship sets (all the reactor components for one ship) the Navy orders, CFO Mike Fitzgerald said at Investor Day. The Navy’s 30-year shipbuilding plan, released in May, calls for (1) “buying two attack boats per year for the next 30 years,” meaning Virginia-class submarines, (2) a new carrier every four years instead of every five, and (3) 15 nuclear-powered Trump-class battleships, per USNI News, the U.S. Naval Institute’s news service. $BWXT’s own read of the plan is naval growth of 4-6%/year from the existing ship classes. Each Ford-class ship set takes ~8 years to deliver, so ordering a carrier every five years left gap years with one ship set in $BWXT’s plants instead of two. CEO Rex Geveden said on the Q2 call that the four-year cadence takes out “that revenue bathtub that we’ve been going through” and has “a bigger volume impact than even adding a battleship.” The next carrier’s long-lead orders come in 2028, but Fitzgerald said at Investor Day the faster cadence won’t really show up in $BWXT’s numbers until around 2030. A Trump-class battleship would use one Ford-class reactor (a carrier uses two), so $BWXT could build the reactor on its existing lines, but Congress still has to fund the program. Fitzgerald said $BWXT’s 2030 targets exclude the battleship program, so congressional funding would be extra growth.

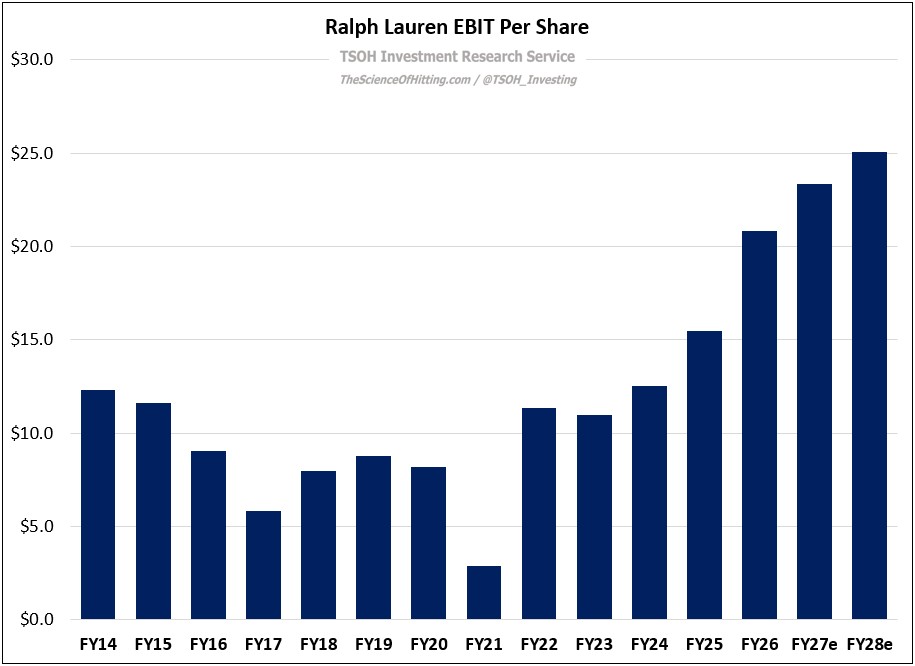
“Is Ralph Lauren Still Relevant?”

Ralph Lauren’s 2017 CEO change put Patrice Louvet in charge of reversing nine quarters of same-store sales declines and restoring the…
DB · long

Deutsche Bank AG

Deutsche Bank trades at 1.0x tangible book, with projected ROTCE above 13% and a favorable setup ahead of earnings.
Deep Dive: Inter & Co

Inter & Co, Brazil’s second-largest neobank, grew over 20% with controlled delinquencies and 15% book-value compounding while trading at…
A temporary glitch?

Coupang’s November 2025 cybersecurity breach tests whether a selloff is temporary despite its 28% Korean e-commerce share, 14 million-plus…
You Understand Now, Why You Came This Way

Brazil’s October 25 runoff puts Bolsonaro’s likely victory at the center of a bullish regional-stock case; Golar LNG (GLNG) also reports…
TSOH Weekly Roundup (10/09/2026)

Paramount Skydance’s debt-heavy Warner Bros. Discovery acquisition, streaming bundle pricing and alcohol-industry diversification anchor…
Publications we follow

Every publication on this site, hand-picked.

129 publications

Newsletters 107

X accounts we follow

Every account on this site, hand-picked.

88 accounts

Investor letters we follow

189 firms

Sectors

Ordered by how often our editor reaches for them.