Legence trades at 10.4x EV/aEBITDA with a $5.7 billion backlog, as AI data center installations drive growth and expand its maintenance…
S Monte Independent Investment Research 2 clicks
OceanaGold trades below its mine value despite US$655 million of cash and no debt, with production set to dip before Wharekirauponga begins…
SA  The Bullionaire 1 click
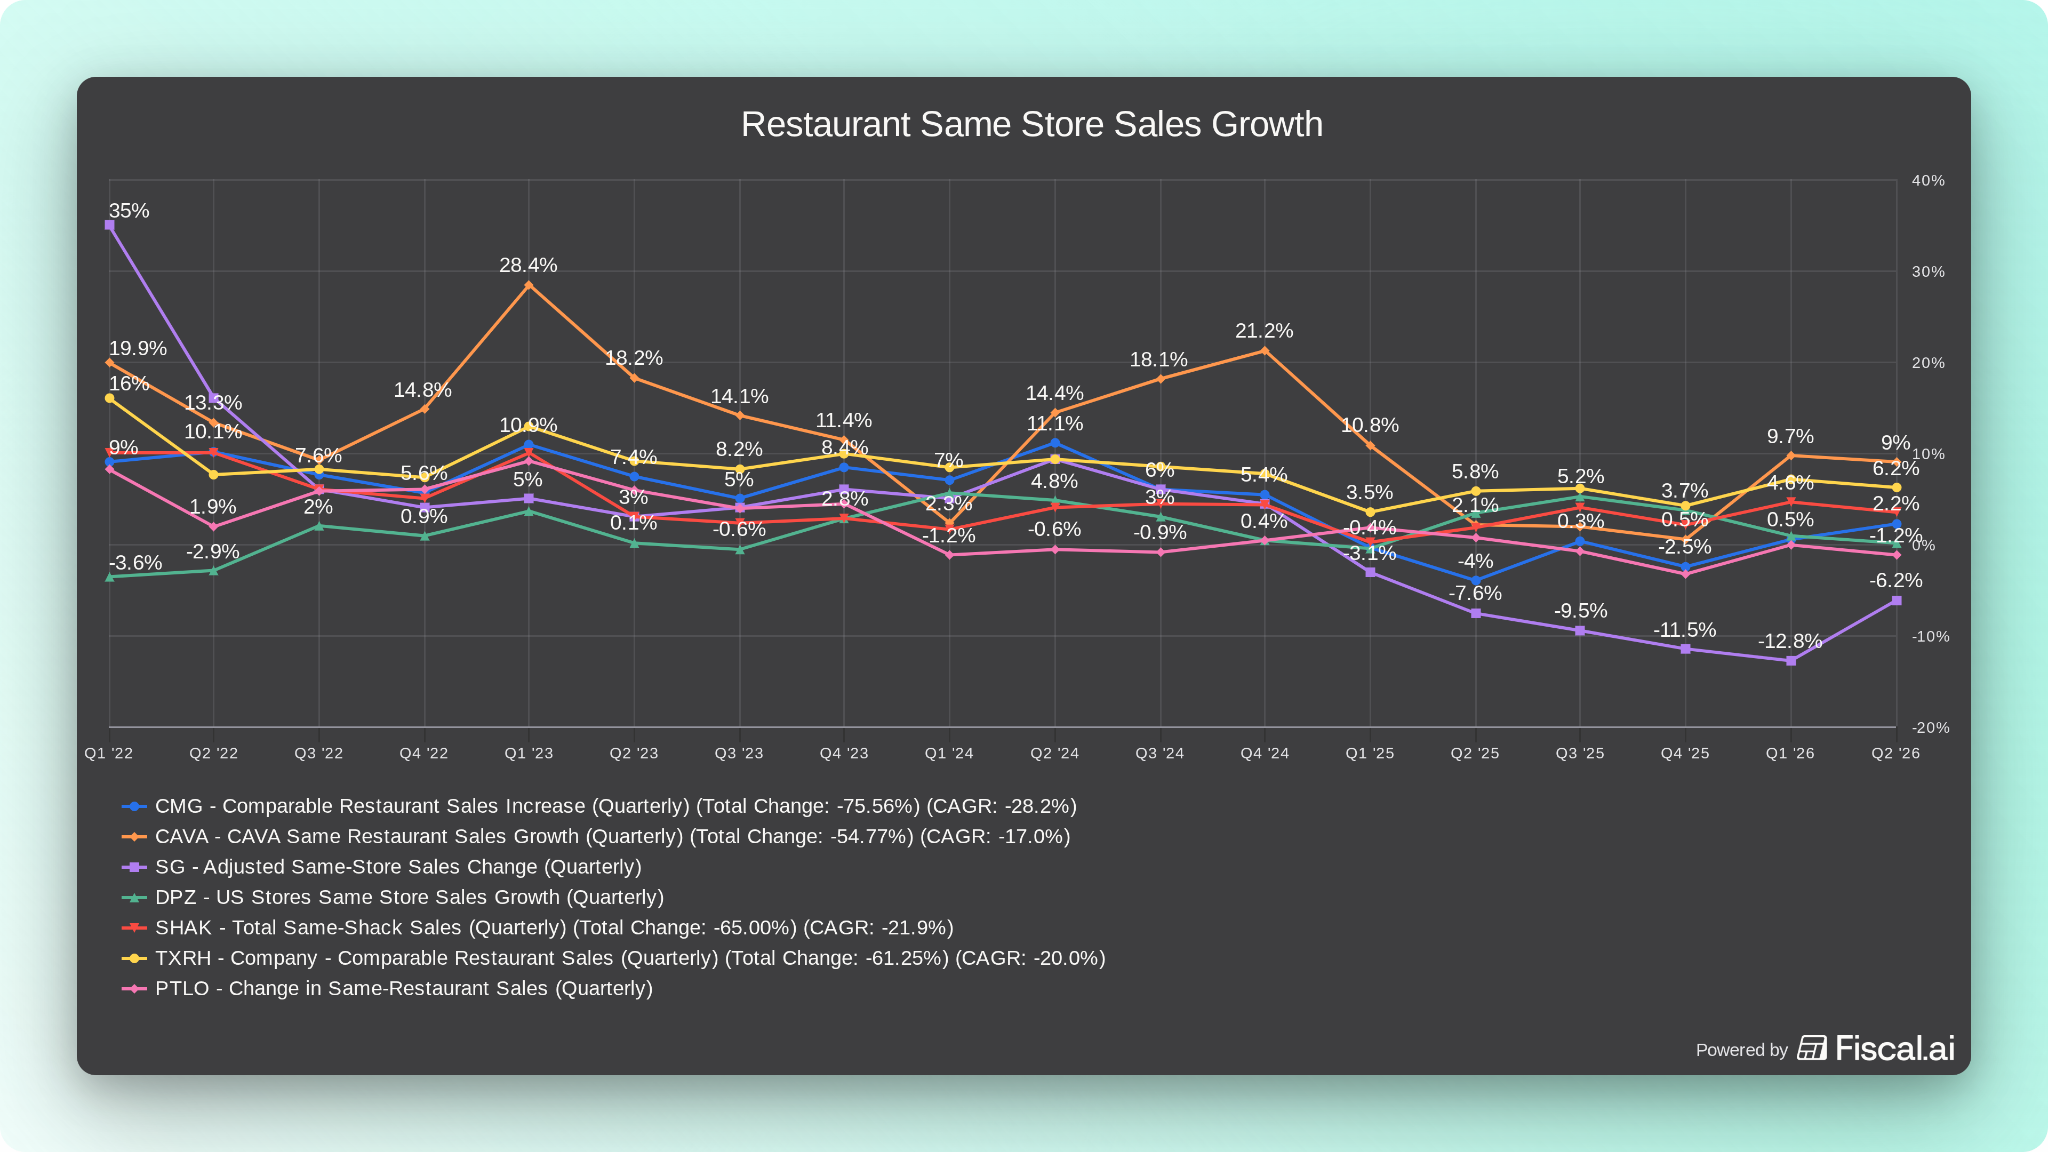
Cava’s $3 million AUVs, 25.1% restaurant margins and sector-leading same-store sales support its expansion case as awareness rose from 40%…
S Emerging Moats Research 6 clicks
Special-situations survey profiles 26 activist, capital-return, M&A and strategic-alternative catalysts, led by buybacks at Under Armour,…
S Latticework by MOI Global 2 clicks
Millrose told Goldman its Lennar purchases had rent-to-own tenants lined up, but most analyzed homes were advertised for rent and showed…
BL Hunterbrook 4 clicks
Golar LNG ordered a $2.45 billion fourth FLNG vessel, targeting 3.5MTPA of capacity and $400 million in annual EBITDA under a 20-year…
S Monte Independent Investment Research
Maase, a $5B AI infrastructure company with sub-$50M annualized revenue and persistent losses, faces governance concerns over super-voting…
SA  Wolf Report 1 click
Salad and Go filed Chapter 11 after its Texas and Oklahoma expansion failed, seeking to sell 65 leases to Dutch Bros for $105 million as 7…
S PETITION 3 clicks
Astronics targets $1.02 to $1.04 billion in 2026 revenue after adjusted operating margin reached 20.3%, with Boeing representing 12% of…
SA  Jordan Aquilina
Golar LNG’s fourth FLNG vessel targets 3.5MTPA capacity and a 2029 delivery, supporting projected adjusted EBITDA above $1 billion in…
S Monte Independent Investment Research 1 click
 ABG · long
Asbury Automotive Group's changed setup and underperformance versus other public dealers form the basis for a renewed long thesis.
BL Value Investors Club
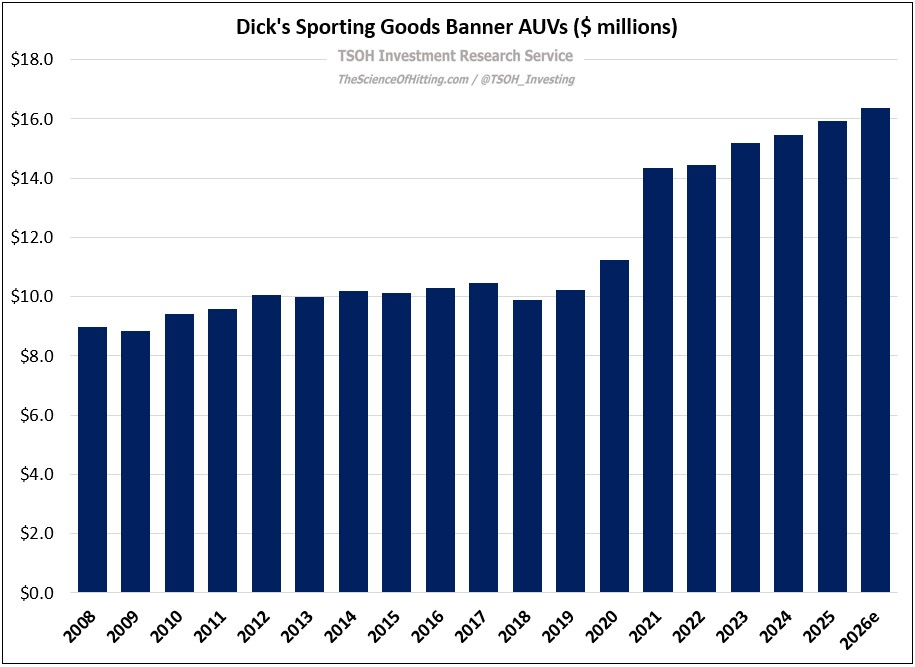
TSOH Weekly Roundup covers Ralph Lauren’s $1 billion distribution pullback, Peloton’s $2,195 foldable treadmill and $800 million…
S TSOH Investment Research 3 clicks
Ouster began coverage at Accumulate as lidar revenue rose 56% in Q2, while annual cash burn near $80 million has driven an 86% share-count…
BL Cestrian Capital Research 5 clicks
AAON's BASX data-center cooling business targets $1 million to $1.5 million per megawatt, with new capacity and backlog conversion expected…
S Monte Independent Investment Research 6 clicks
Vista Energy's Q2 2026 production rose 32% and revenue 89% as Vaca Muerta acquisitions expand its Argentine export platform and cash…
SA  Alan Galecki 4 clicks
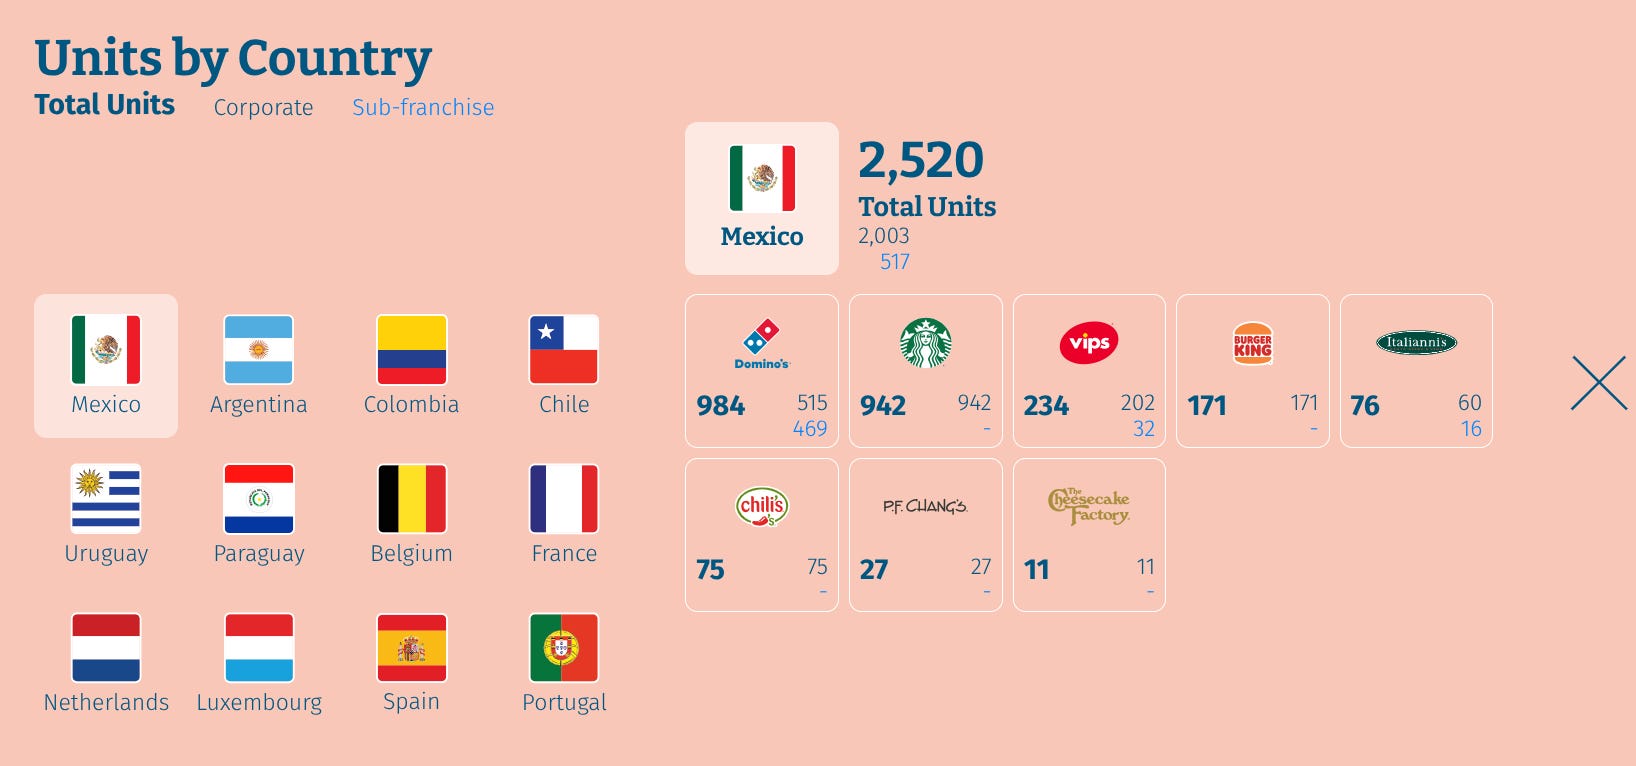
Alsea, Mexico’s Starbucks, Domino’s and Burger King franchise operator, trades at 5.4x EBITDA while funding remodels, Mexican expansion and…
S Emerging Moats Research
ASR’s $992 million Motiva acquisition broadens its South American airport network after a 25% YTD decline, while its 8.5% FCF yield and…
SA  C Jessen 3 clicks
Firefly Aerospace ended Q2 2026 with $1.5 billion backlog and a 2.49x book-to-bill ratio, adding lunar, defense and launch contracts for…
S Monte Independent Investment Research 15 clicks
Birkenstock targets 13–15% annual revenue growth through FY2028, driven by APAC expansion and closed-toe footwear, while trading at 13.44…
SA  Roman Vitasek 4 clicks
ZIM’s proposed deal carries a claimed 23% spread and 110% IRR by Q4 2026, with Q3 and Q4 dividends potentially raising returns if closing…
S Calvin Blissett 13 clicks