An open letter to Senator Elizabeth Warren
NAIC oversight missed Delaware Life’s $13.34 billion affiliated-bond exposure and permits capital treatment that props up Brighthouse’s Delaware captive.
NAIC oversight missed Delaware Life’s $13.34 billion affiliated-bond exposure and permits capital treatment that props up Brighthouse’s Delaware captive.
Ngl I'm the most bulled up I've been in a while here. Not bullish the entire market and $SPY, but bullish stuff like breadth, $RSP, low vol stuff. Breadth has crashed, sentiment is in the toilet, and October is historically pretty strong seasonality wise. https://t.co/Q3nWJ8IpAN
@SW_Resurgo I dunno, I see lots of very real cases of people doing shit like this. Remember the guy who went all in on $PDD and then had a royal crash out?
@27XVII $CSHR for bitcoin etfs
$CXW got a new President/CEO today. https://t.co/7WpulDuHkg
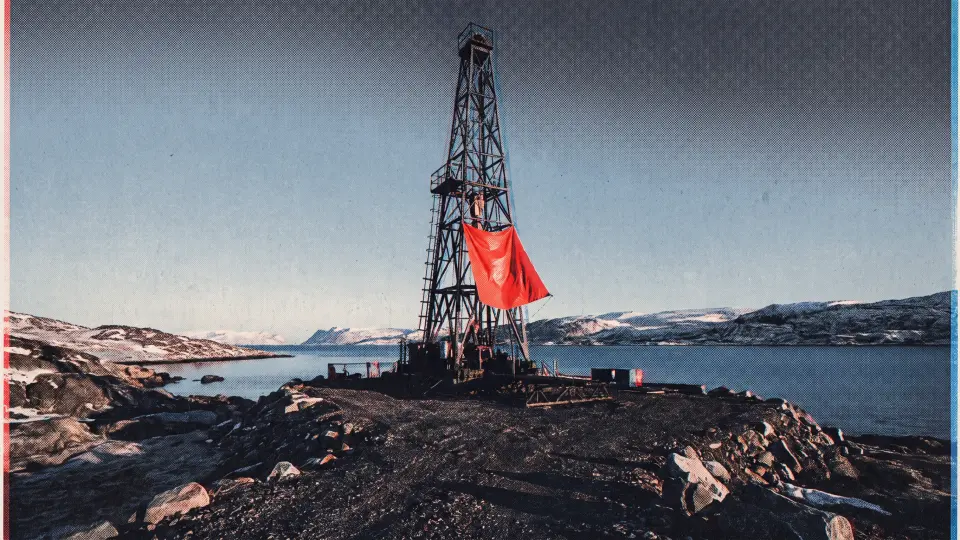
Greenland Energy Company holds 2.1 million acres in the Jameson Land Basin, but drilling permits, political risk and warrant dilution cloud…
 Ron Ferrie
Hindsight Capital tests crisis-era investment decisions using anonymized company financials, including TransDigm, Halma and Texas Pacific…
Neighborhood Intelligence, NXH, faces a cash shortfall after failed and restructured acquisitions, as losses and limited financing options…
 Vince Martin 1 click
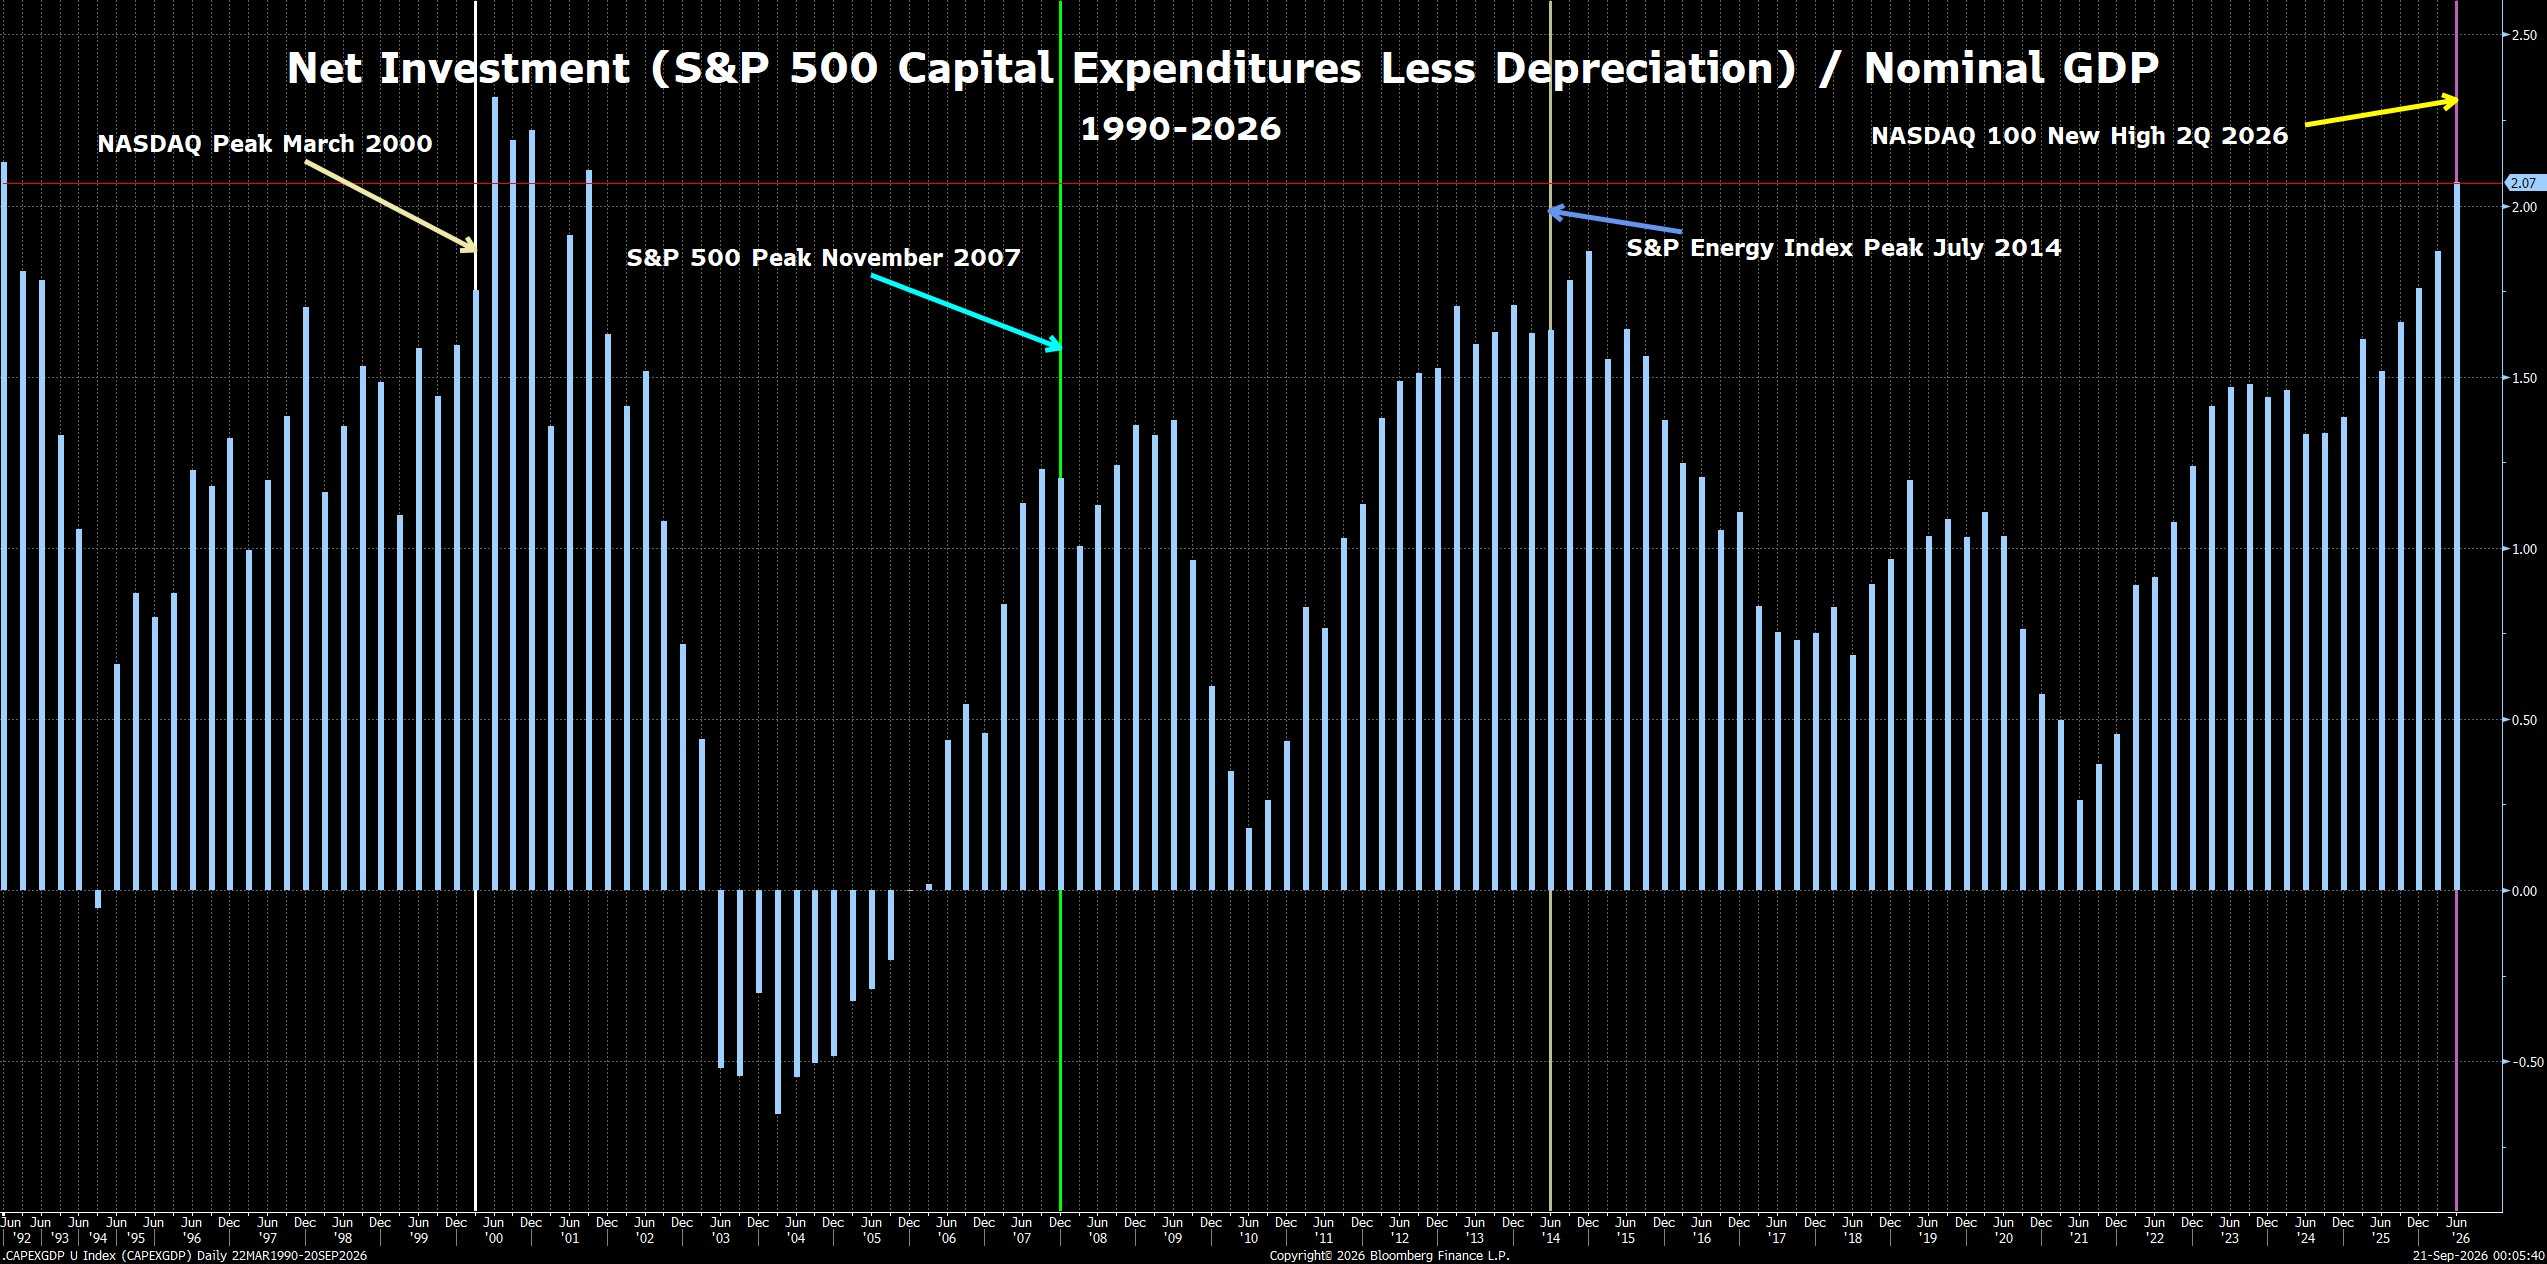
Microsoft, Amazon, Oracle, Meta and Alphabet face another two years of record AI data-center investment amid $3 trillion in commitments,…
Honeywell Aerospace, newly spun off as HONA, fell 41% from post-listing highs after Q2 2026 as supply-chain bottlenecks delayed revenue…
VersaBank uses cash holdbacks and put-backs to buy point-of-sale loan cash flows, with C$7 billion in assets and AI-enabled real-time…
GitLab's Q2 FY2027 beat and raised guidance reflect large deals, paid consumption growth and AI demand, while valuation rests on revenue…
 Research and Value 3 clicks
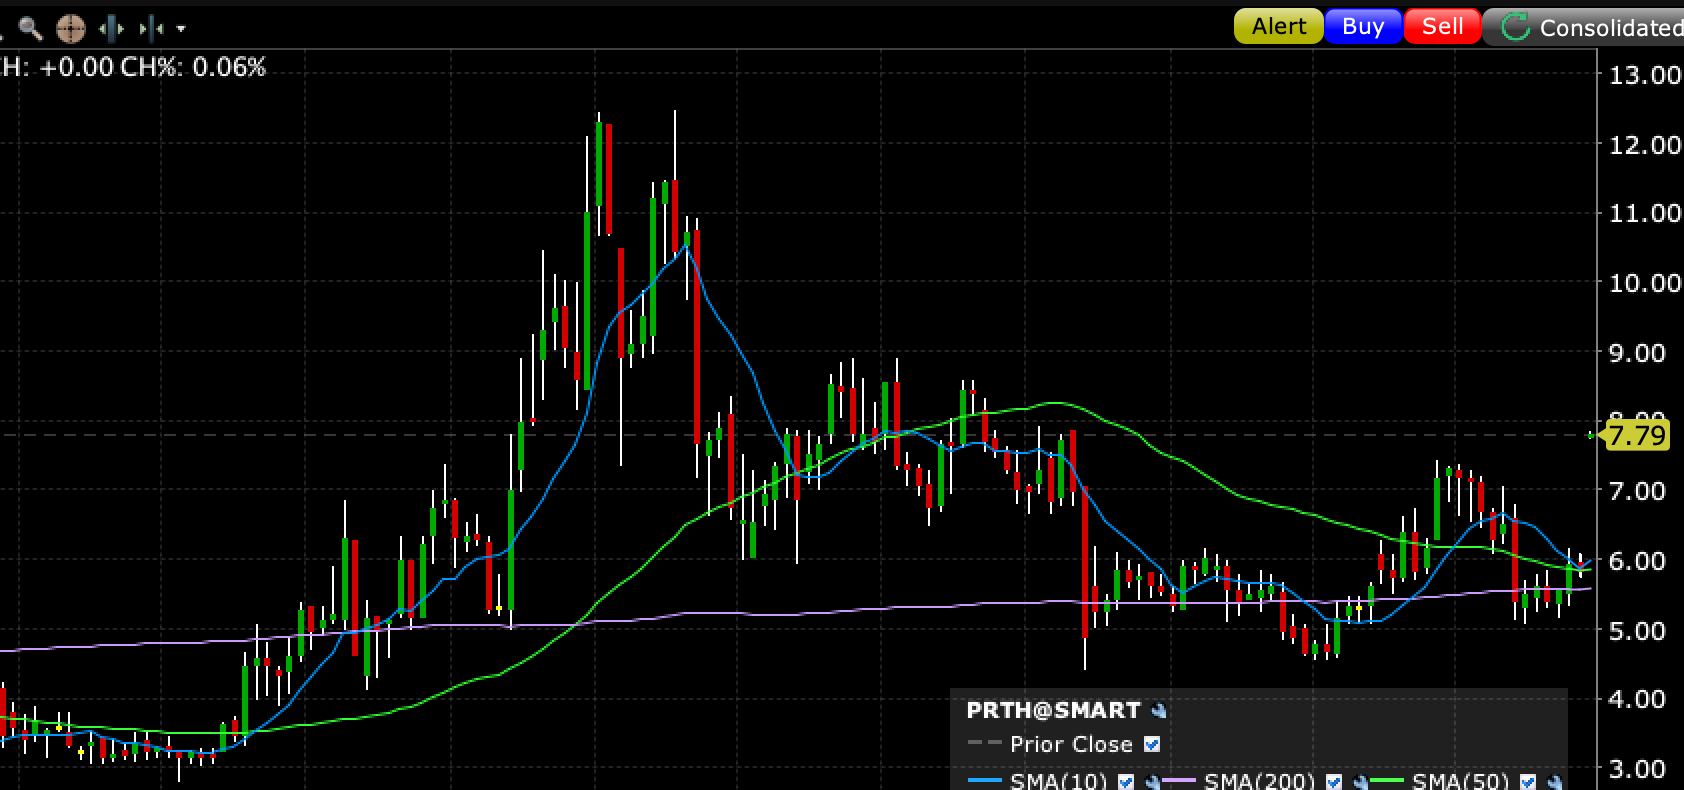
FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.
Steve Eisman says AI companies are reviving Enron-era off-balance-sheet and circular financing, alongside concerns around Oracle and Blue…
Reddit’s DCF values shares at $225, driven by international ARPU expansion from $2.2 to $8.3 by 2035 and 38% operating margins.
 THC · long
Tenet Healthcare generates roughly two-thirds of profits from hospitals and one-third from ambulatory surgery centers.
Meta’s Muse reached 2.8 million downloads in two weeks, using AI agents to automate insurance shopping and erode customer inertia that…
Oklo shares have fallen 77% since October 2025 as commercialization slips beyond 2027, revenue estimates fall and dilution continues.
 Ian Bezek 5 clicks
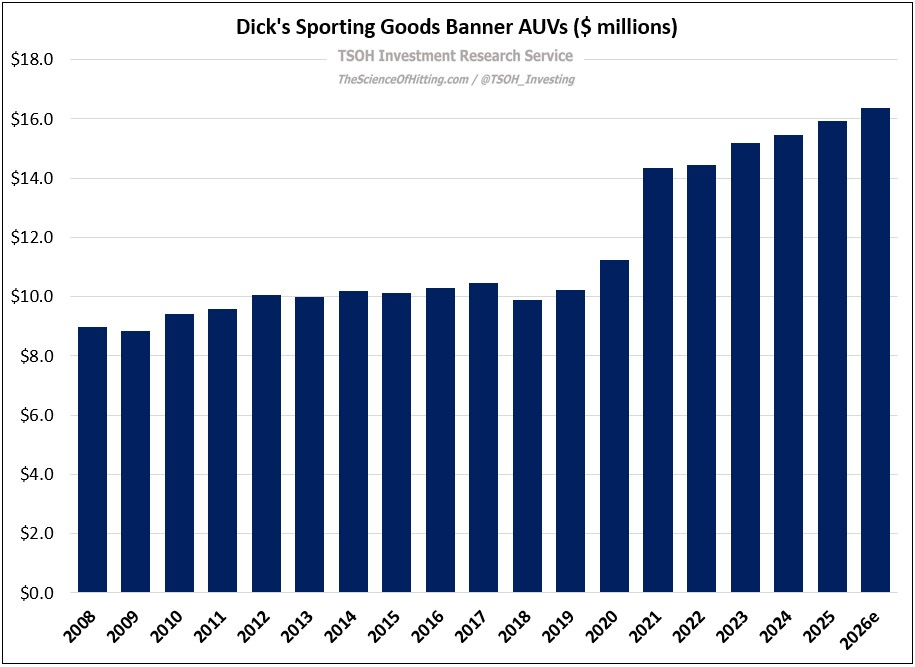
TSOH Weekly Roundup covers Ralph Lauren’s $1 billion distribution pullback, Peloton’s $2,195 foldable treadmill and $800 million…
IonQ's Q2 2026 revenue rose 287% to $80.1 million, but durability hinges on its $485 million RPO and enterprise adoption for production AI…
 Deep Value Investing 2 clicks
Rocket Companies combines Redfin, Rocket Mortgage and Mr. Cooper into an end-to-end homeownership platform, adding mortgage servicing fees…
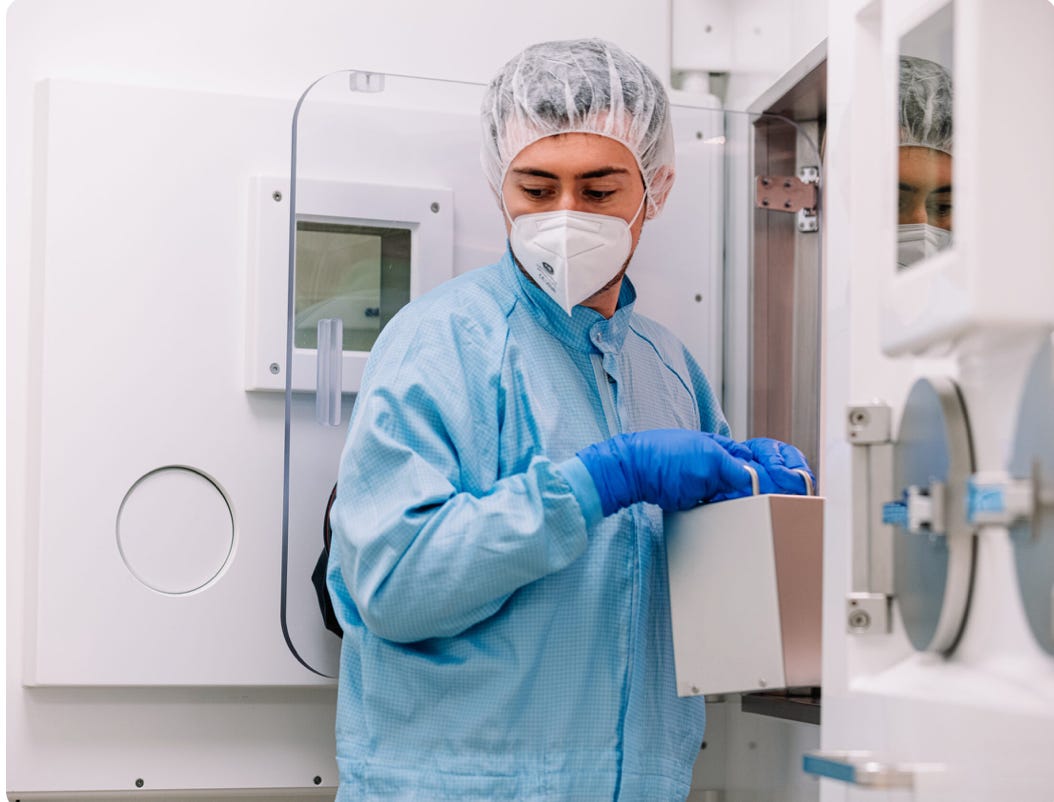
Eckert & Ziegler trades near €12, about 14 times expected earnings, as its isotope supply business expands with radiopharma demand despite…
Mach Natural Resources' Q2 distributable cash fell to $60.1 million as development spending rose, prompting a distribution cut; its units…
Berkshire Hathaway's succession elevates Greg Abel to CEO and Howard Buffett to chairman, reinforcing its acquisition, buyback and…
 Jim Sloan 6 clicks
Ouster began coverage at Accumulate as lidar revenue rose 56% in Q2, while annual cash burn near $80 million has driven an 86% share-count…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Bullionaire
 The Curious Analyst
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.