Adobe’s fiscal 3Q26 revenue grew 13%, while ARR growth slowed to 9.3% excluding Semrush.
S Speedwell Memos Sep 14 2 clicks
Amazon’s refrigerated same-day network has lifted monthly perishable customers roughly 50%, using grocery frequency to deepen loyalty and…
S scuttleblurb Sep 14 1 click
Cestrian initiated Joby Aviation at Accumulate and upgraded Applied Materials and Broadcom to Accumulate for the week ended 11 September…
BL Cestrian Capital Research. Sep 14
Oracle’s $88.3 billion net debt and $90-95 billion capex plan pushed five-year CDS to 215 bps, despite 121% OCI growth and a $664 billion…
BL Cestrian Capital Research. Sep 14
MKS Instruments posted $1.25 billion in Q2 revenue and is expanding Penang capacity for a $200 billion to $250 billion wafer-fab-equipment…
SA The Straits Strategist Sep 14 Adobe’s fiscal 3Q26 revenue grew 13%, while ARR growth was about 9.3% excluding Semrush.
BL Speedwell Research Sep 14 1 click
Enel Chile uses battery storage and grid management to turn renewable oversupply into flexibility, lifting H1 2026 EBITDA 3.9% and net…
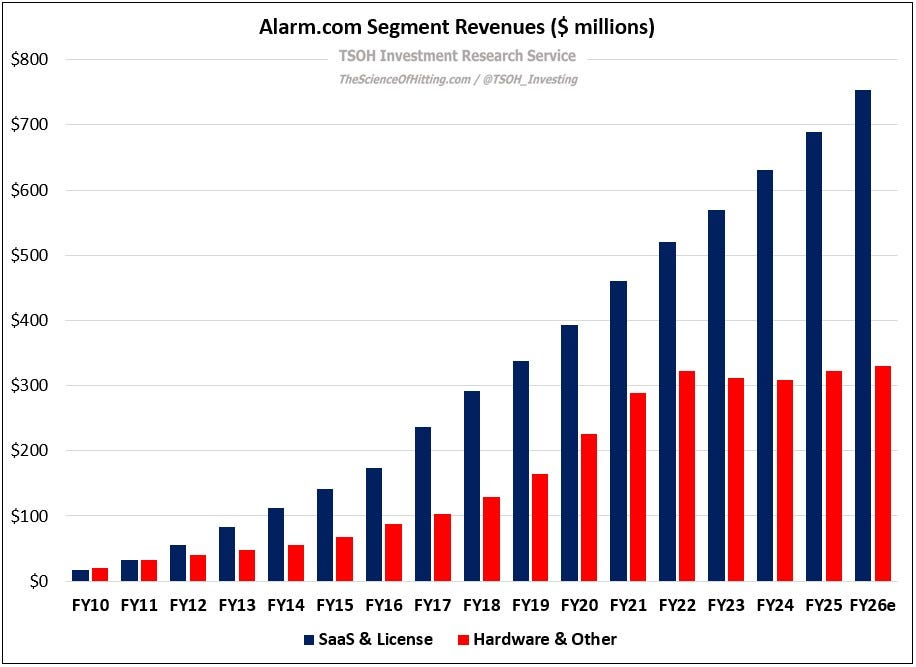
SA Ryan Canady Sep 14 4 clicks Alarm.com, founded after CEO Steve Trundle’s bad home-security experience, has fallen from $105 in 2020 to about $55, testing whether…
S TSOH Investment Research Sep 14 1 click
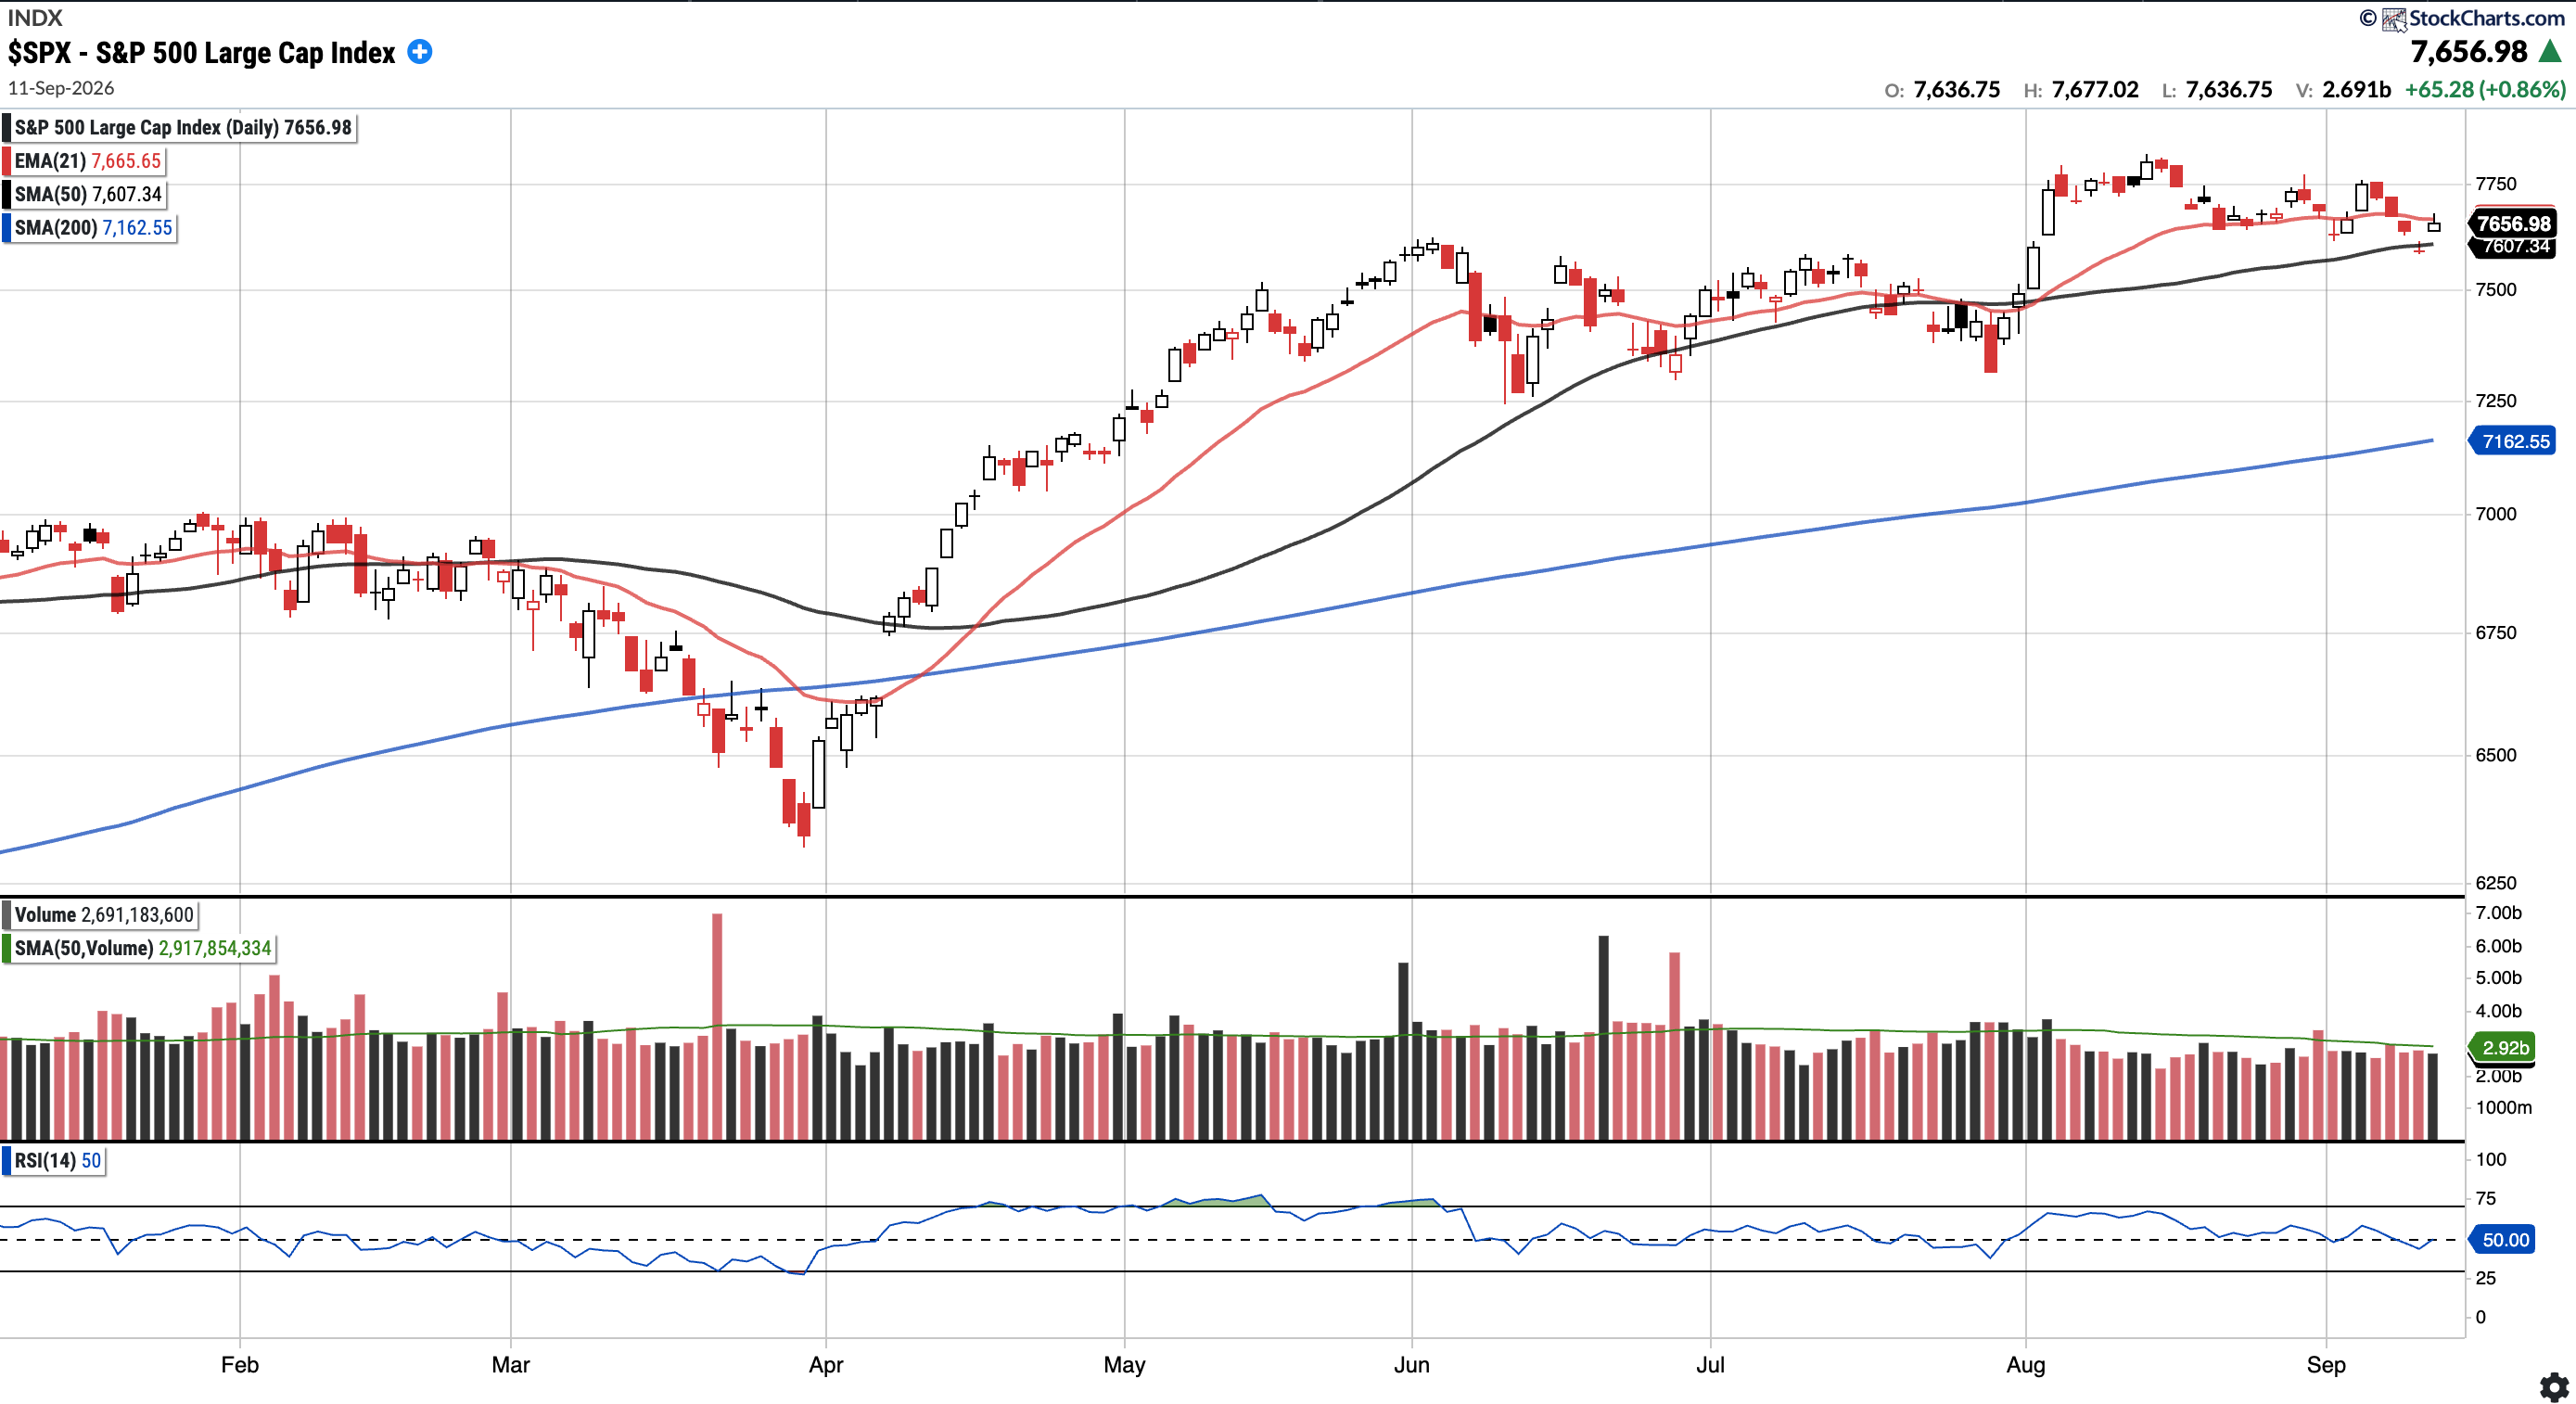
The week of September 14 features the FOMC decision, retail sales and housing data after the S&P 500 fell 0.8%.
S SixSigmaCapital: Navigating the Financial Markets Sep 13 3 clicks
Netflix is using AI visual effects and dubbing to cut production costs, expand global distribution and reinforce its recommendation-driven…
S Bearhold Research Sep 13 1 click
TYL · long Tyler Technologies, TYL, is positioned as a resilient govtech software provider if AI disrupts enterprise SaaS.
BL Value Investors Club Jun 16
Booking Holdings trades at 19x earnings, its lowest since 2022, after a 20% annual decline, with the thesis resting on durable online…
S Capitalist Letters Sep 13 4 clicks
Oak Bloke’s 2026 picks have returned 37% in GBP, with AltynGold, Geiger Counter, Silvercorp and China-focused trusts still rated buys…
S The Oak Bloke Sep 13 3 clicks
Nintendo expects software, digital sales and character licensing to drive growth, with FY2027 revenue forecast at ¥2.05 trillion and…
SA LL Insights Sep 13 Ten-year Treasury yields breach 4.9% as Steve Eisman discusses AI fears, OpenAI's price cut, Oracle's 30% revenue growth and Tesla's…
YT Steve Eisman Sep 11 2 clicks
USA Compression targets nearly 30% full-year EBITDA growth as JW Power synergies, telemetry and maintenance reduce costs; its units yield…
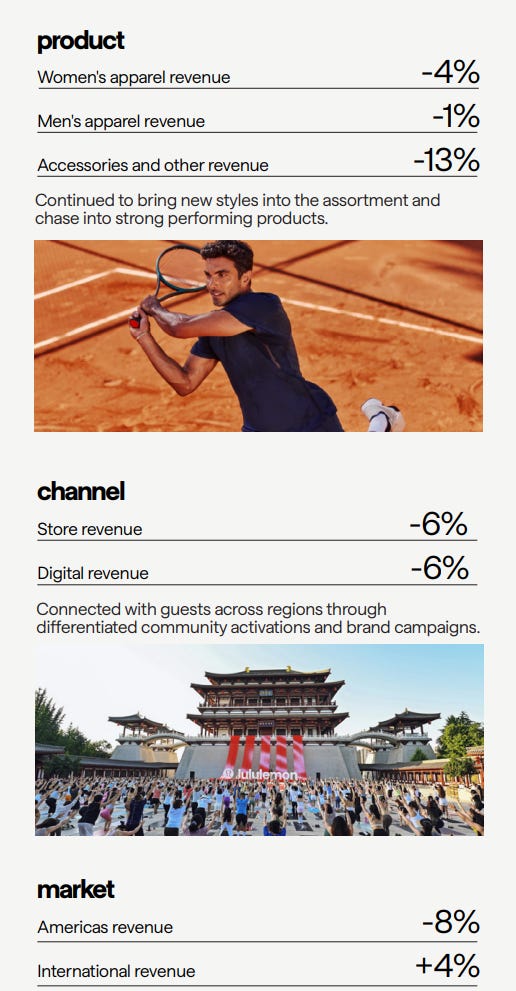
SA Ron Ferrie Sep 11 3 clicks Lululemon’s North American sales, margins and legging demand are falling as Alo and Vuori gain share, leaving its brand moat and depressed…
S Hated Moats Sep 11 2 clicks
Chevron’s 2027 EPS could be underestimated by about $4.50 per share if U.S.-Iran conflict keeps oil near $100 rather than forecast $74 to…
SA Envision Research Sep 11 1 click Lululemon’s growth stalled as affordable-luxury apparel brands face fading post-Covid demand, cheap social-media influence and China…
S MBI Deep Dives Sep 11 2 clicks
Apollo Global Management’s five defining deals, from Executive Life to Intel, built a $1 trillion asset manager spanning insurance and…
S Net Interest Sep 11 1 click