Atlas Engineered Products ($AEP.V) FINS Review
Atlas Engineered Products reported Q2 revenue up 19% to $16.2 million, but ended cashless on its credit line as inventory rose 47% and year-to-date losses widened.
Atlas Engineered Products reported Q2 revenue up 19% to $16.2 million, but ended cashless on its credit line as inventory rose 47% and year-to-date losses widened.
$DAKT CEO departing, new high-quality CFO (temp) w very attractive secular tailwinds in digital display demand + activist involvement = increased likelihood of takeout. Optimal business for PE. Multiple logical strategics. +75% upside.
$FTDR Vol declining (existing home sales=driver). Pricing lagging inflation, massively over-earning. Problematic given 25% churn w aggressive new entrants. Dubious company overall. Investor day yesterday was comical, compared themselves to $NFLX. Earnings misses coming.
$AVO $CVGW 1) Retailers $CMG, etc sourcing elsewhere given MX tariff risk. 2) Avocado price spike during last year’s peak harvest season enabled distributors to realize outsized margins. 1-time benefit has reversed, significant earnings misses ahead for these commodity businesses
$NX Outlandishly guiding to flat 2025 sales, customers and channel -DD. Commodity window and door components facing pricing pressure from larger customers ($JELD, $OC). Now levered 4x, trading at a premium to higher value-add building products peers. Guide cut inevitable.
$J Beat earnings yesterday. Holding back detailed guidance for Investor Day (2/18)—likely raise ’25 #s, 4-year financial targets w significant upside on margins ($ACM and other peers +15% EBITDA margins). Record backlog and multi-year growth runway.
$NX Rapidly declining levered (4x) commodity biz. Q1’25 guide -12% sales, mgmt hoping for 2H’25 recovery. End-mkts deteriorating ($OC -20% Q4 guide, $JELD), customer losses, internal controls issues, integrating a large acq, 0 prior M&A experience. +30x P/E on best case 2025 #s
@StockJabber Thank you. As a read on $PLUS Q3 is tracking in October, $CSCO just reported -23% sales in networking (products account for ~50% of $PLUS revenue) for the Oct quarter-end. Further confirmation that PLUS Q3 is going to be ugly and no turnaround in sight.
Airbnb Experiences faces a supply bottleneck from manual approvals, while a farm host raised her price from $15 to $25 after stronger…
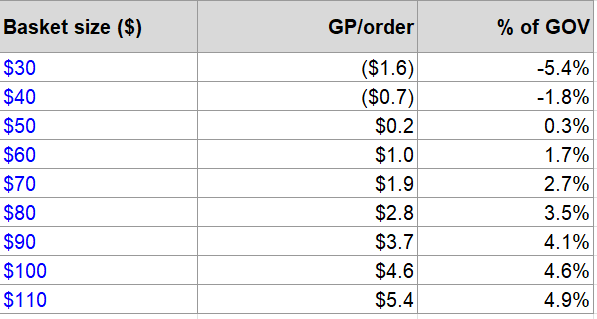
Instacart’s larger grocery baskets create disproportionately better delivery economics than DoorDash’s, making half the basket size worth…

El Al trades near 2x EBITDA after wartime near-monopoly profits, with $1.3 billion of net cash and owned aircraft weighed against…
 BAC 2026-08-20
Bank of America’s BAC.PR.B yields just over 6% near par, while discounted lower-coupon series such as BAC.PR.P offer better value despite…
 Prakhar Agarwal, CFA 1 click
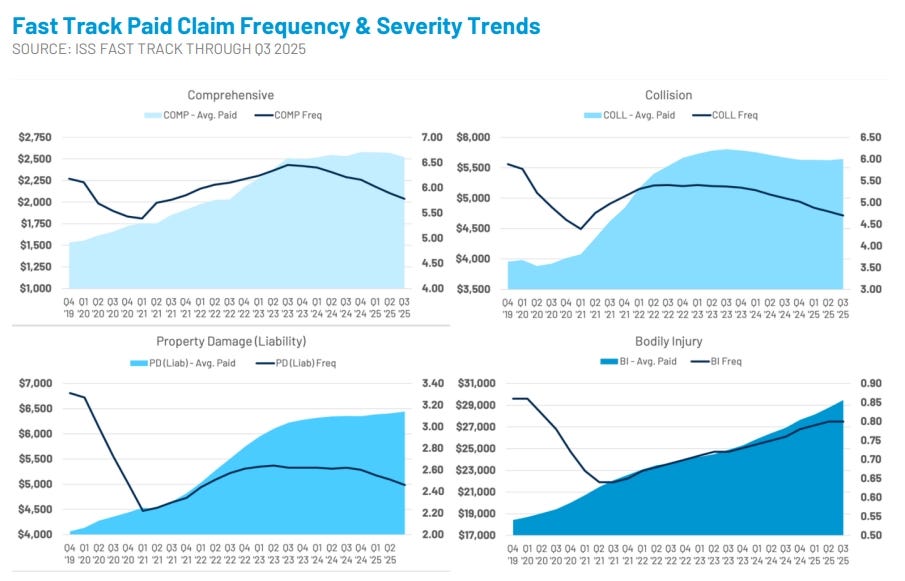
CCC, the dominant auto physical-damage claims estimator, connects 27 of the top 30 insurers with 31,000 repair shops as takeout rumors…
Verra Mobility's new seven-year Avis agreement replaces a customer worth over 10% of revenue on materially worse economics, exposing…
BHP 2026-08-20 BHP expects copper to generate over half of FY2026 EBITDA and plans a 40% production increase by FY2035 after profit, free cash flow and…
 On the Pulse 1 click
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028…
APP 2026-08-19 AppLovin’s AXON 2.0 self-serve rollout, e-commerce onboarding and Connected TV expansion aim to revive growth after Q2 2026 revenue and…
 KL Research 1 click
Jumia’s January 2028 $7/$15 call spread risks $1.15 for up to $6.85 if cost cuts and marketplace growth deliver adjusted EBITDA and…
 ANET · long
Arista Networks, at about $150 per share, is a $190 billion data-center networking franchise generating $9.7 billion of LTM revenue with…
STNE 2026-08-25 StoneCo's buybacks and special dividend produced roughly 39% H1 shareholder yield as Brazil's rate cuts slow and competition persists.
 IWA Research 3 clicks
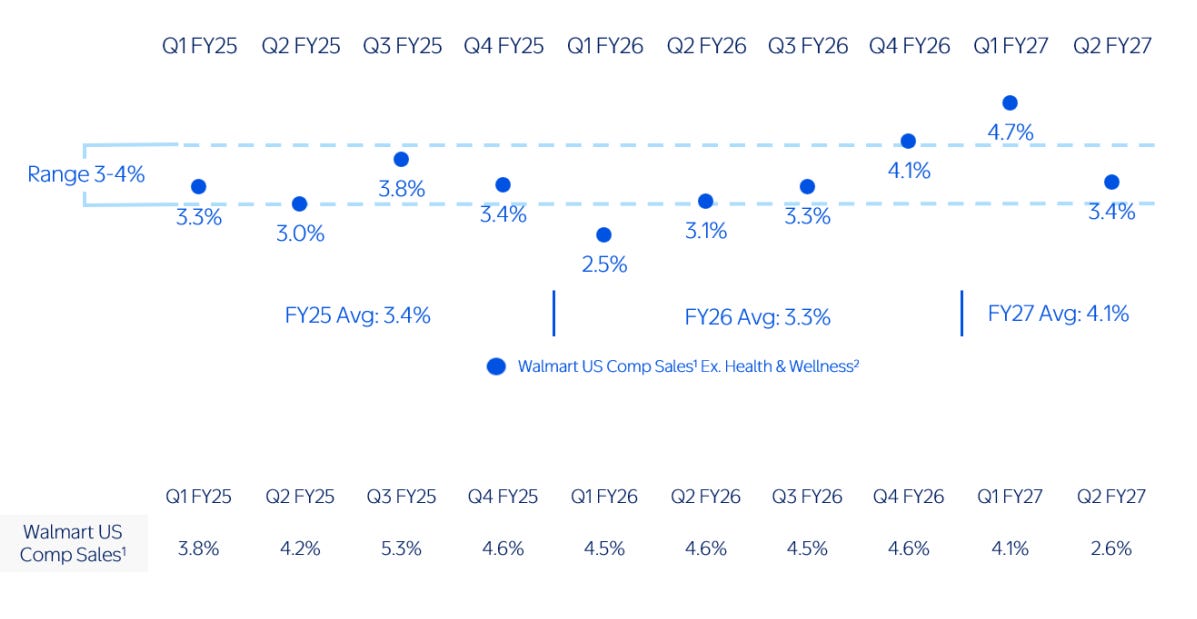
Walmart says Medicare Maximum Fair Price rules will cut FY27 US comps by 125 basis points, while pharmacy margins and prescription volumes…
VISN 2026-08-21 Vistance Networks trades at $11 after a $5 special distribution, with a DOCSIS 4.0 upgrade cycle, cash reserves and a $160 million tax…
 Investor Overview 1 click
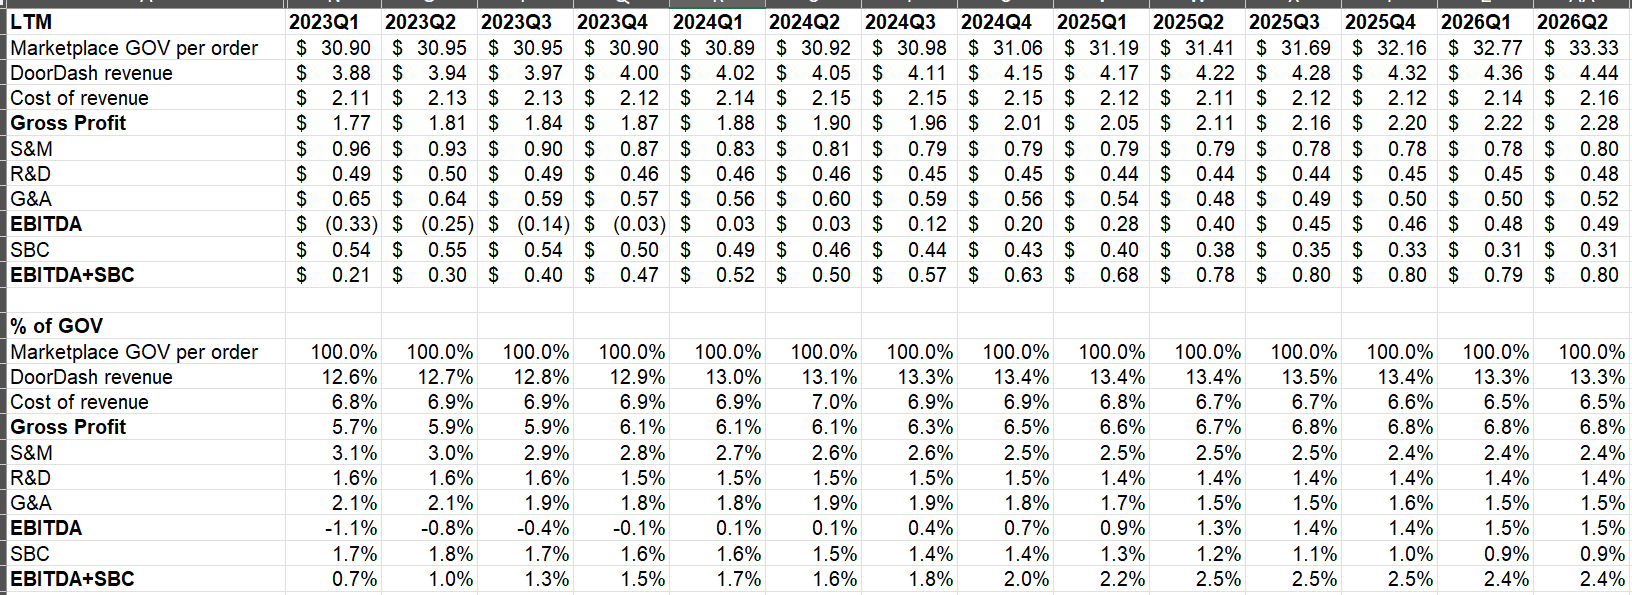
Instacart’s per-order unit economics provide a benchmark for assessing DoorDash’s LTM profitability and operating model.
NBIS 2026-08-20 Nebius posted 454% revenue growth and a 41% EBITDA margin, while Meta’s $27 billion agreement supports its AI infrastructure backlog.
 The Quality Growth Investor 1 click
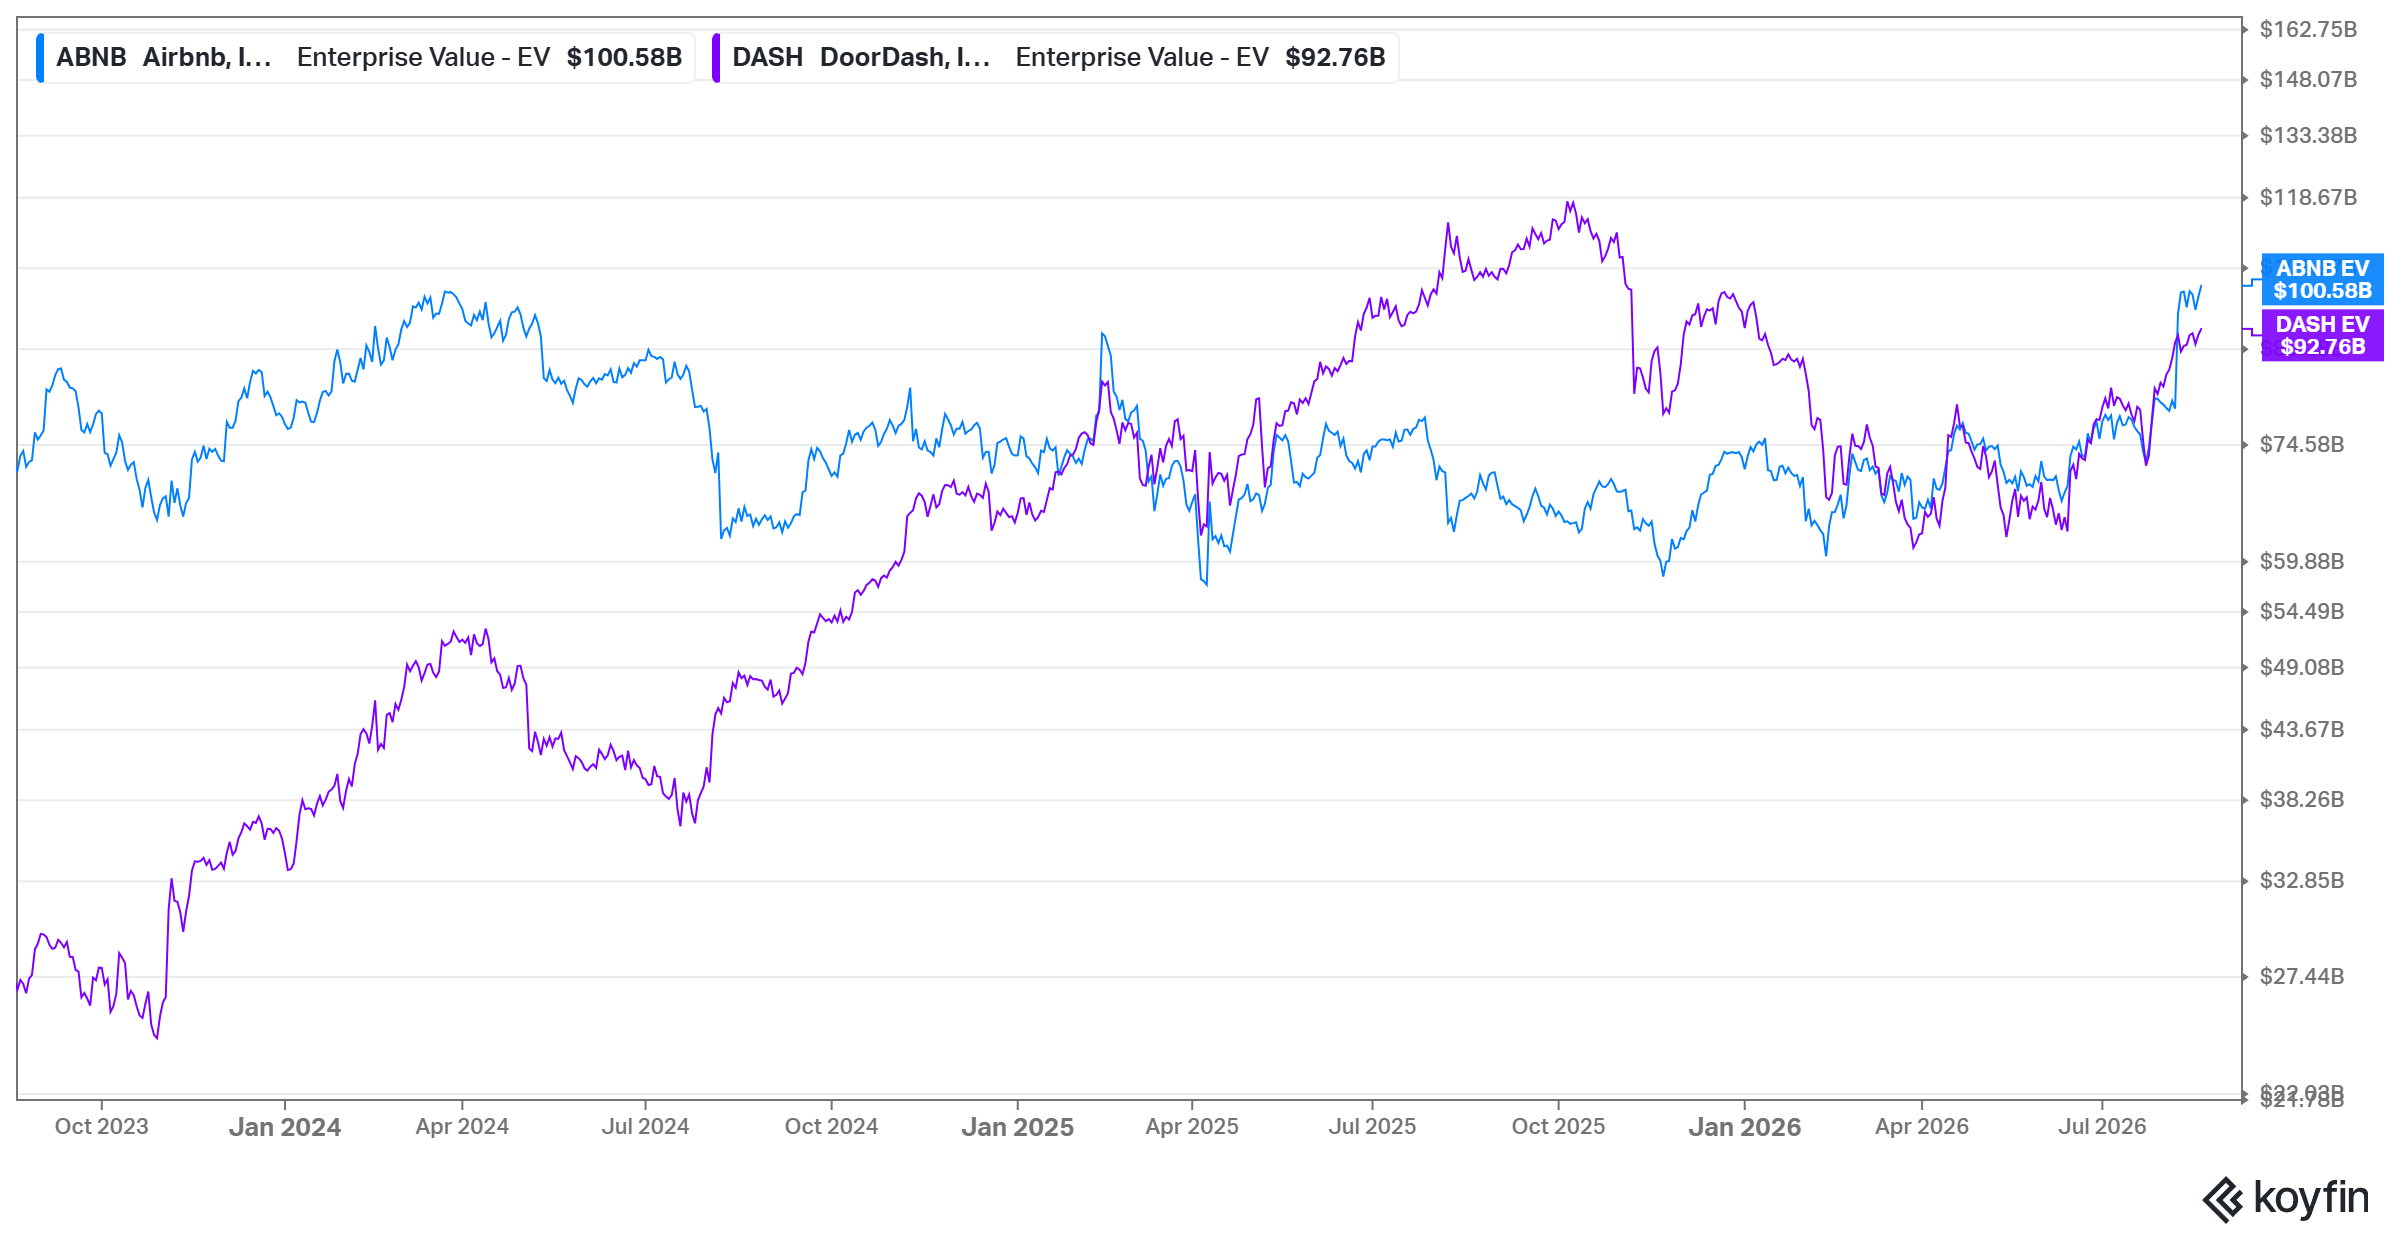
Airbnb shares have risen about 50% since October 2025, prompting a revised 2026 model and return assumptions at the current price.

IREN awarded each co-CEO roughly 9 million RSUs, about 2.5% of shares and $400 million, in exchange for no further equity grants until…

Nubank's 140 million customers, 20% efficiency ratio and 30% ROE frame whether its high-teens P/E reflects a scalable fintech or a maturing…
E.W. Scripps, Team Internet, Monro, doValue and Inter & Co feature as special-situation trades involving mergers, asset sales, leverage and…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor Investor Overview IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.