The Non-linear Economics of Grocery Delivery Basket
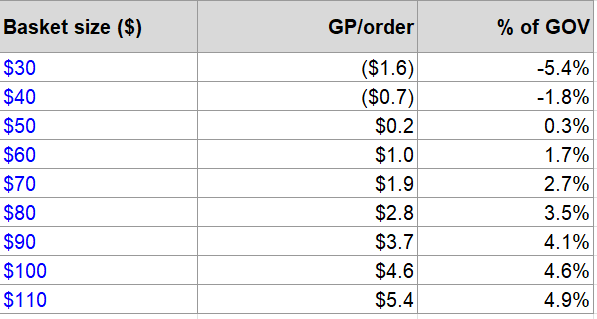
Instacart’s larger grocery baskets create disproportionately better delivery economics than DoorDash’s, making half the basket size worth far less than half the profit.
Instacart’s larger grocery baskets create disproportionately better delivery economics than DoorDash’s, making half the basket size worth far less than half the profit.
@Ross__Hendricks @DratchCap @WarrenPies Equity is abundant even while absolute debt issuance skyrockets. I would think prudent capital allocators would tap the former… (see $GOOG, $ORCL as of late)
@davey_juice @taobanker I own both. $NU seems inevitable. $INTR more execution and single-market risk but a lot more upside if it works and gets rerated.
@taobanker $INTR at 1.2x book 5.5x '27 earnings with a 16% ROE growing at 20% a year probably qualifies. But yes, $BLX is incredible and I still kick myself for selling most of my position at $25 after buying at $15. Grabbed defeat from the jaws of victory there.
@BoxLongs Wild truth is that if $SNAP chooses they can earn over $1/share in FCF next year. $5 stock.
Bought $TTWO after seeing the GTA VI leaked footage. Forget the graphics. Unpolished gameplay is showing a massive leap in world density, NPC behavior and systemic depth. The world feels alive. First real evidence GTA VI may actually be a generational leap. That’s the signal. https://t.co/r6HKMVSYgc
@taobanker $U up every day, $APP down every day, $RBLX demolished. Things as they should be.
@2suns2moons @bold_perception $CIB dividend up from $2.25/year in 2022 to more than $6/share now. Covers a lot of living expenses. If you relocate to another country, good to own some stuff there so you have an economic stake if its conditions improve...
Deutsche Bank $DB freed from consent order in 2010s FX scandal https://t.co/BsHGBheaWK
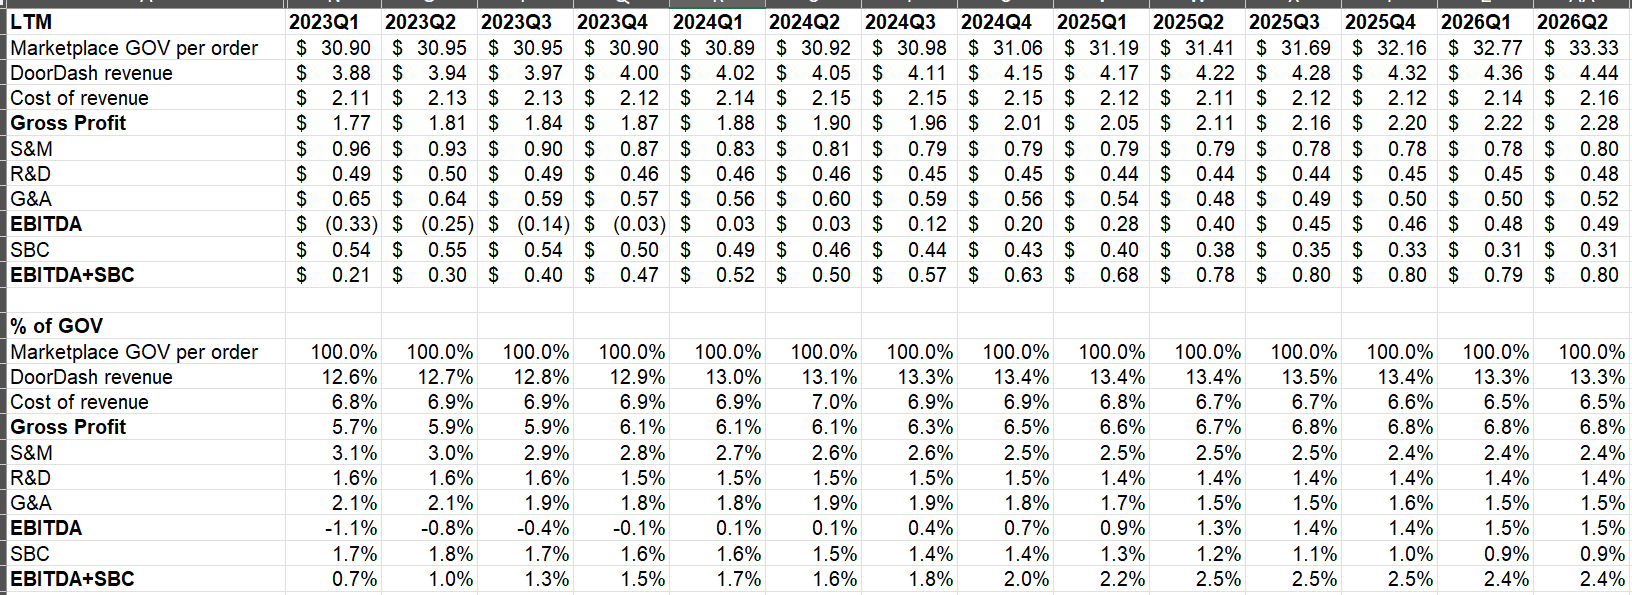
Instacart’s per-order unit economics provide a benchmark for assessing DoorDash’s LTM profitability and operating model.
 NBIS 2026-08-20
Nebius posted 454% revenue growth and a 41% EBITDA margin, while Meta’s $27 billion agreement supports its AI infrastructure backlog.
 The Quality Growth Investor 1 click
CCC, the dominant auto physical-damage claims estimator, connects 27 of the top 30 insurers with 31,000 repair shops as takeout rumors…
TEM 2026-08-20 Tempus AI's diagnostics and data businesses grew Q2 2026 revenue 19.4% year over year, with FDA approvals, expanded tests and pricing aimed…
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028…
APP 2026-08-19 AppLovin’s AXON 2.0 self-serve rollout, e-commerce onboarding and Connected TV expansion aim to revive growth after Q2 2026 revenue and…
 KL Research 1 click

IREN awarded each co-CEO roughly 9 million RSUs, about 2.5% of shares and $400 million, in exchange for no further equity grants until…

Nubank's 140 million customers, 20% efficiency ratio and 30% ROE frame whether its high-teens P/E reflects a scalable fintech or a maturing…
HubSpot trades near its 2020 share price despite quadrupled revenue and $750 million in free cash flow, with Breeze AI upside weighed…

DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
 WK · long
Workiva, an enterprise software platform, trades at a reasonable valuation as it approaches its first profitable period since its 2008…

ResMed’s 30 million connected sleep-apnea patients, recurring masks and software support a data-driven healthcare platform; 11.9% annual…
Nike is excluded from Bearhold’s universe because cultural relevance and consumer taste drive demand, leaving its revenue model less…
Copart’s salvage-auction network pairs scarce storage land with global online bidding, supporting insurer returns and a durable moat…
Shift4 built its payments business by acquiring gateway nodes and migrating merchants to its processing platform; revenue has compounded…

Vaca Muerta’s $36–45-per-barrel breakevens, Milei reforms and $17 billion infrastructure buildout underpin the bullish case for Vista…

Airbnb’s fourth-quarter revenue rose 12% to $2.8 billion and GBV 16%, while product improvements and AI spending target booking conversion…
Adobe trades at 14x free cash flow after a 60% decline despite growth, with AI, its business-model transition and creative-software…

Adobe’s sub-20x forward GAAP P/E reflects AI disruption fears, with the investment case hinging on whether Digital Media’s creative…

A former value-investor darling, down 50%, pairs a monopoly with a recurring-revenue razor-and-blade business; debt paydown, margin…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.