NCLH or her grandma Saga?
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028 profit.
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028 profit.
@DueDoctor Oh I agree 100%. The move is totally insane. $GME like. +20% would have made some sense based on math. I actually think lack of 2ndary here is even WORSE for them. They need the cash. 2ndary cleans up that need.
@DueDoctor All goes well this could add $800mn in annual revenue to $mrna. Added $44B in market cap. Market said that theoretical 2-3 year out revenue is worth 50x + yesterdays' market cap
@BoxLongs $SNAP added $250mn in revenue yy and $200mn in adj ebitda. Adj shares outstanding actually decreased 70 bps yy. FCF +400% yy. While everyone knows its a horribly managed asset, the numbers in isolation are MUCH improved YoY while stock itself is down 30% yy.
@SandBrandyn I bought a basket of software and adjacent in Feb/March. $TEAM most ridiculous example both to the down and now upside... I don't trust the management teams enough to make a concentrated bet on any of these.
Atlassian $TEAM now up 214% since April, and +5% YTD. Market very efficiently determining future discounted cash flows from software companies, I see.
@LocalHero55 @OtterMarket @gatorcapital Post on an even more obscure MHC bank. And yes, $TFSL is a great income instrument, with (eventually) a chunky cap gain exit when they finally convert.
@OtterMarket @gatorcapital $tfsl is just under a billion when you exclude the phantom shares. I've owned it a long time and very few people care about it either. That said, this NY one is even more obscure
@stoked_on_waves @CapitalShipyard $open's backers also claim it is profitable. Apparently you can just say stuff now

Nubank's 140 million customers, 20% efficiency ratio and 30% ROE frame whether its high-teens P/E reflects a scalable fintech or a maturing…
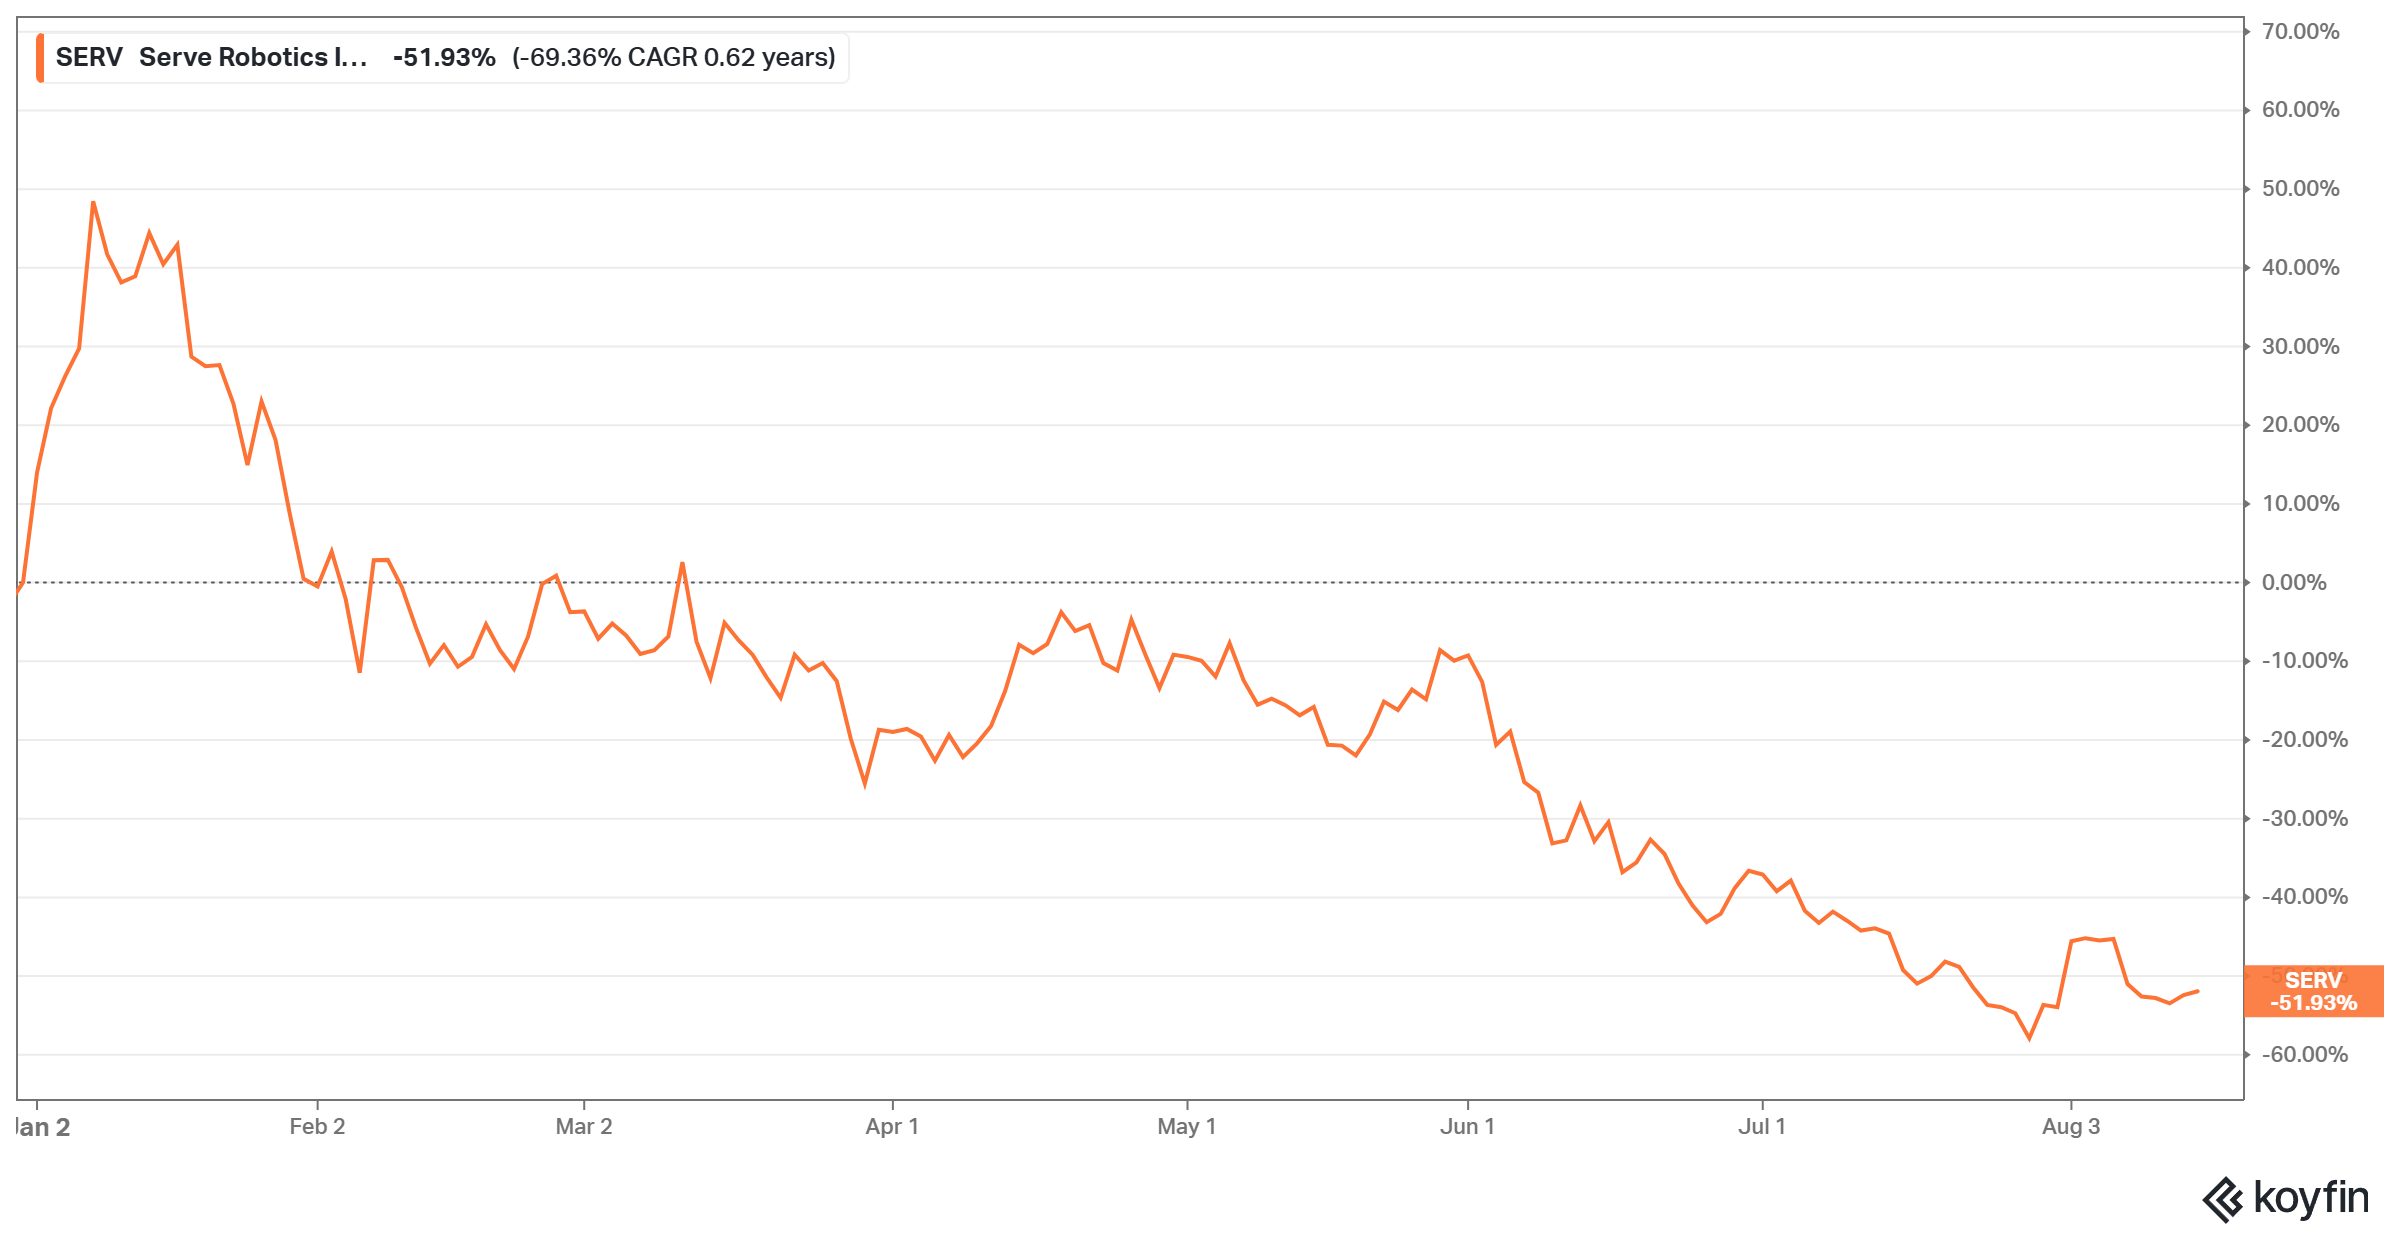
DoorDash’s integrated autonomous-delivery strategy contrasts with Uber’s 2026 divestment of Serve Robotics, its former delivery-robot…

Hyperscalers’ off-balance-sheet lease and purchase obligations rose from roughly $1 trillion to $1.5 trillion, turning the AI buildout into…
HubSpot trades near its 2020 share price despite quadrupled revenue and $750 million in free cash flow, with Breeze AI upside weighed…

Steve Eisman argues the AI boom hinges on Anthropic and OpenAI’s importance to hyperscalers, while weighing software, CoreWeave and Cisco…

DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.

CoreWeave and Nebius cite AI compute shortages and higher-priced GPU renewals, but older-chip utilization and depreciation vary across…
Macy’s and Kohl’s face renewed short cases as their recent reratings ignore fading store-refresh gains, credit-card earnings exposure and…
Zoetis’s U.S. companion-animal revenue fell 6% as dermatology competition drove rebates and discounts, pushing full-year net pricing to…
Copart faces a near-term lift from pricier AV repairs and total losses, but shrinking accident volumes could eventually force its…
 OTIS · long
Otis Worldwide's largest global elevator installed base generates 95% recurring revenue, with service margins above 90% supporting a…

ResMed’s 30 million connected sleep-apnea patients, recurring masks and software support a data-driven healthcare platform; 11.9% annual…
Nike is excluded from Bearhold’s universe because cultural relevance and consumer taste drive demand, leaving its revenue model less…
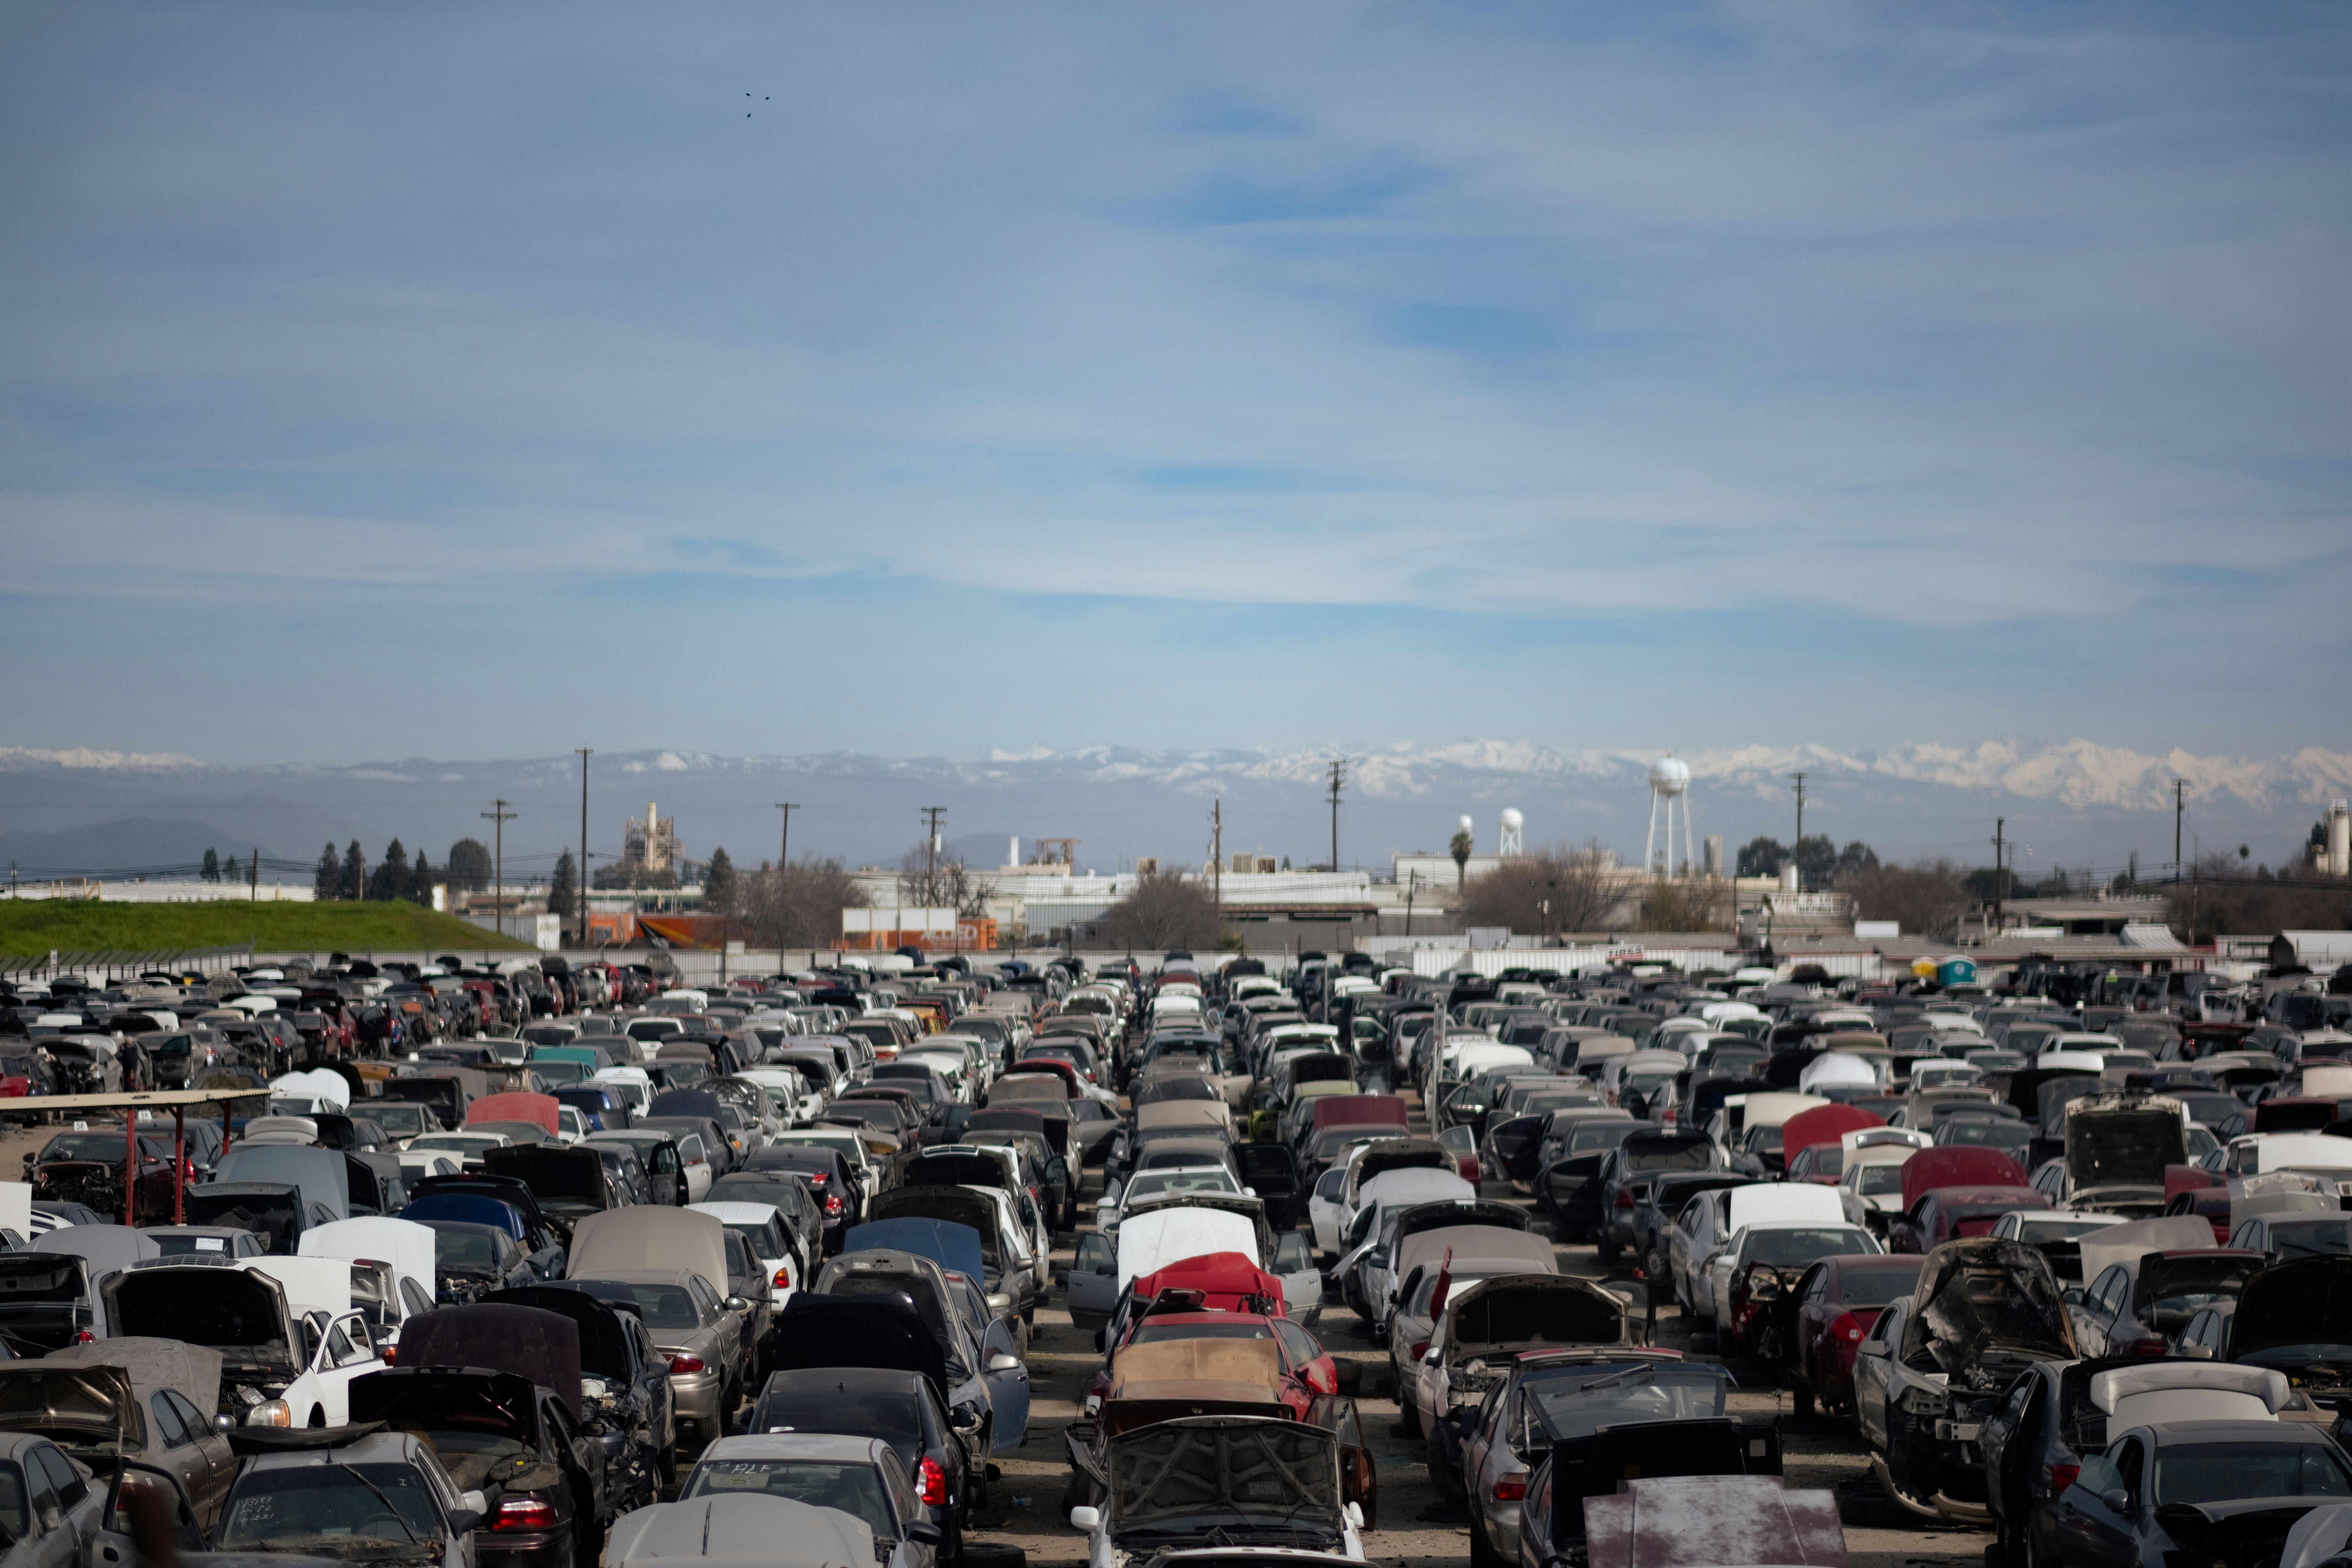
Copart’s salvage-auction network pairs scarce storage land with global online bidding, supporting insurer returns and a durable moat…
Shift4 built its payments business by acquiring gateway nodes and migrating merchants to its processing platform; revenue has compounded…
Vaca Muerta’s $36–45-per-barrel breakevens, Milei reforms and $17 billion infrastructure buildout underpin the bullish case for Vista…

Airbnb’s fourth-quarter revenue rose 12% to $2.8 billion and GBV 16%, while product improvements and AI spending target booking conversion…
Adobe trades at 14x free cash flow after a 60% decline despite growth, with AI, its business-model transition and creative-software…

Adobe’s sub-20x forward GAAP P/E reflects AI disruption fears, with the investment case hinging on whether Digital Media’s creative…

A former value-investor darling, down 50%, pairs a monopoly with a recurring-revenue razor-and-blade business; debt paydown, margin…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.