NCLH or her grandma Saga?
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028 profit.
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028 profit.
I just published my Earnings Update about the Q1 2026 of Evolution $EVO $EVVTY. You can find it in the Portfolio section of the blog :) https://t.co/QXlBS93lji
@CalgaryLeveen @cfrischer1 @sScCrRaAbBLLeE 4/x) i'd bet RFID would drop their objections to $NN's plan in exchange for licensed status in 907-918 (or 908-917Mhz). Seems like a fair compromise to provide terrestrial backup to GPS in the U.S. for free.
@CalgaryLeveen @cfrischer1 @sScCrRaAbBLLeE 2/x) remember $NN does not want 907-918 MHz. RFID signal is strongest at 915. Europe and China both use ~9 MHz for RFID, with restrictions on power and listen before talk. Why is 11 MHz that includes 915 (9 w/ blockers) not enough for RFID in the US? https://t.co/U9xEpNXW22
@CalgaryLeveen @cfrischer1 @sScCrRaAbBLLeE 1/x) agree- same objectors in different clothing. We need real world tests to prove/disprove interference - $NN has been calling for those tests for 2 years b/c they know the answer. An NPRM can force testing. The real question though is why does RFID need 902-928 MHz?
Evolution $EVO Q1 '26 results: ▫️Revenues -1.5% *Live Casino -3.2% *RNG +8.2% ▫️EBITDA -1.9% ▫️EBITDA margin of 65.4% (vs. 65.6%) ▫️Profit -1.1% ▫️EPS +2.1% ▫️OCF -4.3% ▫️Europe decline continues die to regulation, while other regions show good progress https://t.co/0HkW1HexzA
Cedar Creek Partners Q1 letter released. Fund was up 6.8% in Q1, net of fees and expenses. $SODI $ENDI $EXCE $PHIF $HRBR $STLE $SLBK $RVRF https://t.co/d794sYsHAT

IREN awarded each co-CEO roughly 9 million RSUs, about 2.5% of shares and $400 million, in exchange for no further equity grants until…

Nubank's 140 million customers, 20% efficiency ratio and 30% ROE frame whether its high-teens P/E reflects a scalable fintech or a maturing…
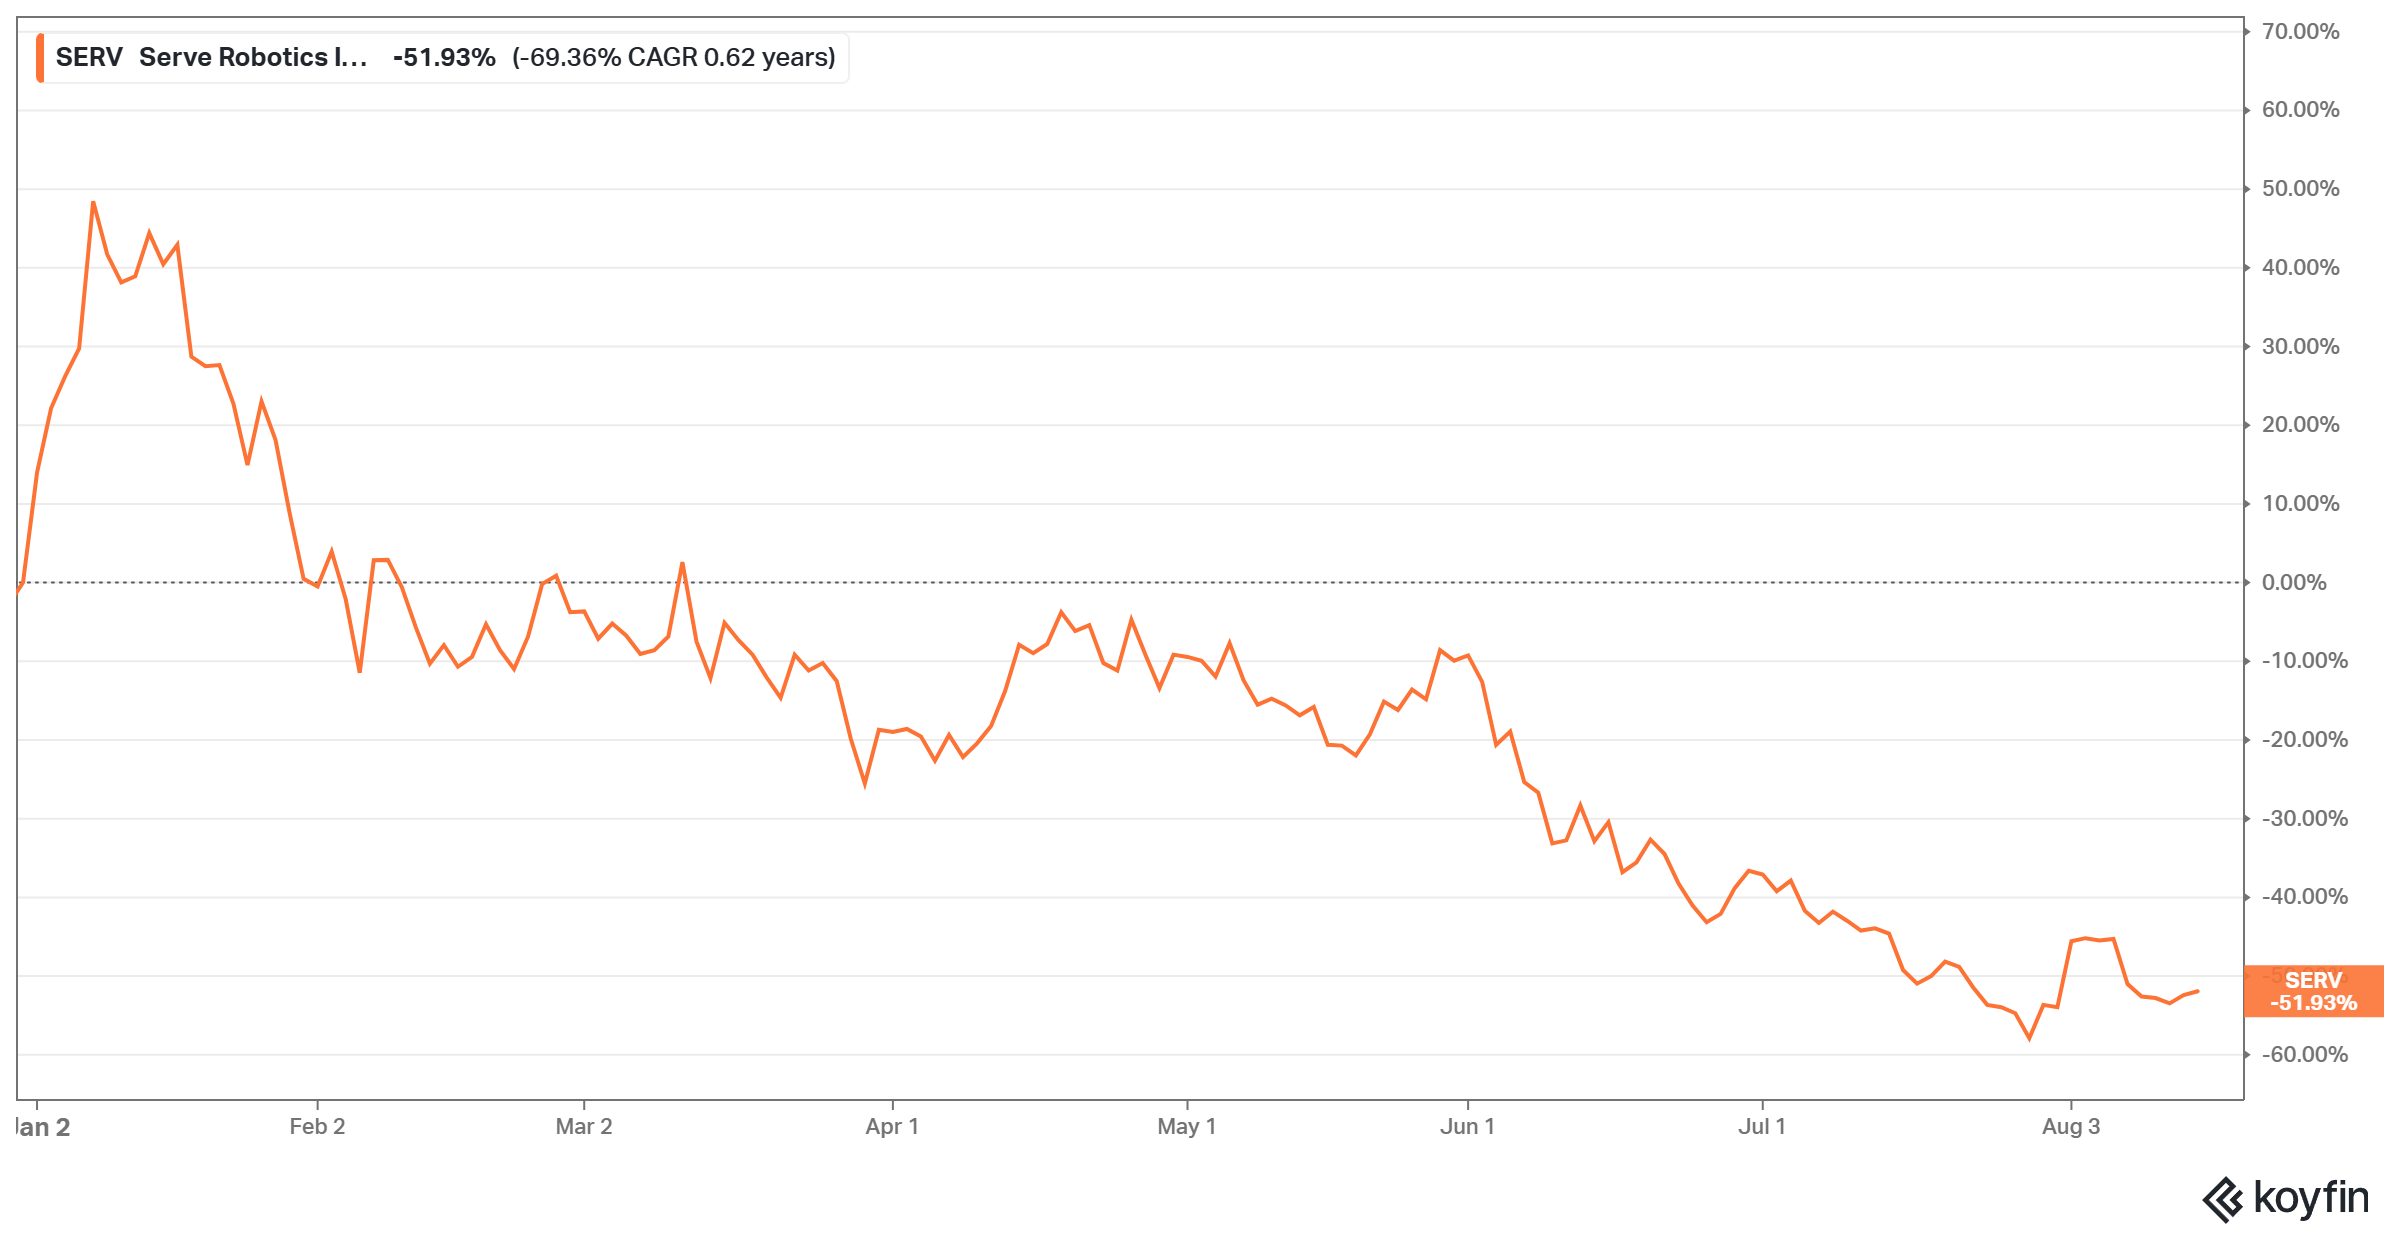
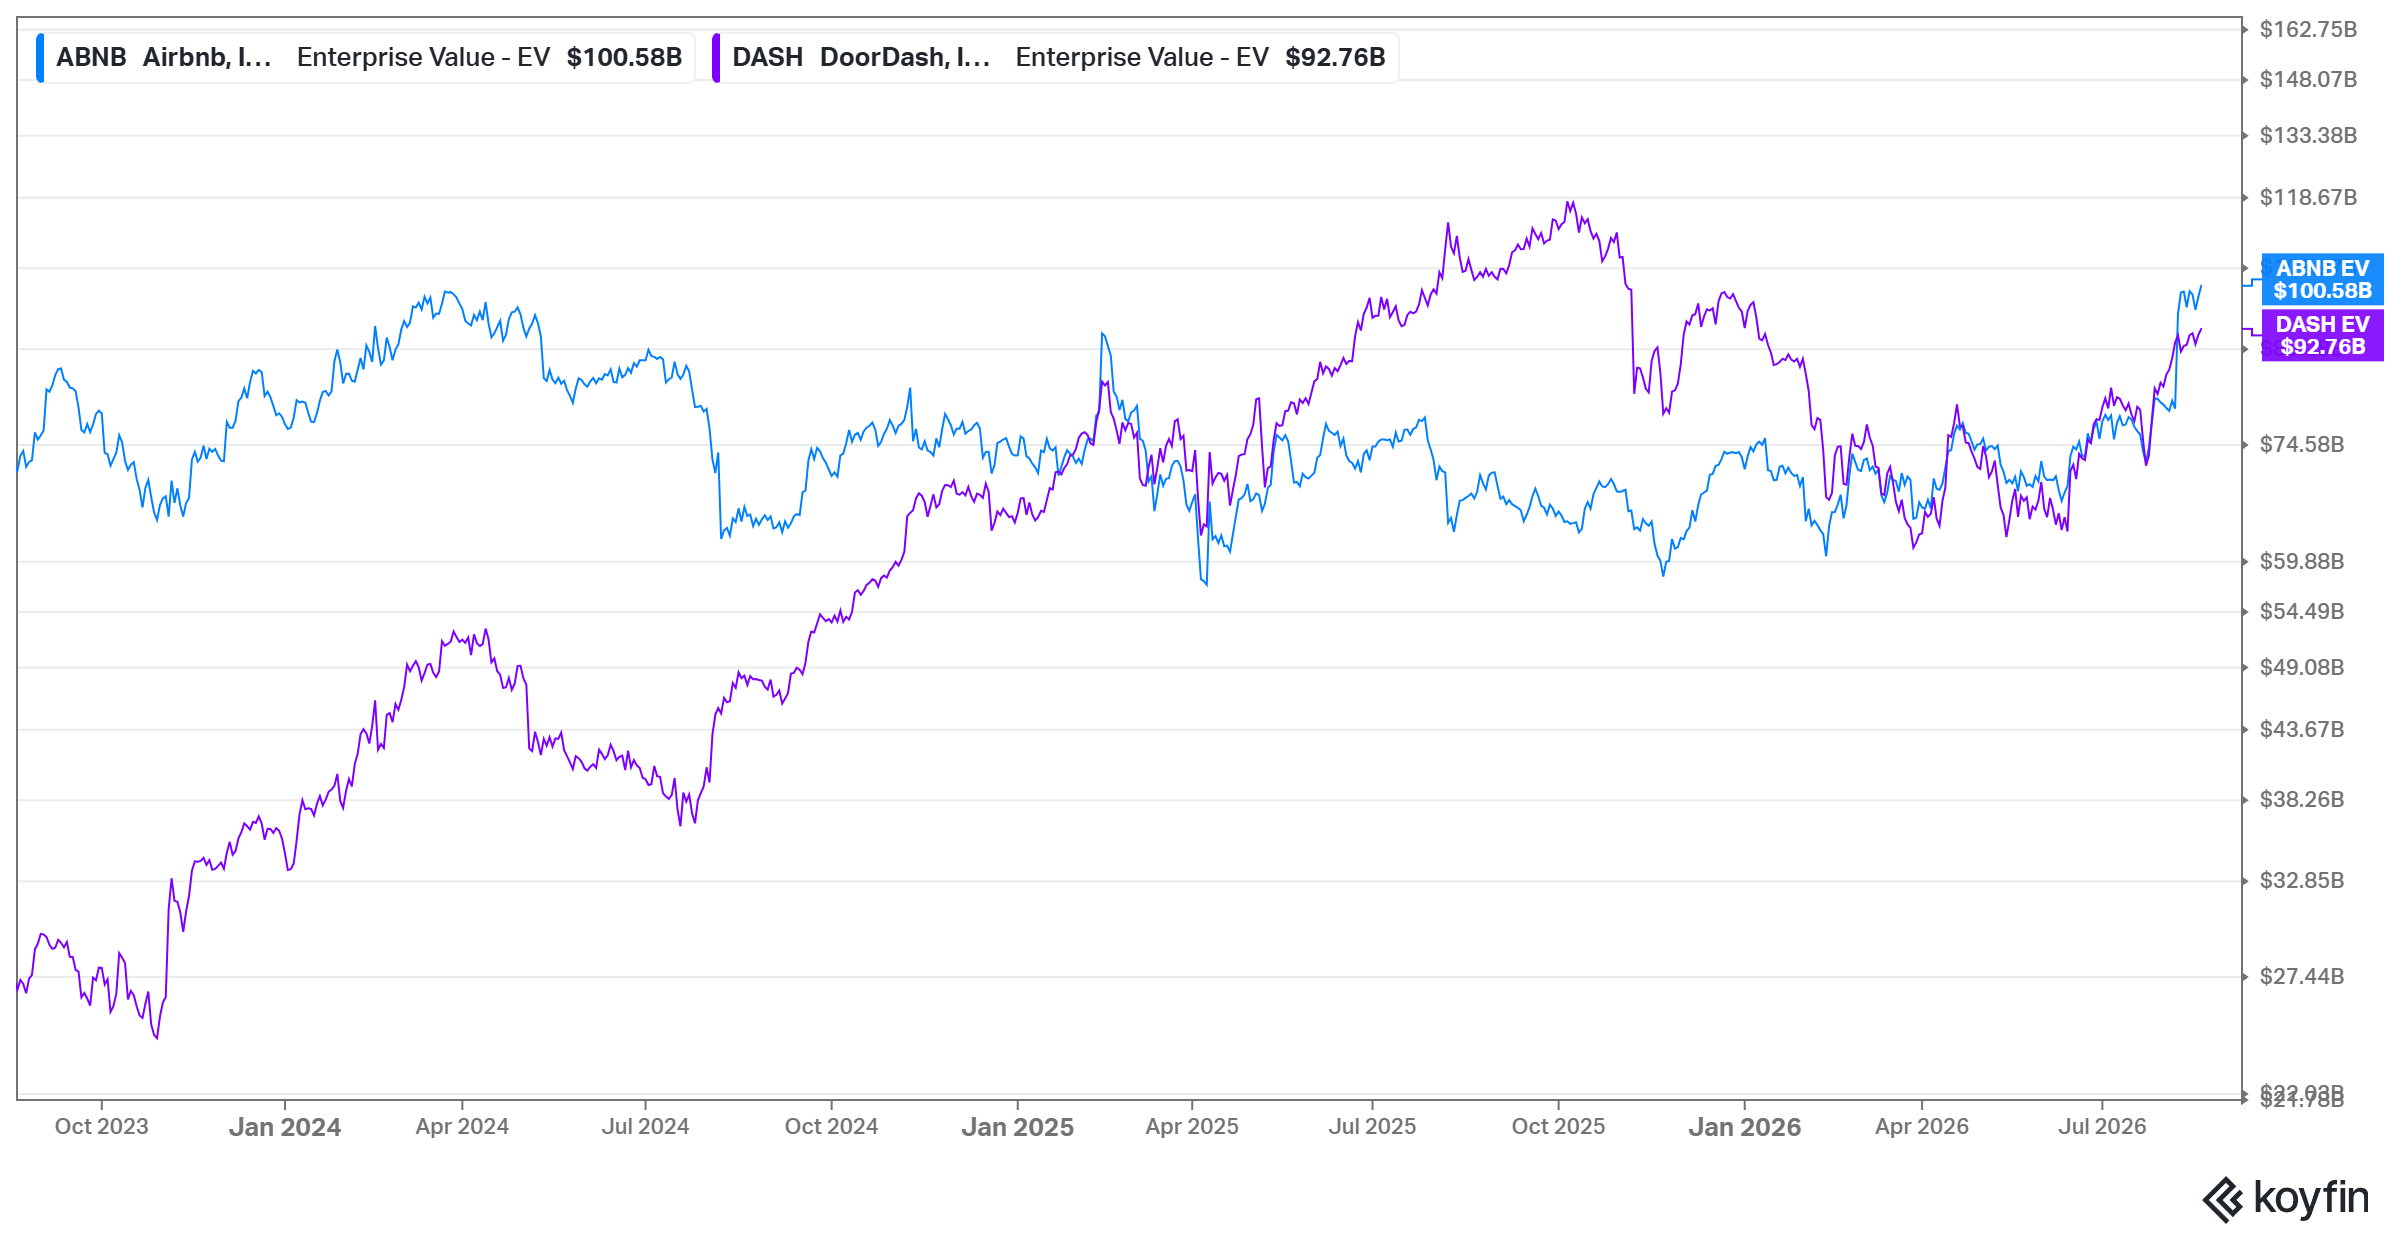
DoorDash’s integrated autonomous-delivery strategy contrasts with Uber’s 2026 divestment of Serve Robotics, its former delivery-robot…
E.W. Scripps, Team Internet, Monro, doValue and Inter & Co feature as special-situation trades involving mergers, asset sales, leverage and…
HubSpot trades near its 2020 share price despite quadrupled revenue and $750 million in free cash flow, with Breeze AI upside weighed…

DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.

CoreWeave and Nebius cite AI compute shortages and higher-priced GPU renewals, but older-chip utilization and depreciation vary across…
Macy’s and Kohl’s face renewed short cases as their recent reratings ignore fading store-refresh gains, credit-card earnings exposure and…
Zoetis’s U.S. companion-animal revenue fell 6% as dermatology competition drove rebates and discounts, pushing full-year net pricing to…
Copart faces a near-term lift from pricier AV repairs and total losses, but shrinking accident volumes could eventually force its…
 ADBE · long
Adobe's dual network effects and platform entrenchment make AI fears a buying opportunity for the software compounder.

GFL’s proposed acquisition of Secure follows 19% revenue growth at Secure and 14.8% EBITDA growth at GFL, with Permian produced-water and…
Entravision’s ATS revenue rose 230% to $182.8 million in Q2, but shares fell from above $14 to about $8 after management forecast…
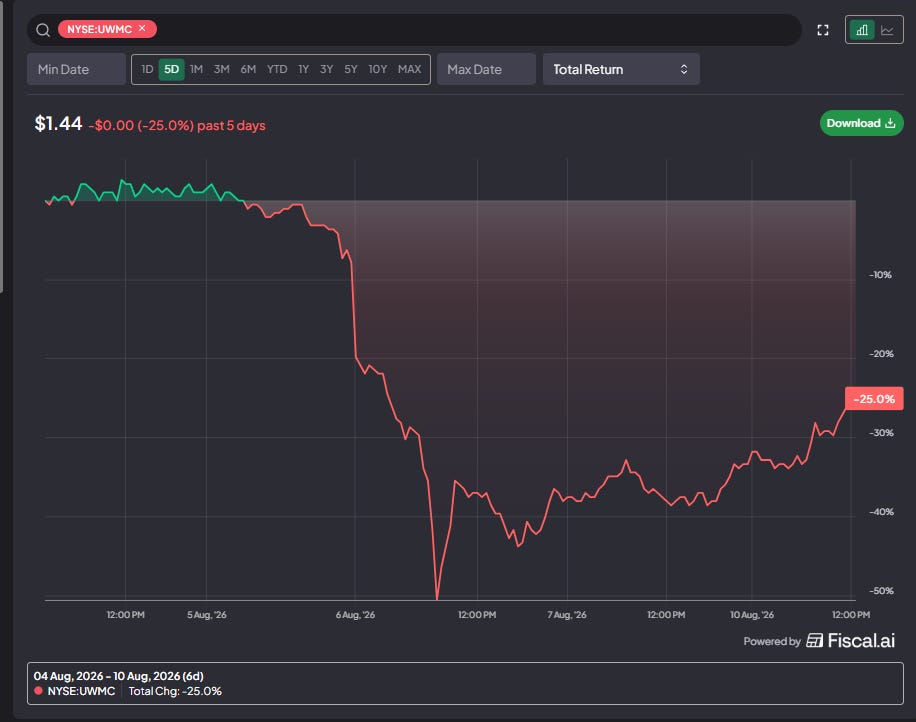
UWMC booked a roughly $600 million Q2 hedging loss tied to TWO months after the deal collapsed, contributing to an expensive capital raise.

Glenn Schorr and Ken Worthington discuss risks in private-credit software loans, agentic AI at retail brokers, crypto use cases and bank…
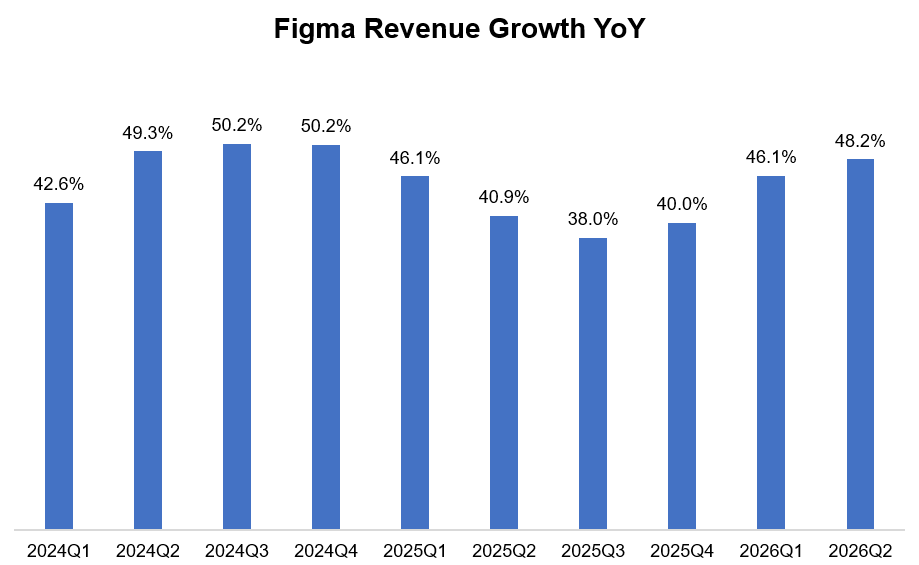
Figma raised its 2026 revenue growth guide to 39%, but a roughly 1% sequential 3Q outlook and unchanged $125-135 million operating-income…
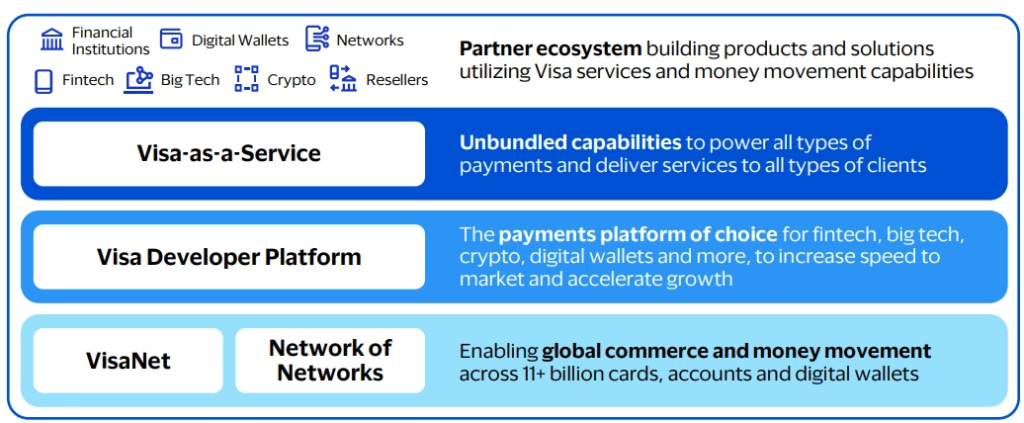
Visa and Mastercard have absorbed digital wallets and BNPL into their networks, using global merchant acceptance to turn supposed…

Navient trades near 40% of tangible book as Gator Financial Partners argues private student-loan growth and restructuring can reverse its…
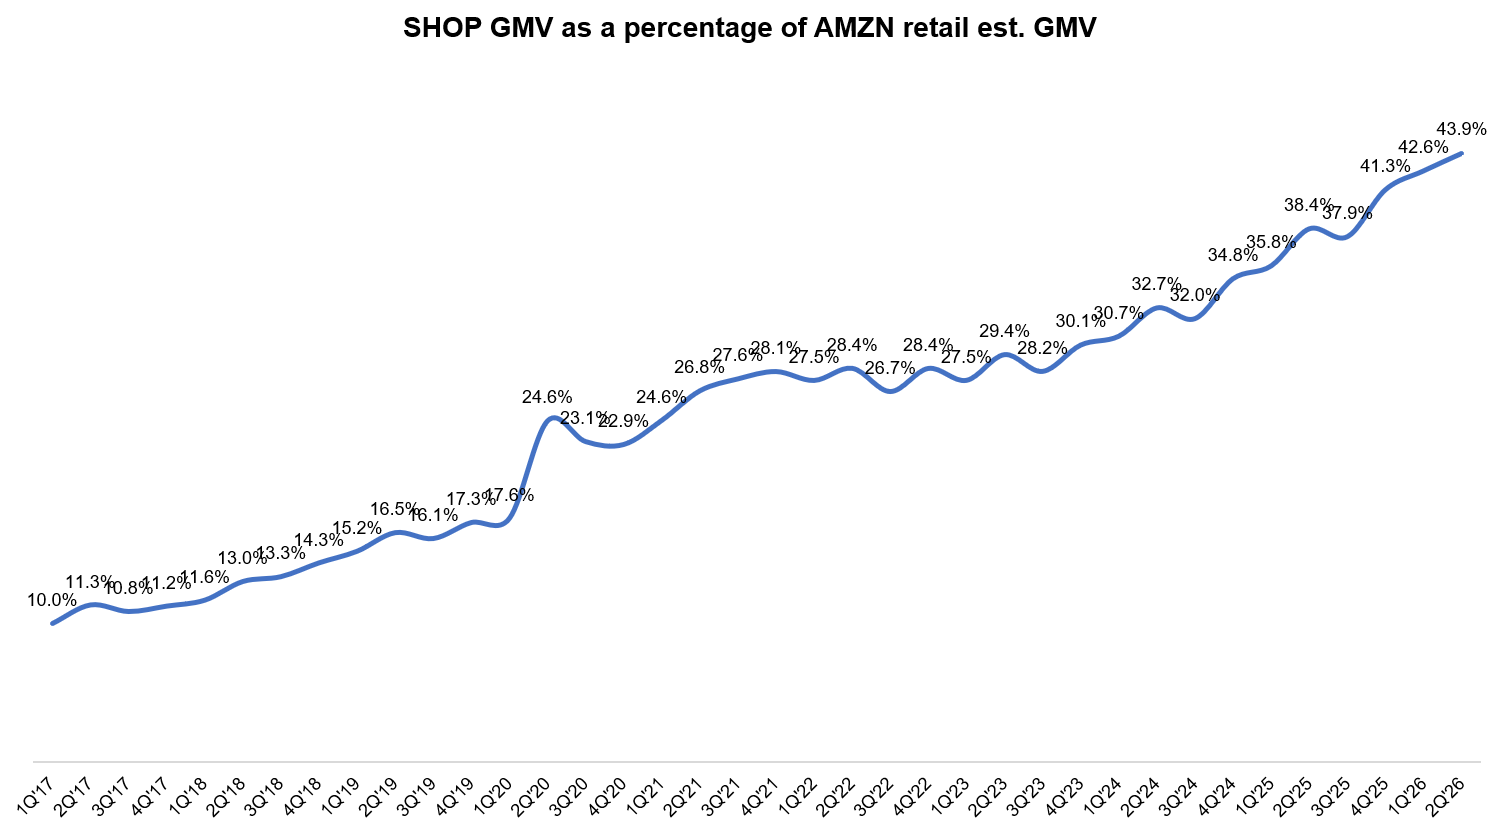
Shopify sustained 30% FX-neutral GMV growth in 2Q’26, reaching roughly 44% of Amazon’s retail GMV as international, POS and B2B volumes…

Steve Eisman reviews SpaceX earnings, AI capital spending’s drag on free cash flow, Meta’s struggles, and the collapse of Situational…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.