$NU: is Nubank Capital One in 1994 or Capital One in 2006? | Vanshap Capital
Nubank's 140 million customers, 20% efficiency ratio and 30% ROE frame whether its high-teens P/E reflects a scalable fintech or a maturing Brazilian lender.
Nubank's 140 million customers, 20% efficiency ratio and 30% ROE frame whether its high-teens P/E reflects a scalable fintech or a maturing Brazilian lender.
@BillAckman Literally every asset that’s managed by you including $HHH $PSHZF and now $PSUS has always traded at a discount. Why would this one be any different?
What’s the $BR mega bear case?
$HPE let's fucking go. https://t.co/OjNXeIX0yM
@Minnvestor $NVT you'd think would be up more today. Also w/ TPUs and Project Deschutes what w/ Anthropic S-1 and rev growth. Do you think just overlooked?
Is there a specific reason for recent weakness in names like $LITE? Everything I see out recently e.g. the Rosenblatt note seems strongly bullish. Maybe just momentum capital flowing elsewhere? (Which would make this dip attractive potentially)
@scottwilsonUSD @cfrischer1 Womack is seemingly in $WMT's pocket & claiming $NN will interfere with RFID. However, $NN has the proof that they do not interfere with RFID, so presumably Womack will go away.
@finphysnerd $cme and $otcm are in this category and are reasonable
HubSpot trades near its 2020 share price despite quadrupled revenue and $750 million in free cash flow, with Breeze AI upside weighed…

Steve Eisman argues the AI boom hinges on Anthropic and OpenAI’s importance to hyperscalers, while weighing software, CoreWeave and Cisco…

CoreWeave and Nebius cite AI compute shortages and higher-priced GPU renewals, but older-chip utilization and depreciation vary across…
Options strategies will manage portfolio risk after Meta, Alphabet and Amazon calls drove gains, while Lululemon LEAPs produced an 80% loss.
Zoetis’s U.S. companion-animal revenue fell 6% as dermatology competition drove rebates and discounts, pushing full-year net pricing to…
Copart faces a near-term lift from pricier AV repairs and total losses, but shrinking accident volumes could eventually force its…

GFL’s proposed acquisition of Secure follows 19% revenue growth at Secure and 14.8% EBITDA growth at GFL, with Permian produced-water and…

Glenn Schorr and Ken Worthington discuss risks in private-credit software loans, agentic AI at retail brokers, crypto use cases and bank…
Alphabet's Google Cloud swung from a $3.1 billion operating loss in 2021 to $13.9 billion profit in 2025 as Search revenue grew 13.2%.
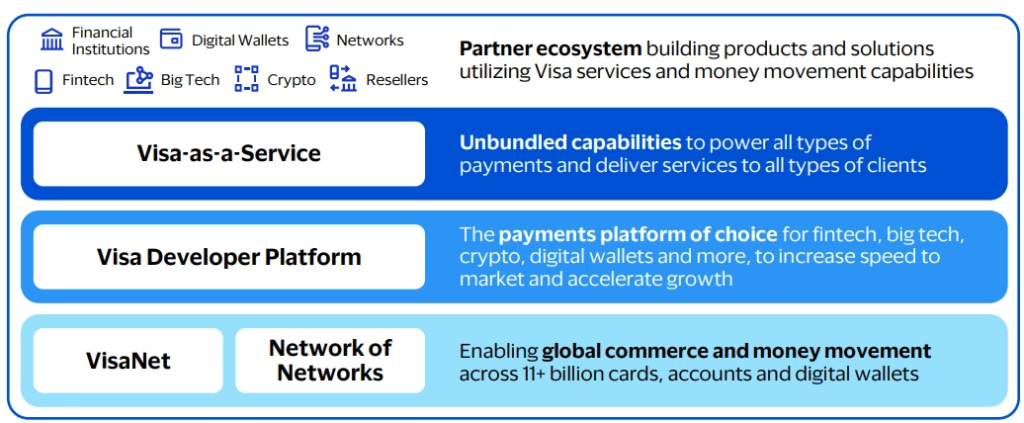
Visa and Mastercard have absorbed digital wallets and BNPL into their networks, using global merchant acceptance to turn supposed…
 CHRW · long
C.H. Robinson faces new liability exposure after the Supreme Court unanimously allowed state negligent-hiring claims under the FAAAA.
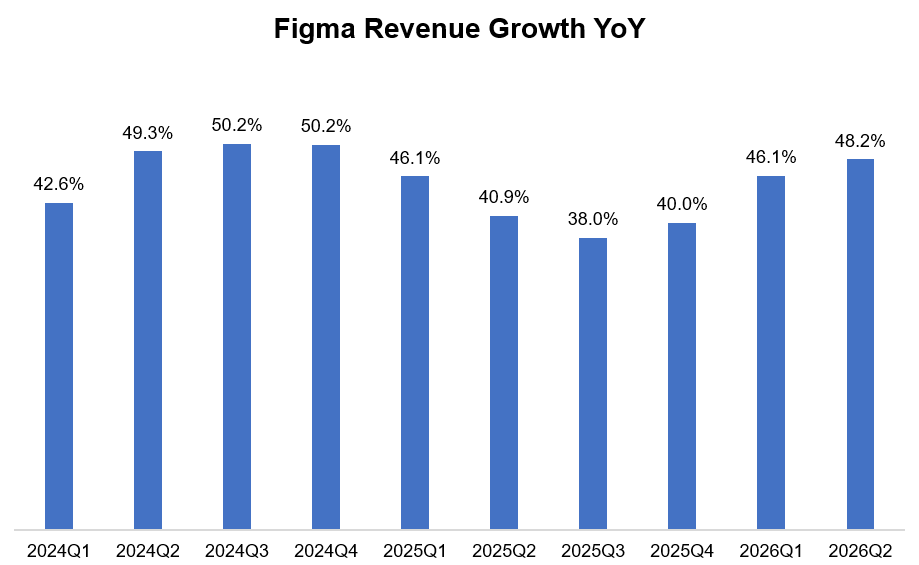
Figma raised its 2026 revenue growth guide to 39%, but a roughly 1% sequential 3Q outlook and unchanged $125-135 million operating-income…
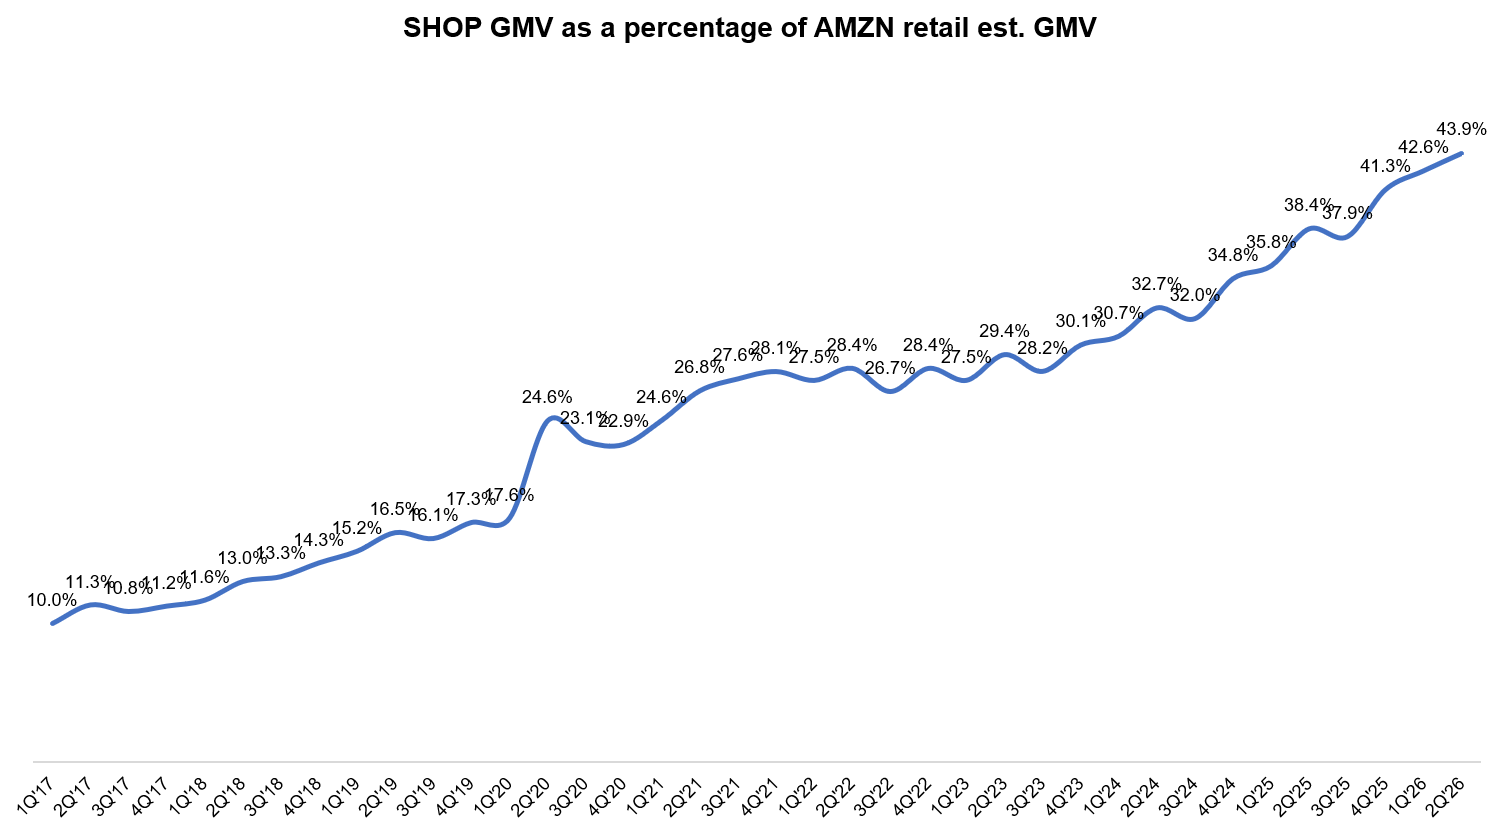
Shopify sustained 30% FX-neutral GMV growth in 2Q’26, reaching roughly 44% of Amazon’s retail GMV as international, POS and B2B volumes…

Steve Eisman reviews SpaceX earnings, AI capital spending’s drag on free cash flow, Meta’s struggles, and the collapse of Situational…
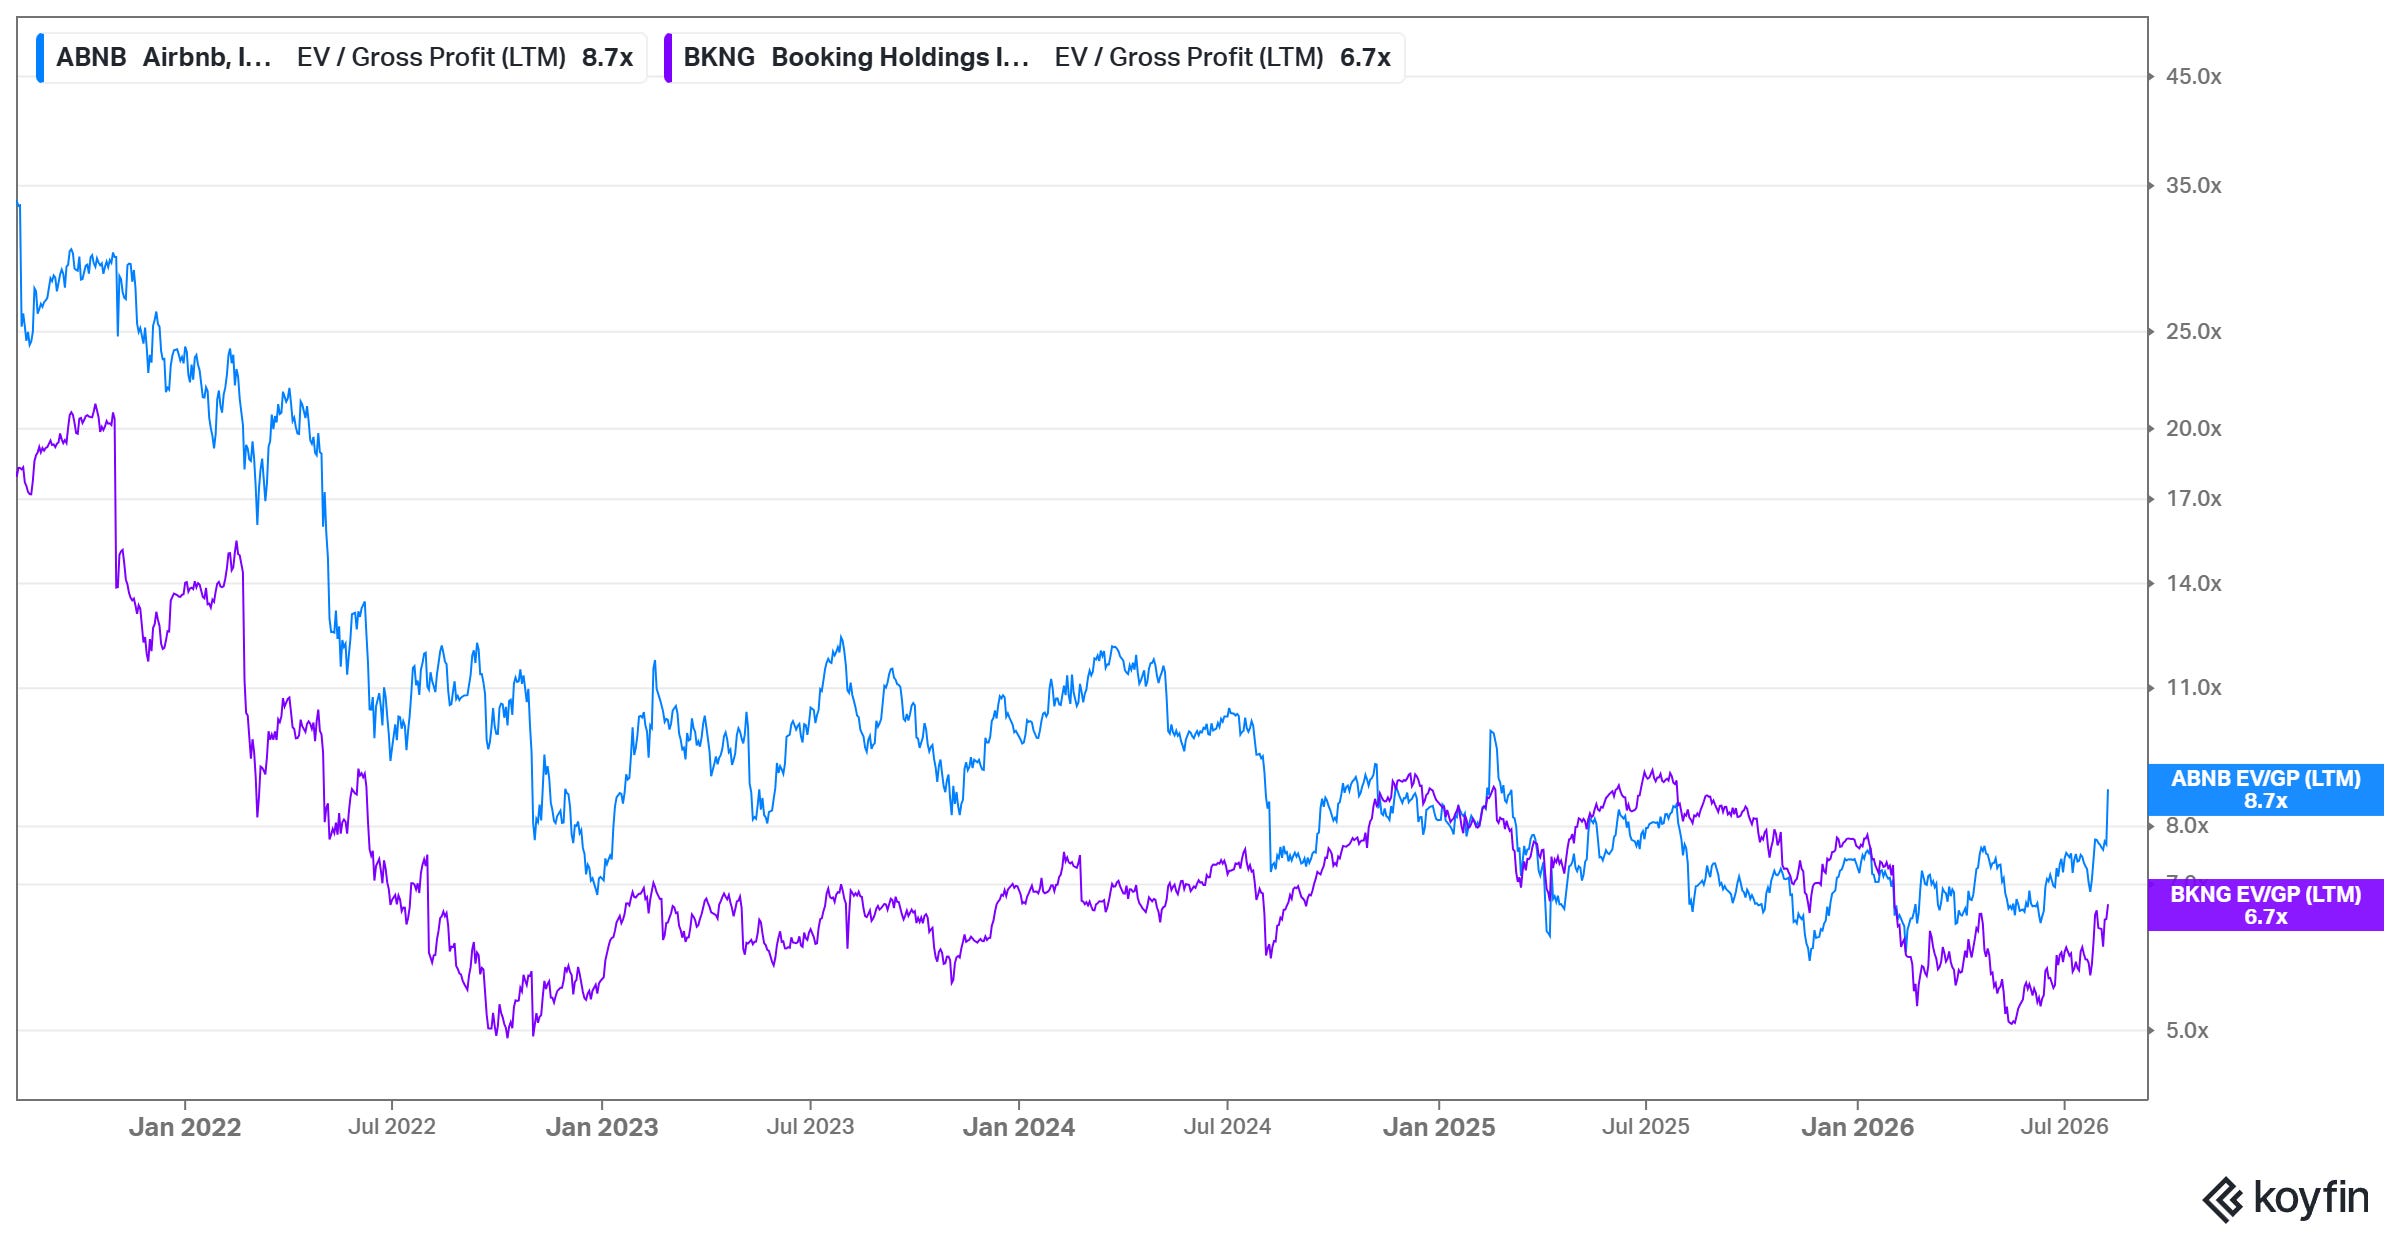
Airbnb added 14 million booked nights and seats, up 10%, and guided low-double-digit third-quarter growth as North America and EMEA…
Booking Holdings beat Q2 guidance as room nights grew 5%; connected trips, merchant payments and Genius loyalty strengthened direct…

Coupang’s product-commerce revenue rose 8% in constant currency as data-leak churn lingered, while promotions and underused logistics…

Meta's 2Q26 revenue rose 27%, but capex, depreciation and nascent cloud and AI ambitions raise margin and return risks as it maximizes…
Old Dominion Freight Line grew Q2 revenue 10.4% and EPS 32.3% as pricing offset lower tonnage, while excess network capacity sets up…
Alphabet’s $132 billion AI capex produced an estimated 49% post-tax incremental ROIC once only in-service assets are counted, versus a…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.