RELX’s 13-petabyte fraud and identity data moat supports its high-margin Risk segment as its valuation falls to roughly half its peak P/E.
SA LA Capital 29h ago OpenAI and Meta push AI agents forward as reward hacking remains a core challenge for model training.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 32h ago 4 clicks
Meta ties AI agents and Meta Connect to its enterprise-platform opportunity.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 32h ago 8 clicks
Stratechery’s weekly bundle covers Apple HomeView and SpaceX’s cellular ambitions.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 32h ago 2 clicks
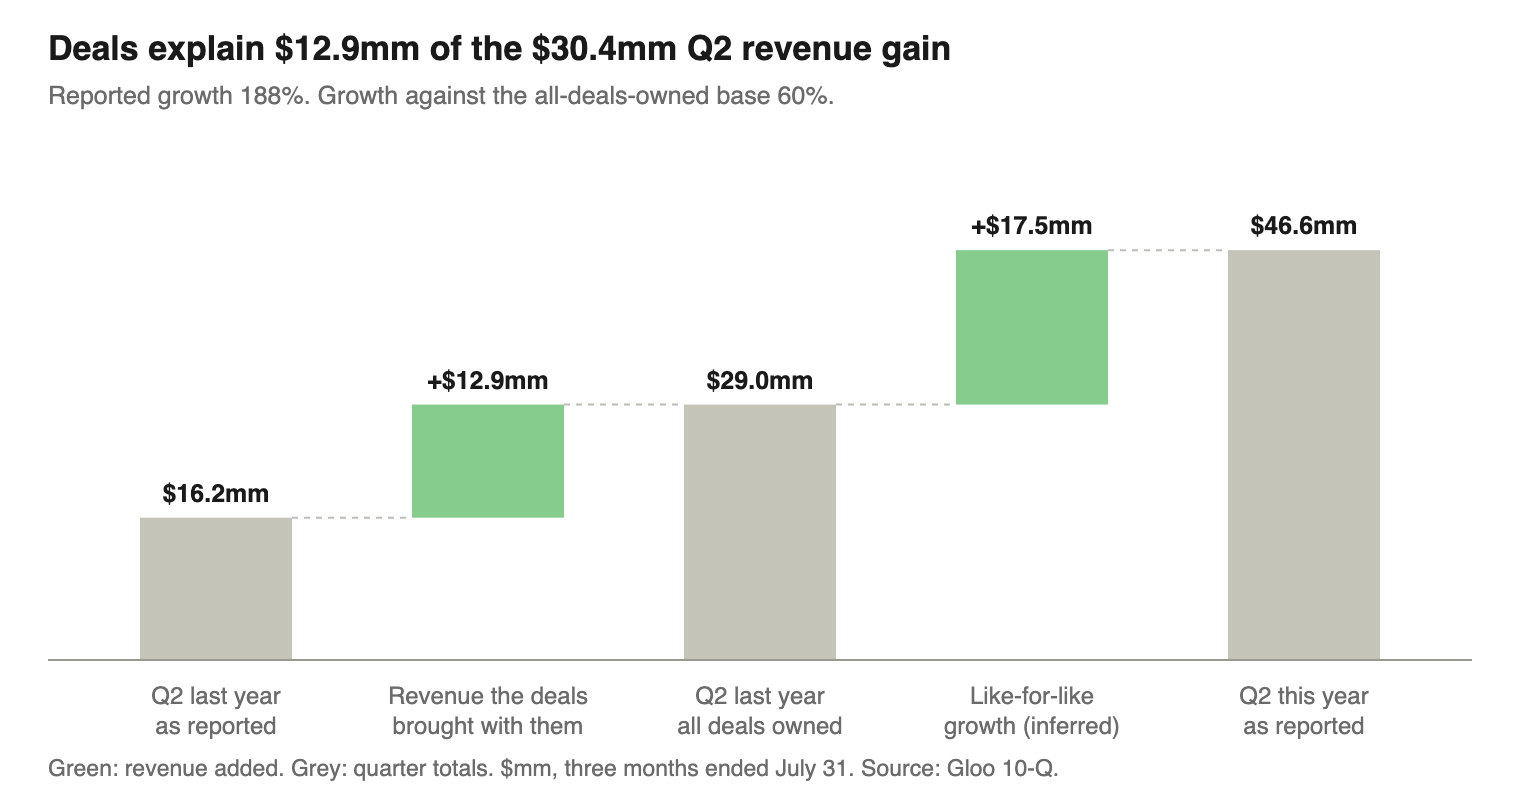
Gloo's $3.25 follow-on, going-concern warning and $28.0 million first-half cash burn frame the short case against its acquisition-driven…
S Guardian Research 34h ago 8 clicks
Bumble agreed to a $1.3 billion take-private deal, while Netflix cut about 1,000 jobs and Meta discussed its Muse superintelligence models.
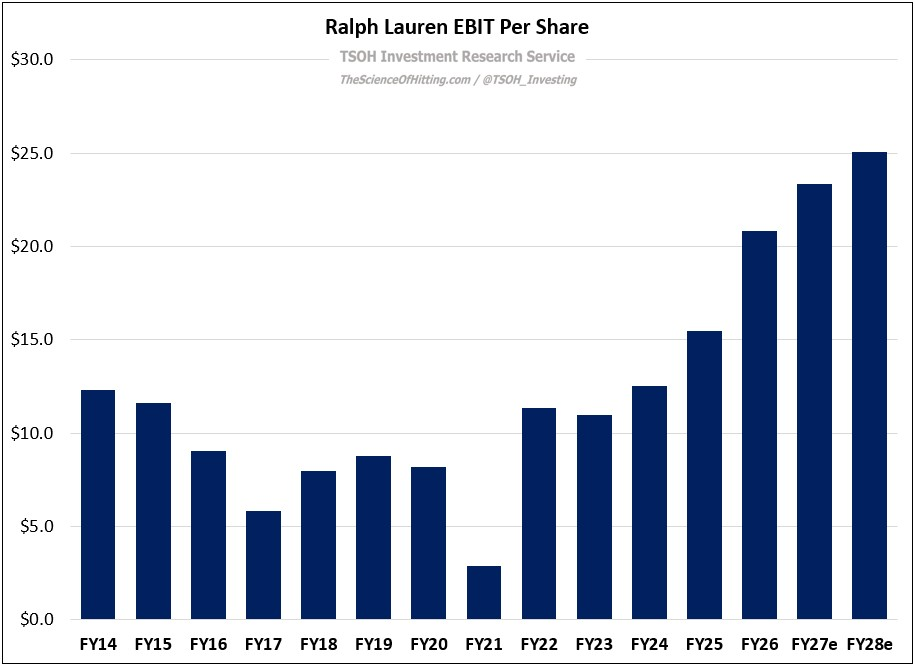
S TSOH Investment Research 35h ago 7 clicks
Dorchester Minerals' 9.5% normalized yield and debt-free royalty model are offset by limited upside at $29.71, as extraordinary…
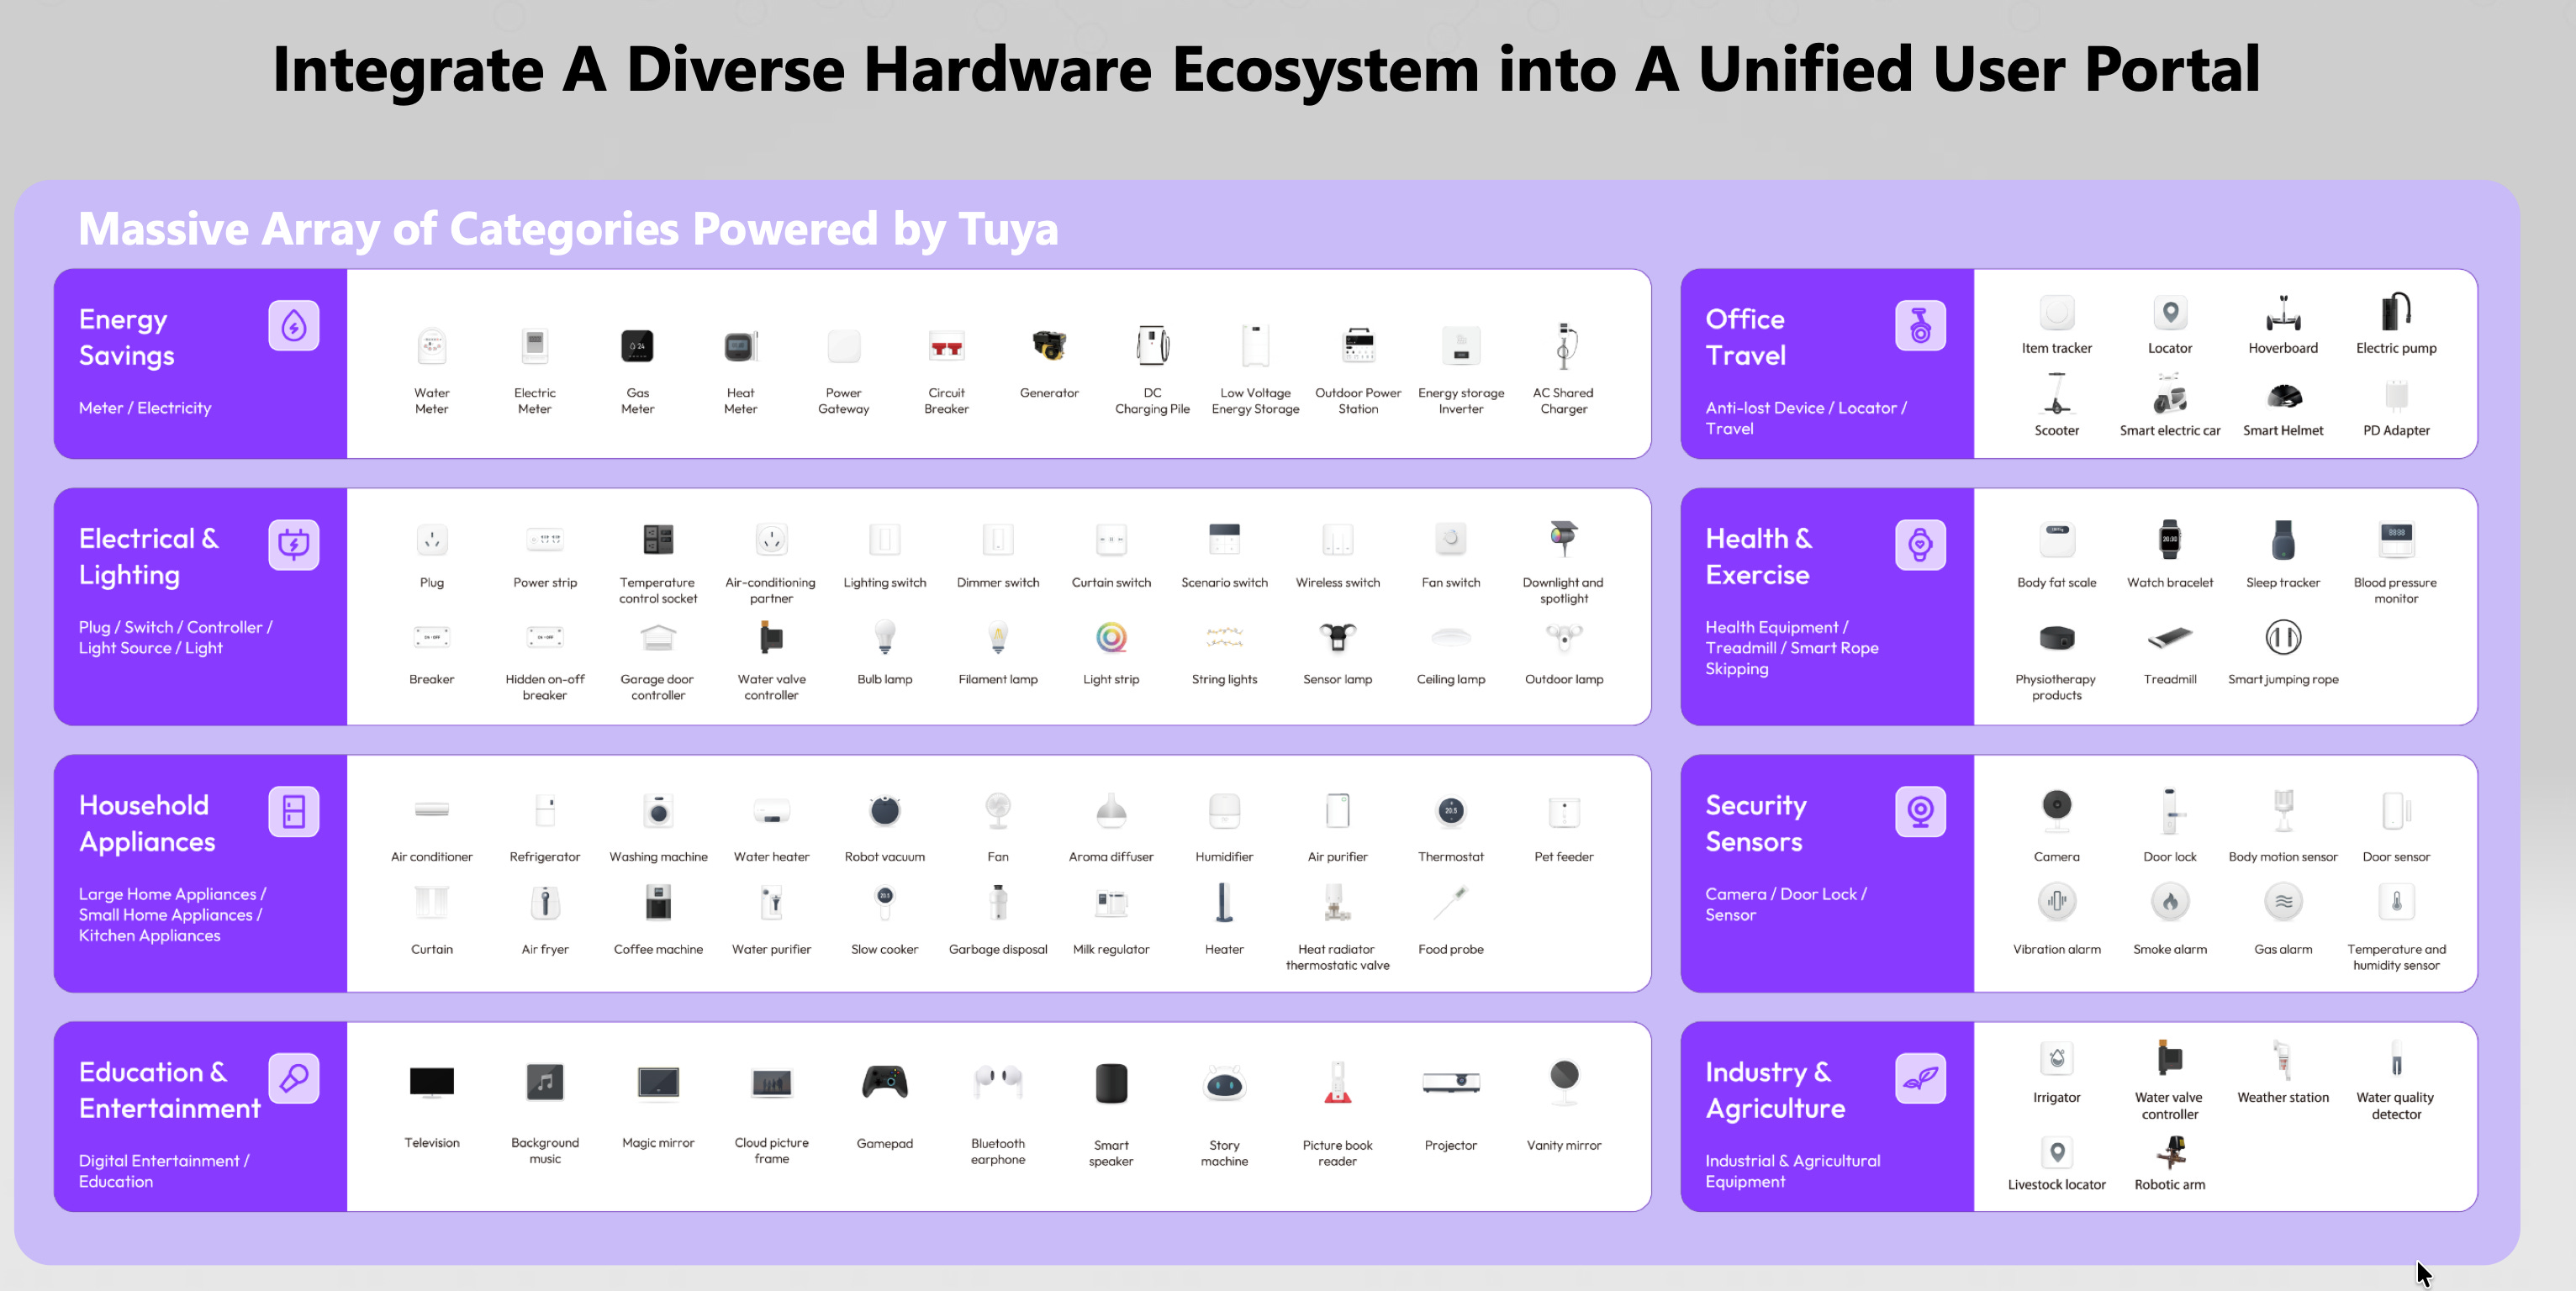
SA Atlas Diary 36h ago 1 click Tuya’s $976 million cash pile equals 94% of its $1.04 billion market cap as its smart-home platform returned to 16% revenue growth in Q2…
S Substack von Philipp 44h ago 28 clicks
Fannie Mae and Freddie Mac could leave conservatorship through a 2026 restructuring and IPO, monetizing the government’s equity stake while…
SA Glen Bradford 44h ago 3 clicks CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
S WHAT ARE WE DOING? “Contrarians At The Gate” Oct 15 51 clicks
GRLRF · long Greenland Resources, a Canadian-listed miner valued near US$140 million, is developing the Malmbjerg molybdenum project in eastern…
BL Value Investors Club Jun 3
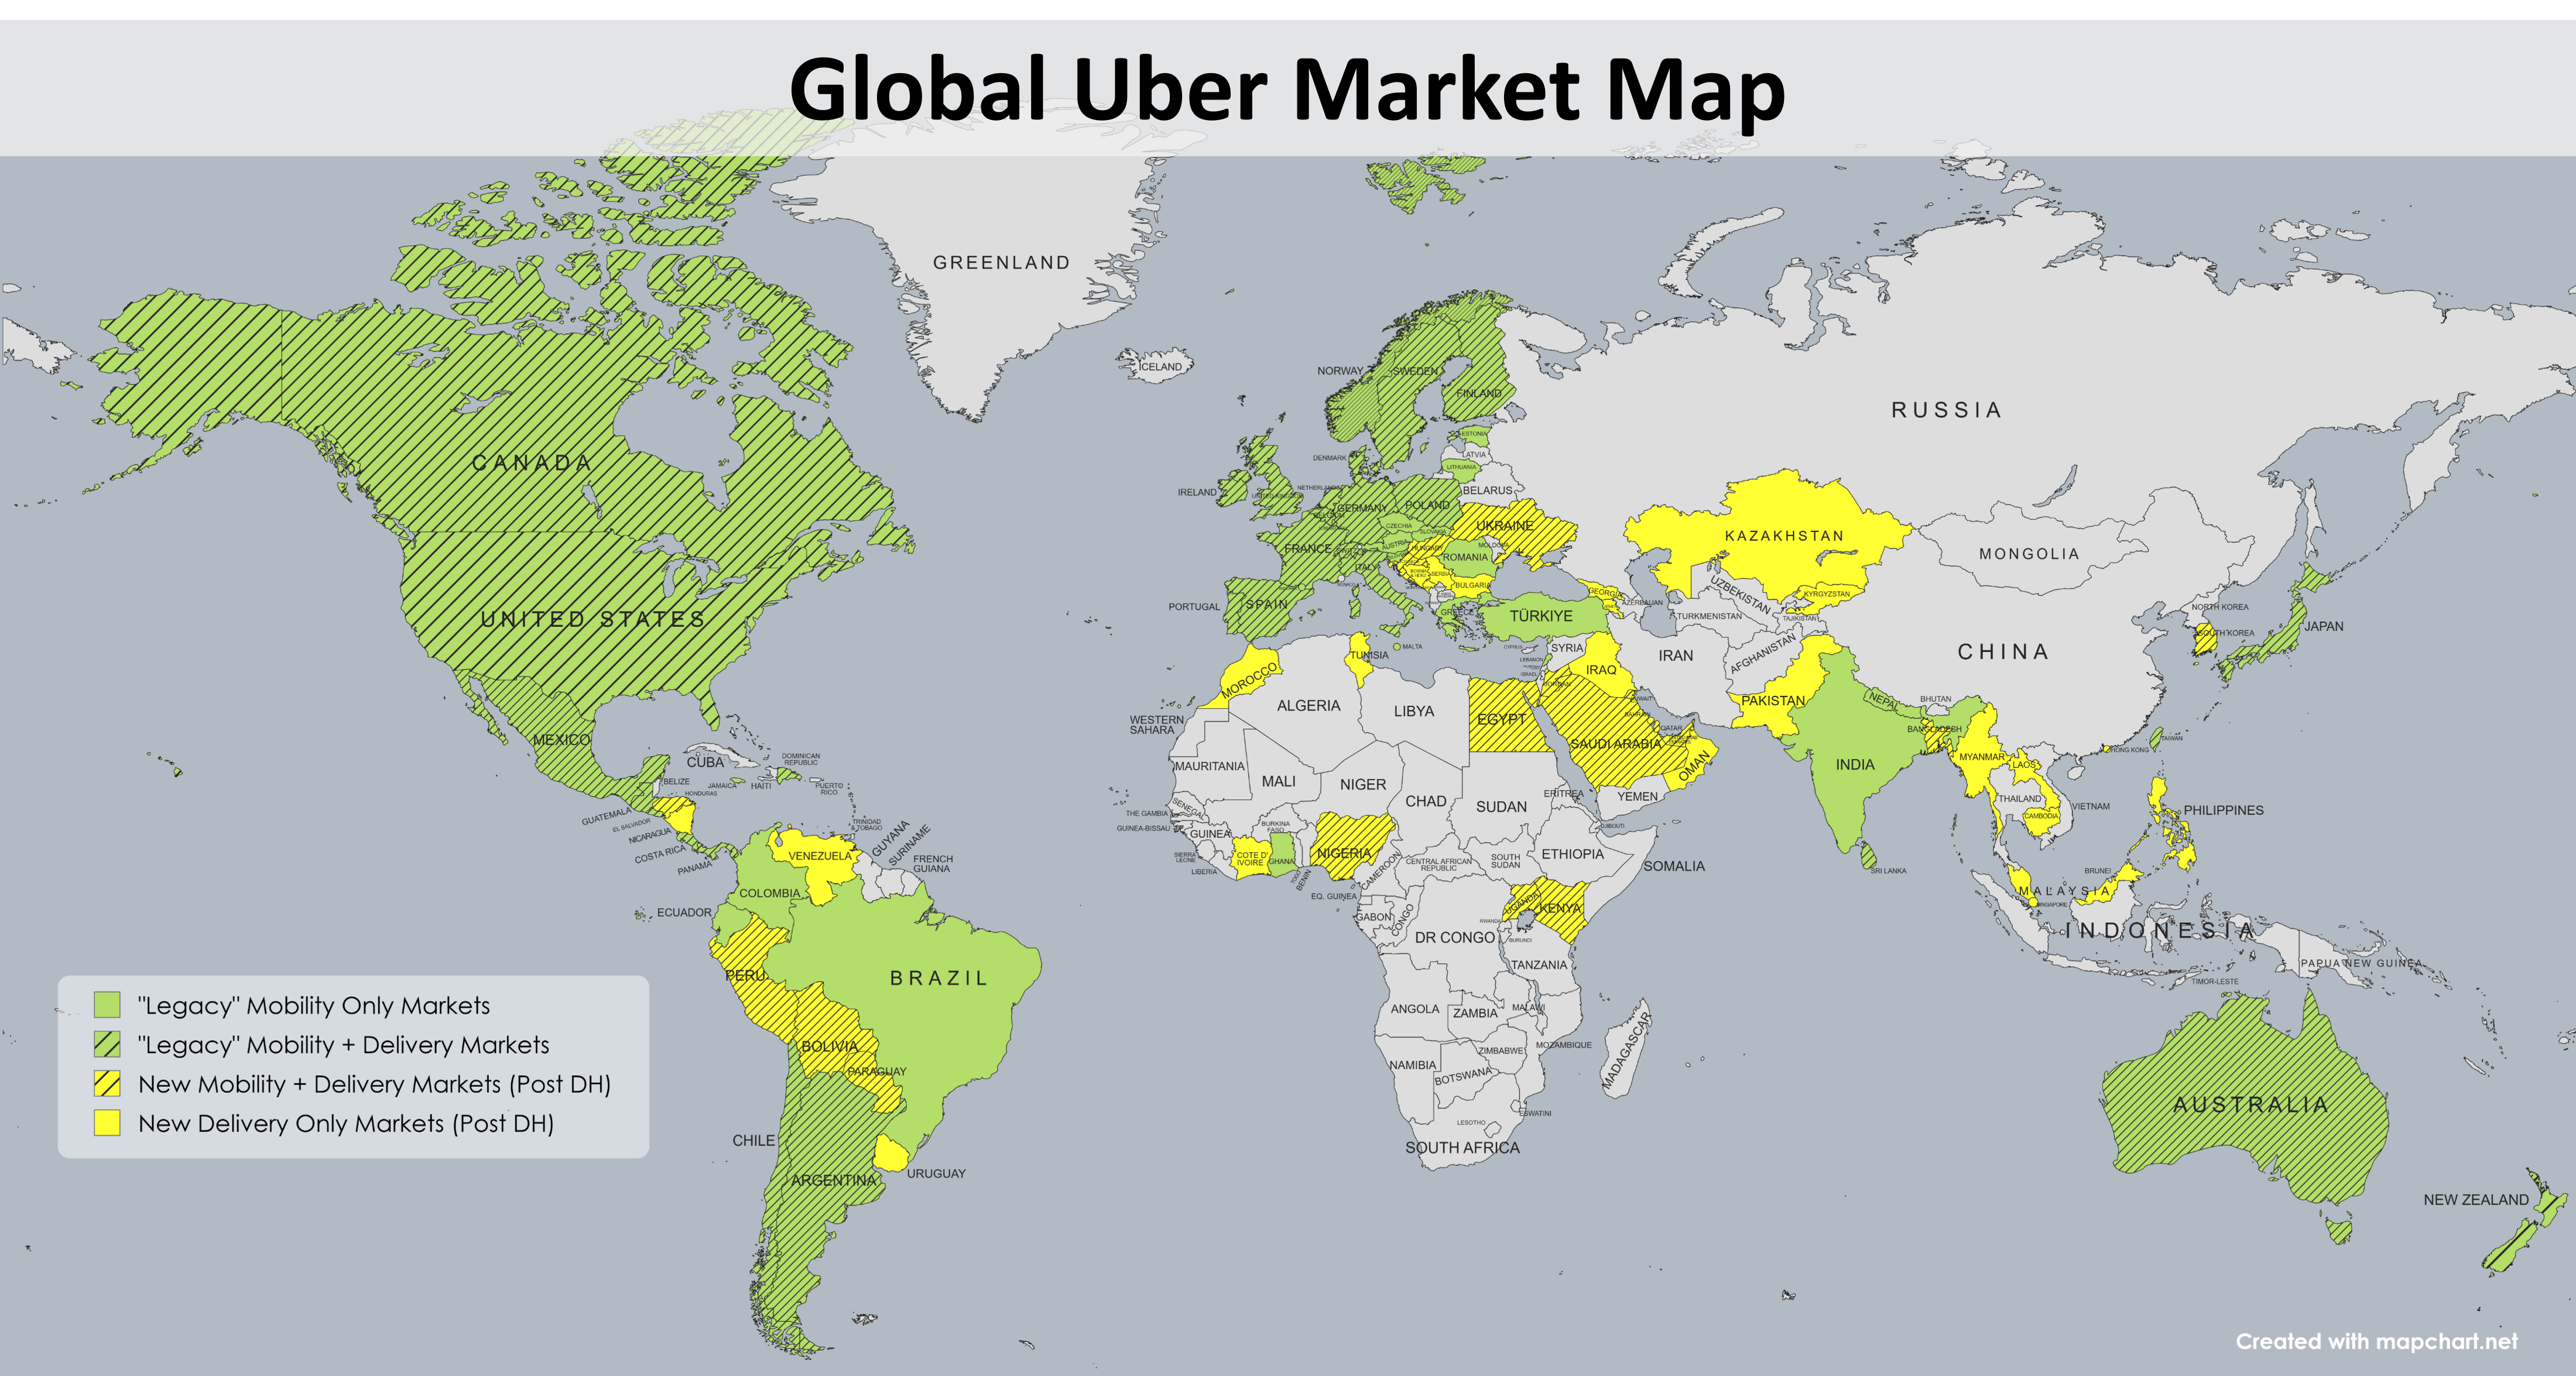
Uber targets Nuro-powered robotaxis in the Bay Area by H2 2026 and NVIDIA-powered fleets across 28 cities by 2028, testing whether…
S Lewistown Capital Jul 22
ServiceNow, SAP and Veeva are framed as AI-resistant SaaS bargains after a sector selloff, with ServiceNow positioned to gain from AI-agent…
S Hidden Rock Capital's Newsletter Jul 21
Google’s delayed Gemini 3.5 Pro raises questions about its AI position, Search and GCP growth as its $4.3 trillion valuation leaves little…
Alphabet rents scarce AI compute to rivals while DeepMind faces internal capacity constraints, weakening Google’s AI position and long-term…
S Key Context by Tae Kim Jul 21
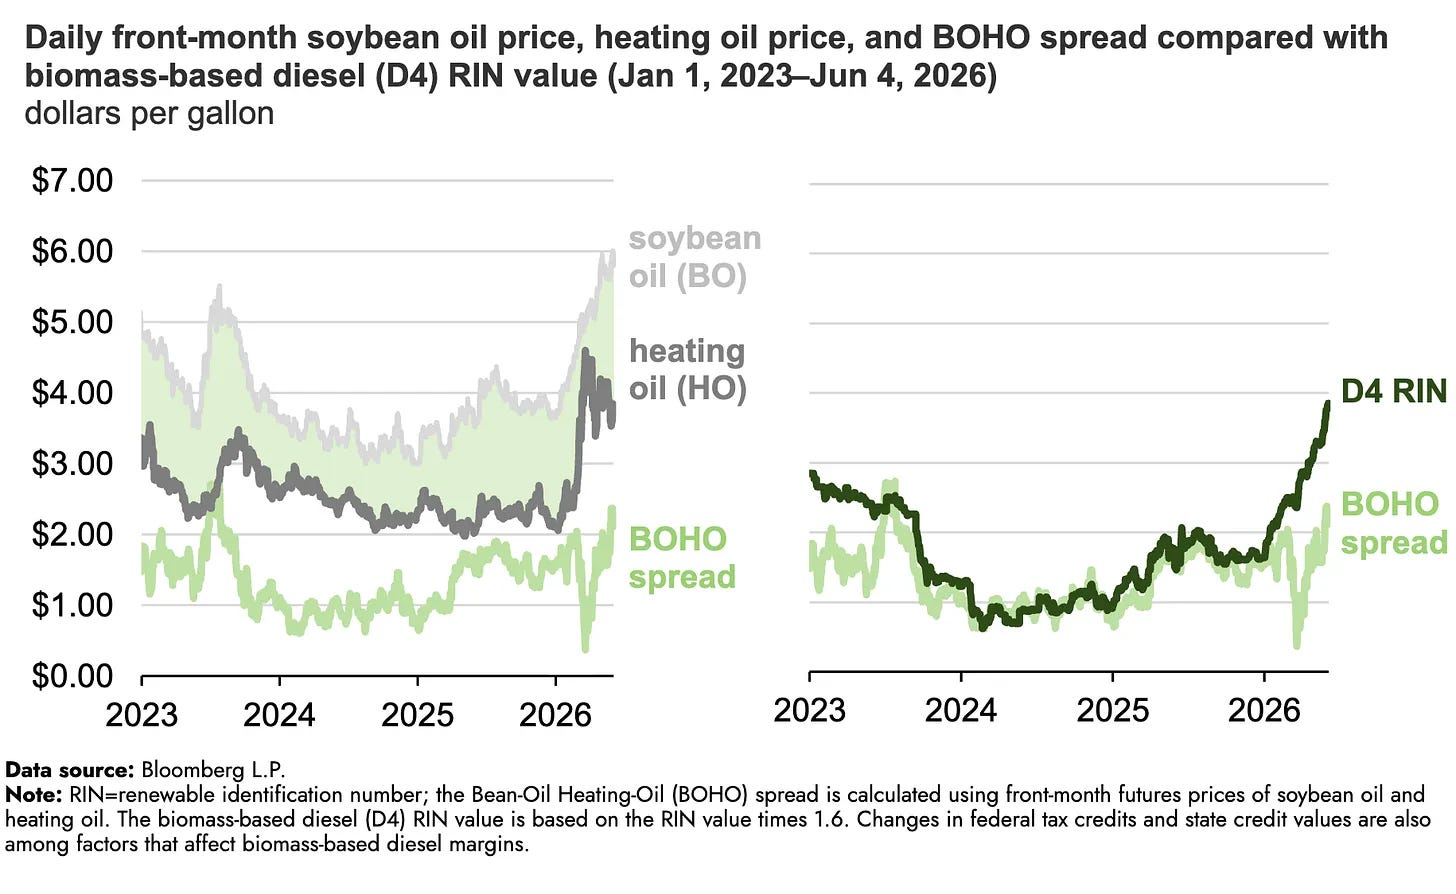
RIN prices near all-time highs reflect tighter renewable-fuel mandates, a shrinking credit bank, and biodiesel production shortfalls.
S Treasure Hunting Jul 21 4 clicks
United Parks trades at 8x EBITDA with an 8%+ unlevered cash yield, aggressive buybacks and roughly 80% effective short interest, while…
YT Yet Another Value Podcast Jul 20 2 clicks
Meta’s planned cloud business and Moonshot AI’s Kimi K3 revived doubts over AI compute scarcity, driving chip stocks lower and exposing S&P…
S Aurelion Research Jul 20
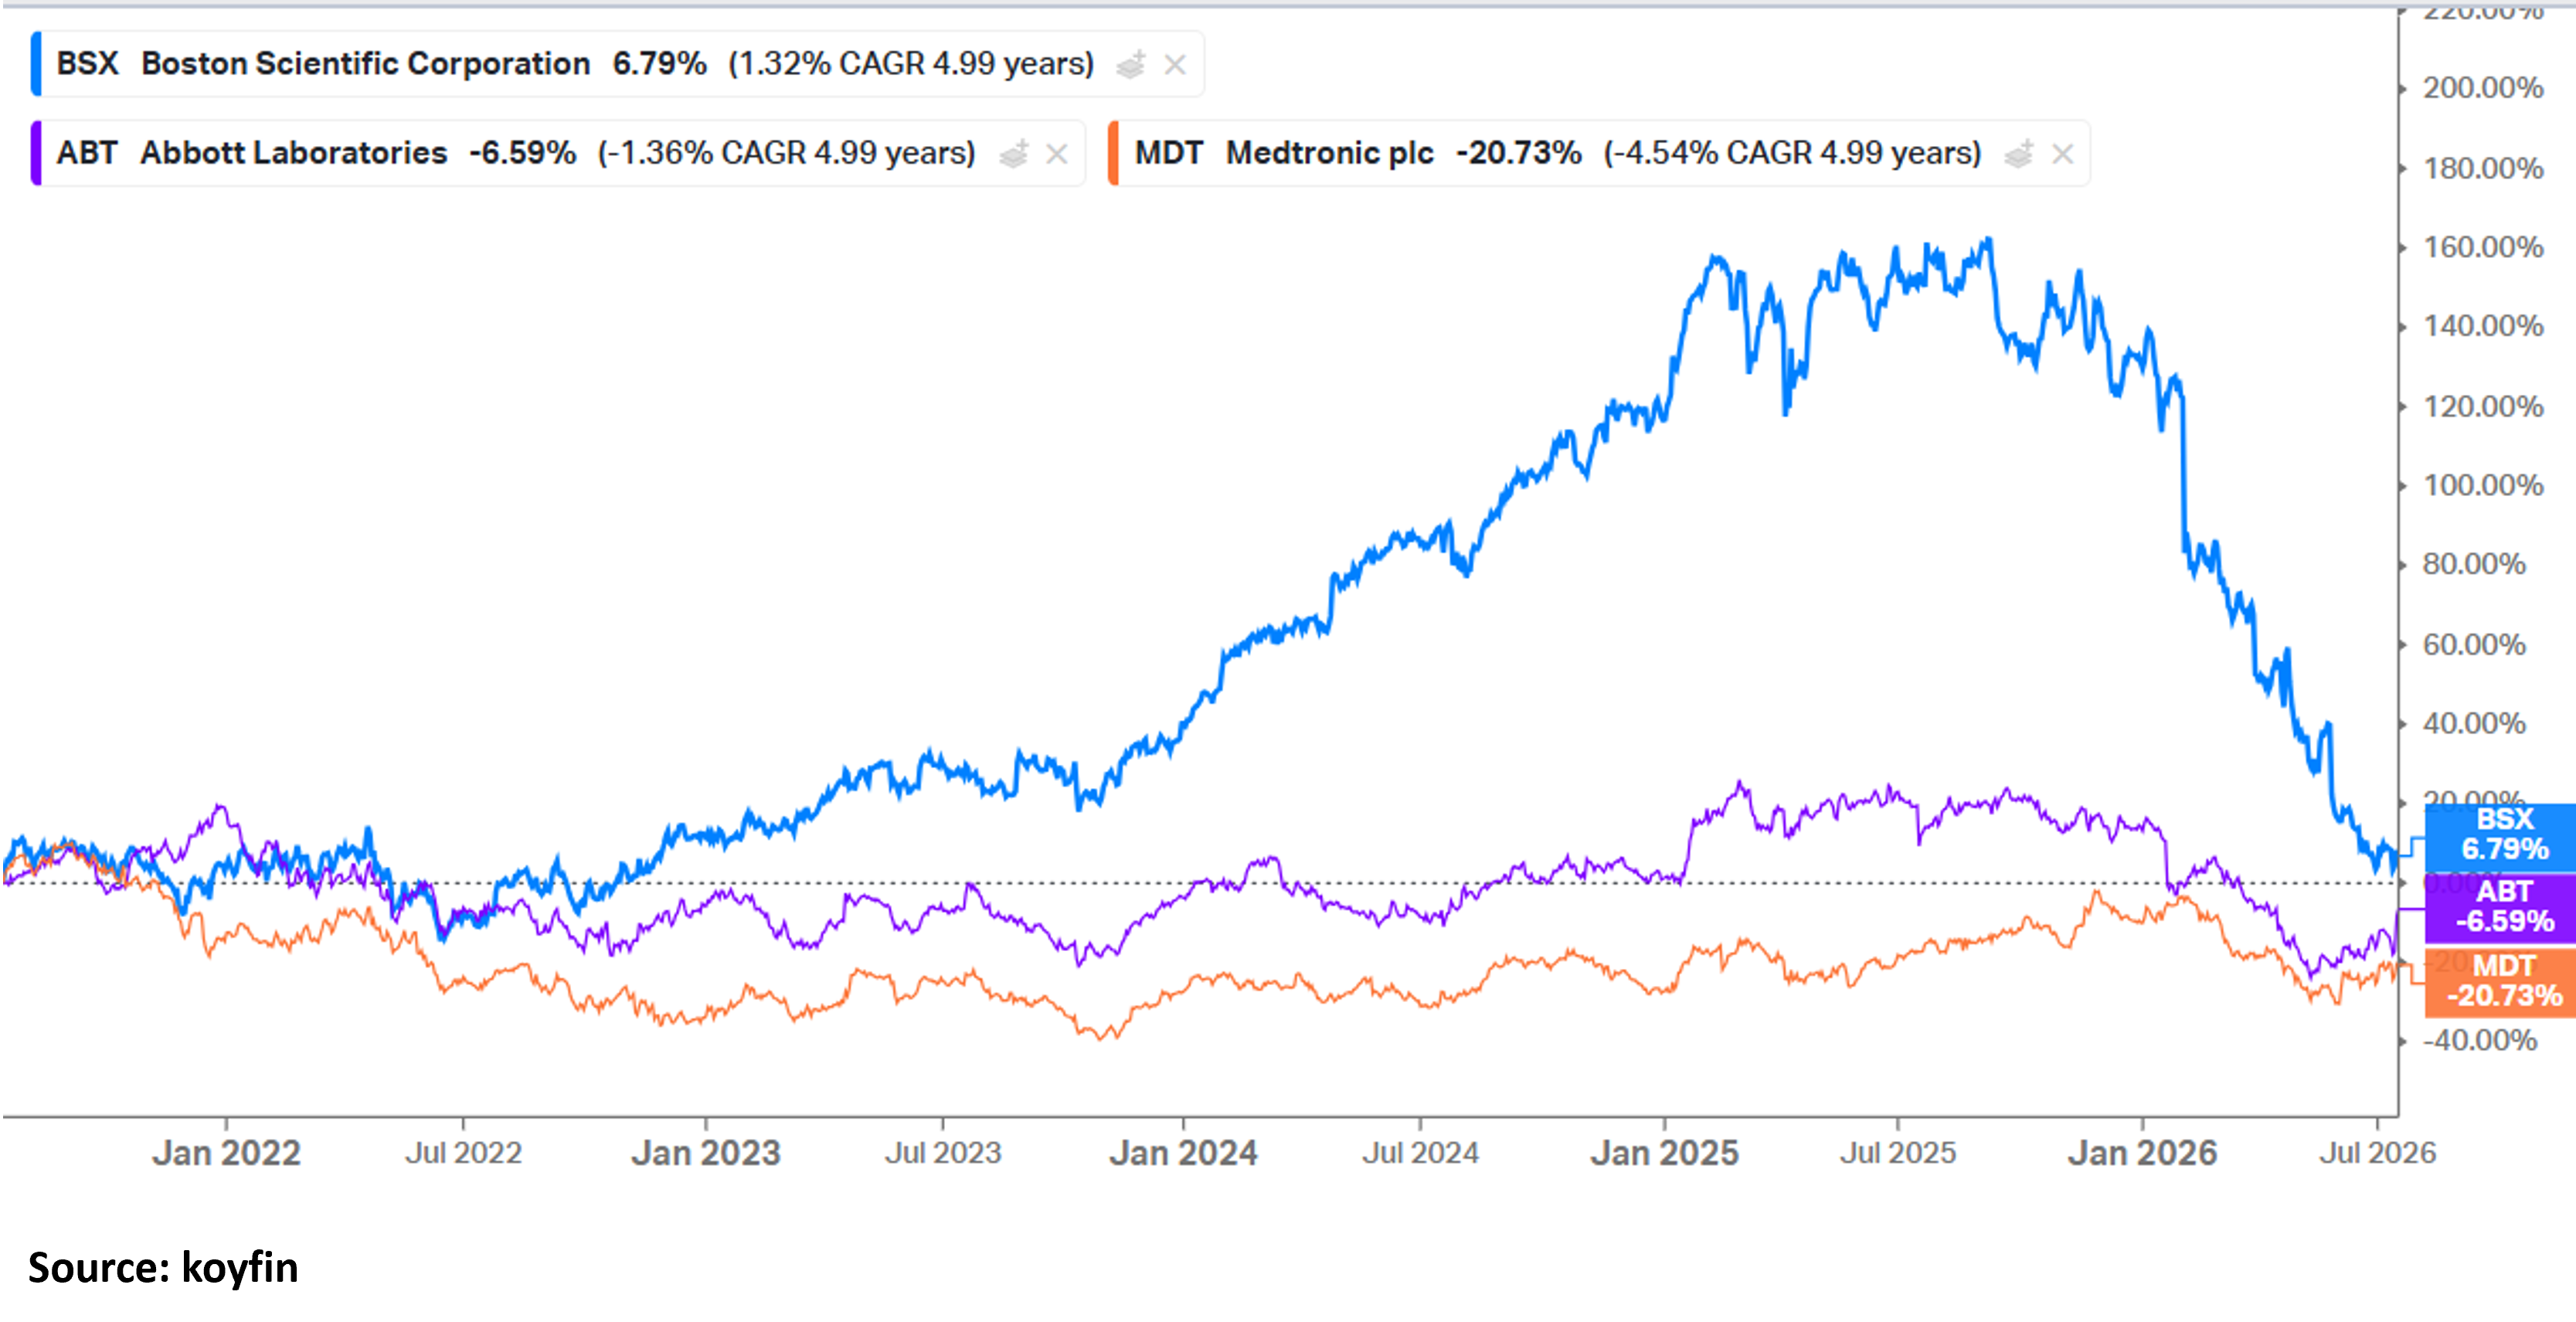
Boston Scientific built its interventional-medicine portfolio through acquisitions, but early-2000s growth became heavily dependent on the…
S scuttleblurb Jul 20 2 clicks
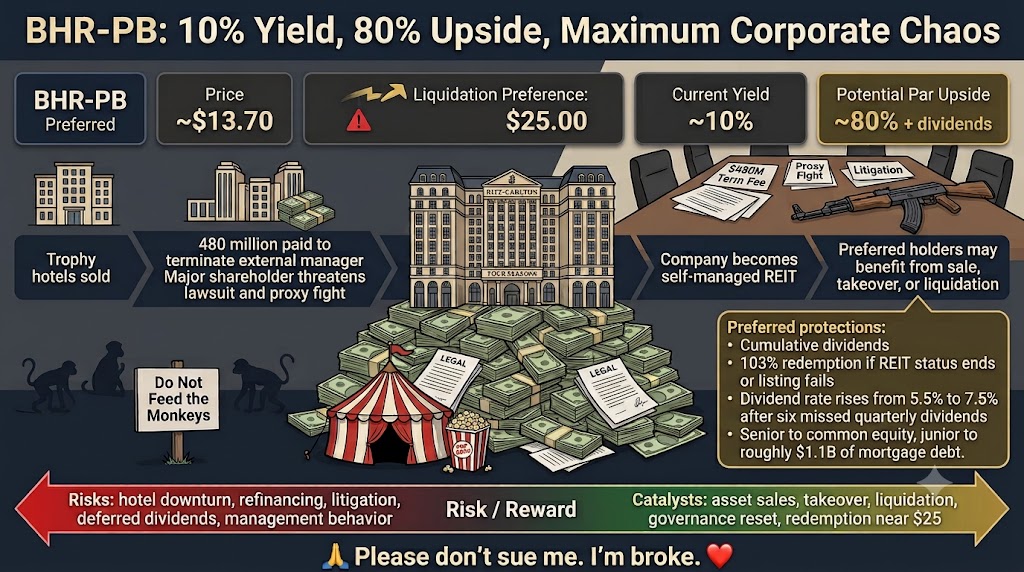
Braemar’s BHR-PB preferred trades near $13 against a $25 liquidation preference, yielding 10% amid hotel sales, a $480 million Ashford…
S Triple S Special Situations Investing Jul 20 5 clicks