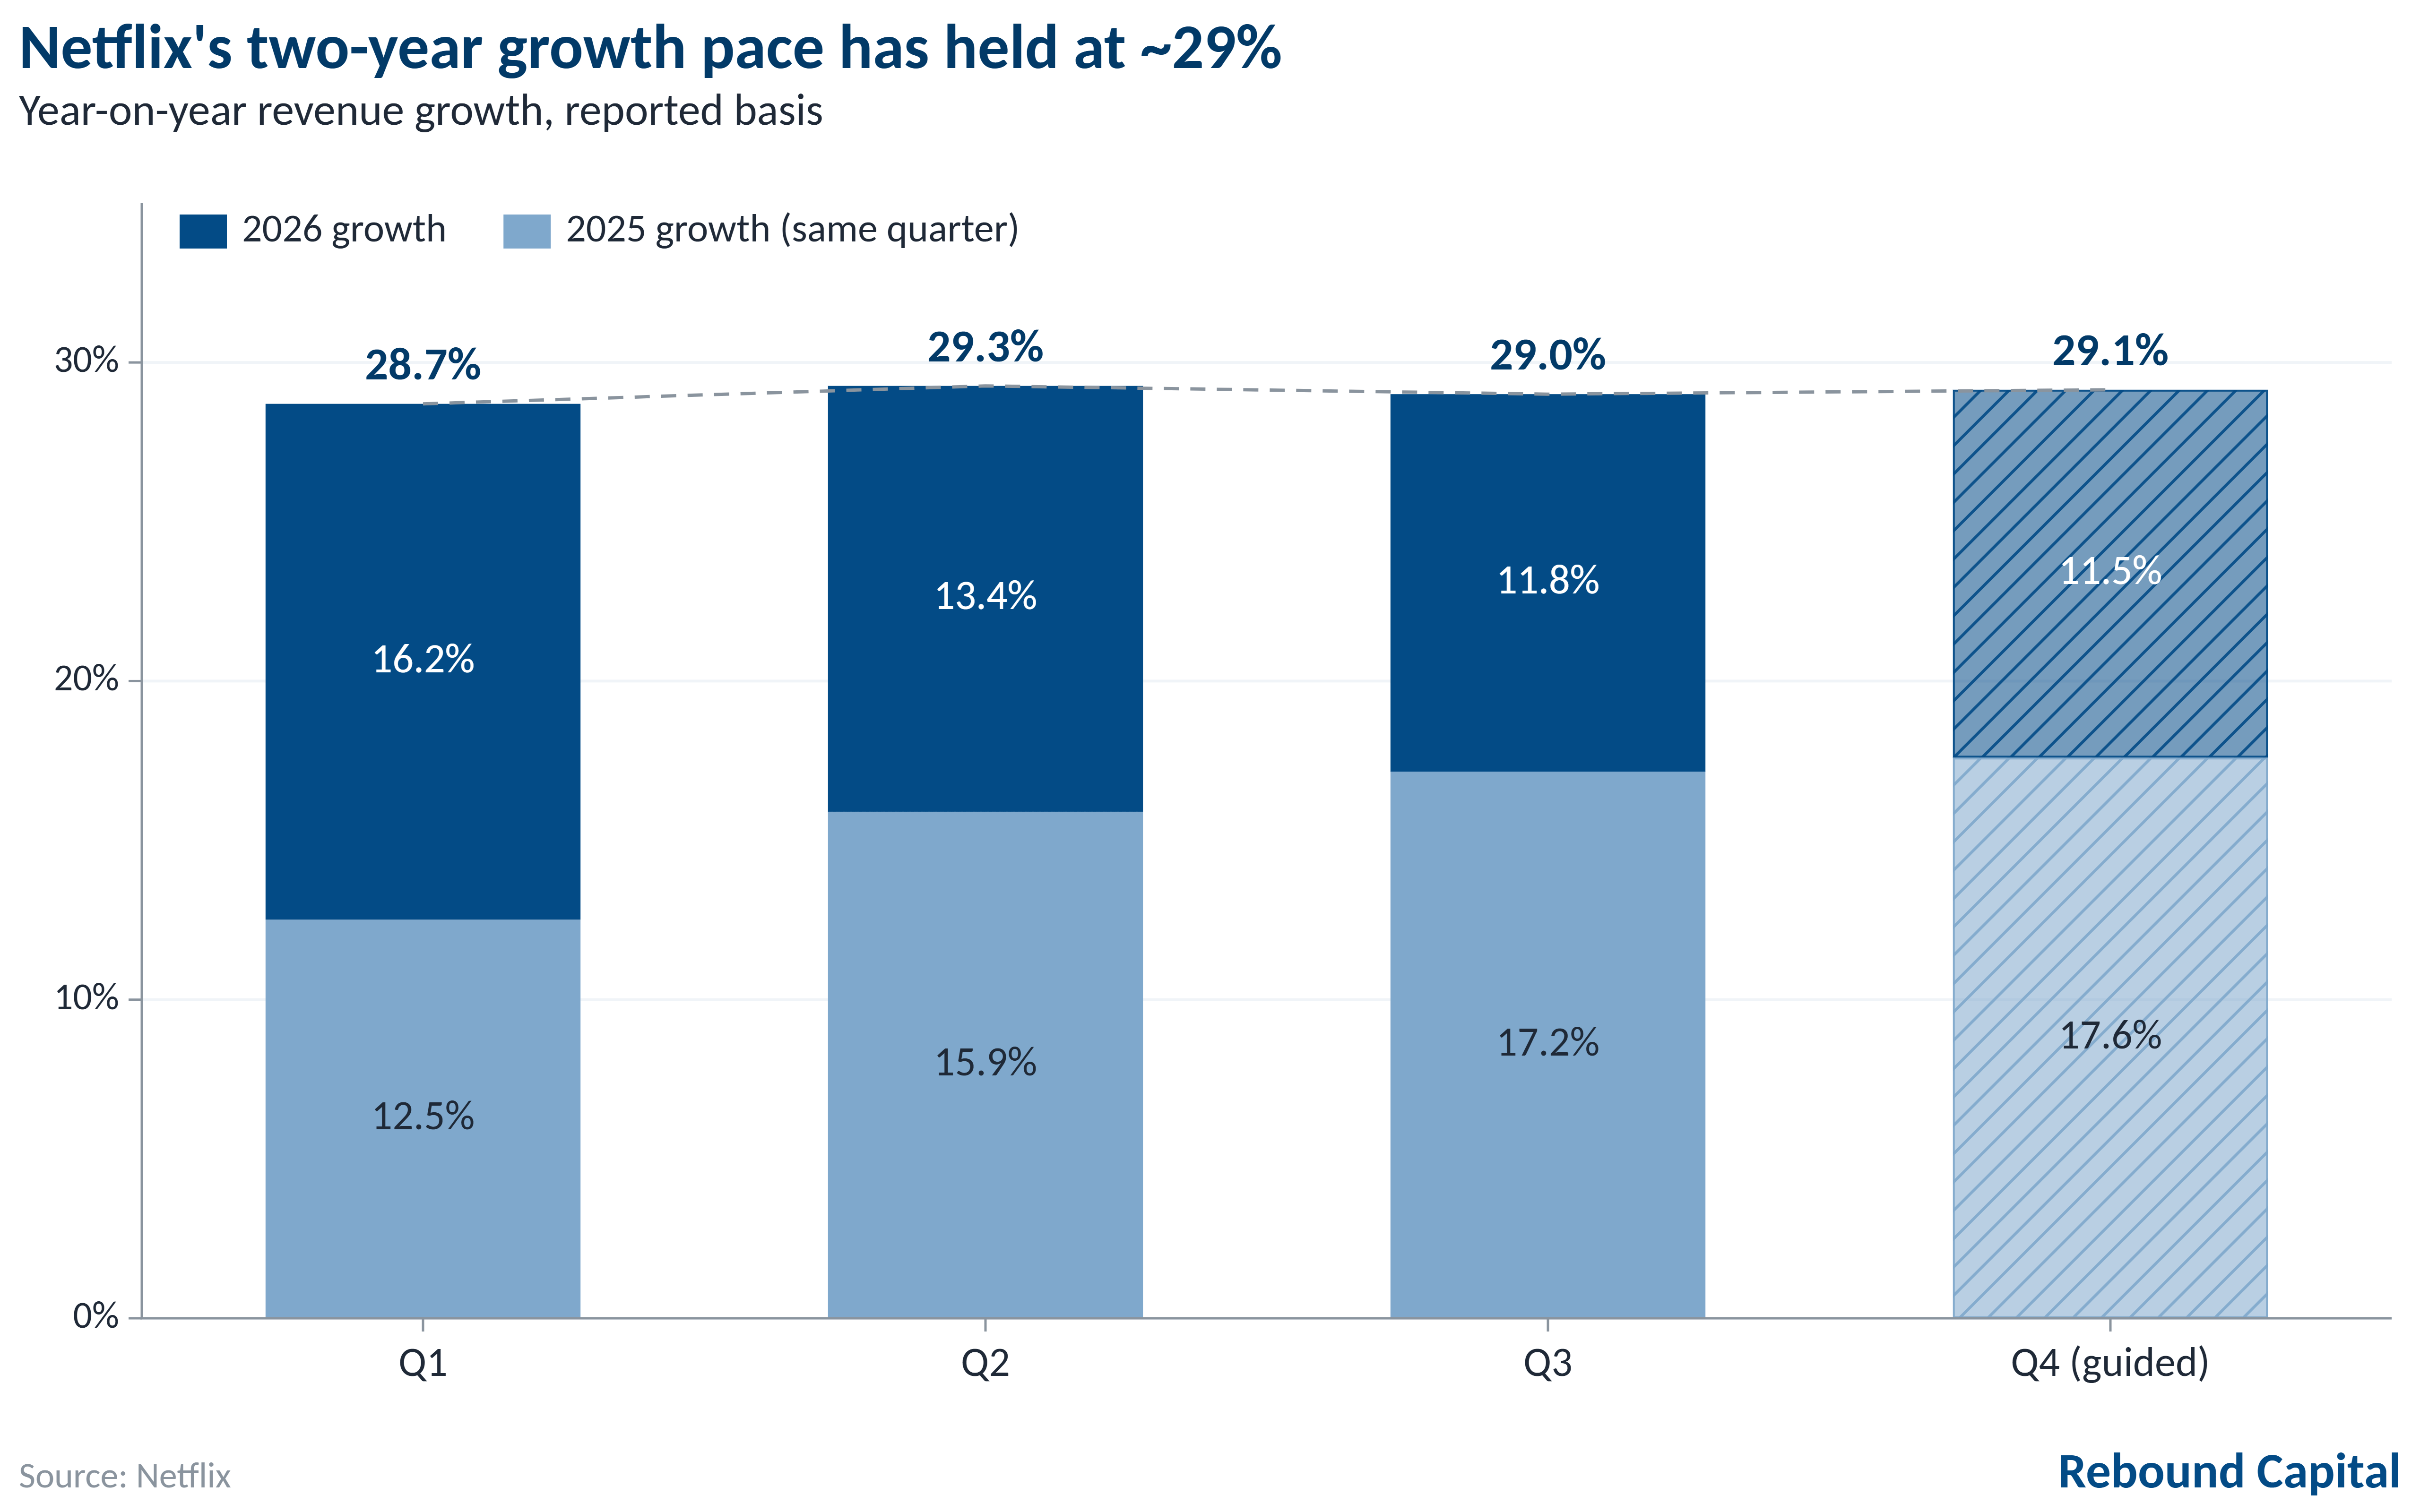Bumble is being taken private
Bumble agreed to a $6.05-per-share cash sale to Ithaca Holdings, 136% above its October 2 share price.
Bumble agreed to a $6.05-per-share cash sale to Ithaca Holdings, 136% above its October 2 share price.
They did the $GNW math… https://t.co/O8PuFZ6zfo https://t.co/vPm6hw8J7o
$NTSK absolutely smash print NNARR bounced to $54M + rev growth re-accelerated steller
This $APTV underperformance is interesting. 🤨 https://t.co/DHfLEh6lkf
*THOMA BRAVO'S PROOFPOINT IS SAID IN TALKS TO ACQUIRE VARONIS $VRNS https://t.co/dQEBQsKgGl
@HiddenGemsInves $CHCI ° Asset light, high ROIC asset manager ° Track record of revenue, FCF growth, clear strategy ° ~30% owned by Dwight Shar, founder/former CEO of $NVR ° move into data center development is a potential grand slam - a cheap call option
@ridireresearch Why $PURR instead of $THYP?
Free Recaps of the best new stock ideas, delivered every morning.
Bending Spoons has spent about $10 billion on software acquisitions, including pending Miro, while Q2 organic growth was 3% and all…
 Jack Bowman 2 clicks
Eli Lilly's Mounjaro and Zepbound drove 2025 revenue to $65.2 billion as the drugmaker expands AI partnerships with Nvidia, Isomorphic…
Gladstone Investment's 50% equity portfolio drove NAV and dividend gains, but five holdings make up 44.5% of fair value and heighten Level…
 Stephen Nemo 2 clicks
Silvercorp’s falling Ying grades, prolonged GC suspension, El Domo execution risk and Chaarat funding needs weaken its valuation despite…
ServiceNow is shifting from seat-based subscriptions to usage-based AI “Assists,” expanding revenue potential across its enterprise…
 Raul Shah 2 clicks
Snowflake says internal AI use is lifting revenue and profit, while customers show early implementation success.
Netflix’s earnings raise questions about whether its growth profile still merits a franchise valuation, alongside discussion of Disney’s…
Vicor’s $66.6 million in AI power-delivery royalties generated about $50 million of operating profit, eclipsing its module business as…
Novo Nordisk has only floated hair loss, while Veradermics’ Phase 3 oral minoxidil data lead a field of licensing and takeover candidates.
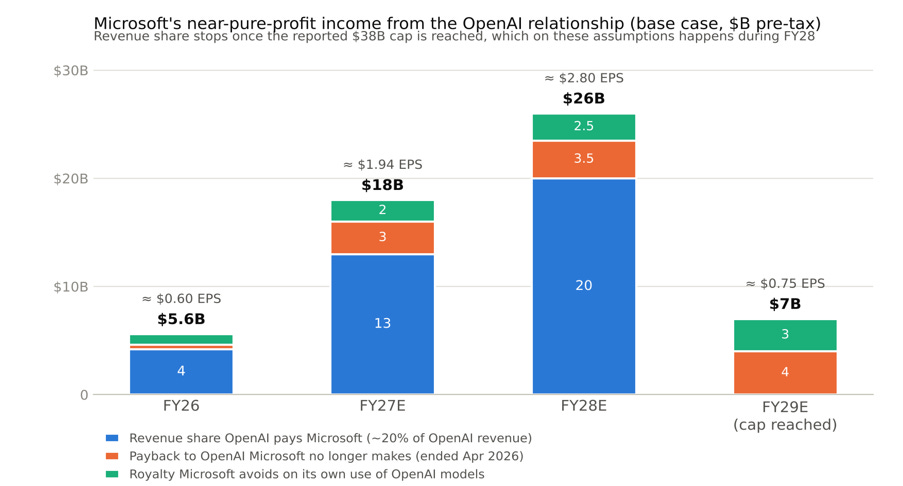
Microsoft booked $24.1 billion from OpenAI in FY2026, nearly a quarter of Azure revenue, raising questions over finite, high-margin…
RTX reported 11% sales growth to $25.0 billion, raised 2026 guidance and reached a record $340 billion backlog, while free cash flow fell…
HEICO sells FAA-approved aircraft replacement parts at 30% to 50% discounts to OEMs, gaining customers as restrictive aftermarket contracts…
Northrop Grumman posted 7% Q3 sales growth to $11.1 billion, lifted profit guidance and reached a record $109.6 billion backlog, led by…
Disney trades at 14x FY27 consensus EPS of $7.50 as parks, merchandise and streaming rebuild its franchise flywheel.
AGI Inc trades at 5.6x earnings after a 35% post-IPO decline, despite roughly 30% ROE and resilient INSS payroll-loan growth.
 Multiplo Invest 11 clicks
Amazon’s fulfillment network and customer-review base limit autonomous AI shopping agents, whose referrals generate under 0.5% of major…
TSMC says 2nm ramp costs and overseas fabs are temporarily pressuring gross margin as AI demand keeps semiconductor supply tight.
 Gil Rotstein 10 clicks
CoreWeave and neocloud peers face financing pressure, but sold-out GPU capacity and rising H100 and B200 rental rates support continued AI…
Group 1 Automotive’s $1.25 billion Atlanta borrowing lifts net corporate debt to about $4.4 billion; a 2009-style downturn leaves it near…
Goldman Sachs carries a $1,116 price target, based on $82.69 estimated 2027 EPS and growing recurring revenue from investment banking,…
 The Curious Analyst 4 clicks
Have a source we’re missing? Send your pick
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Ryan Canady
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.
Anything we’re missing?
Send us a pick