SaaS companies including Salesforce, ServiceNow, CrowdStrike, Synopsys and Veeva are ranked by agentic AI progress, from pilots to…
S Jimmy's Journal 12h ago 5 clicks
Lennar’s land-bank costs pressure homebuilding margins, while Flowers Foods weighs a Tastykake sale after falling branded-bread share,…
S Latticework by MOI Global 14h ago 10 clicks
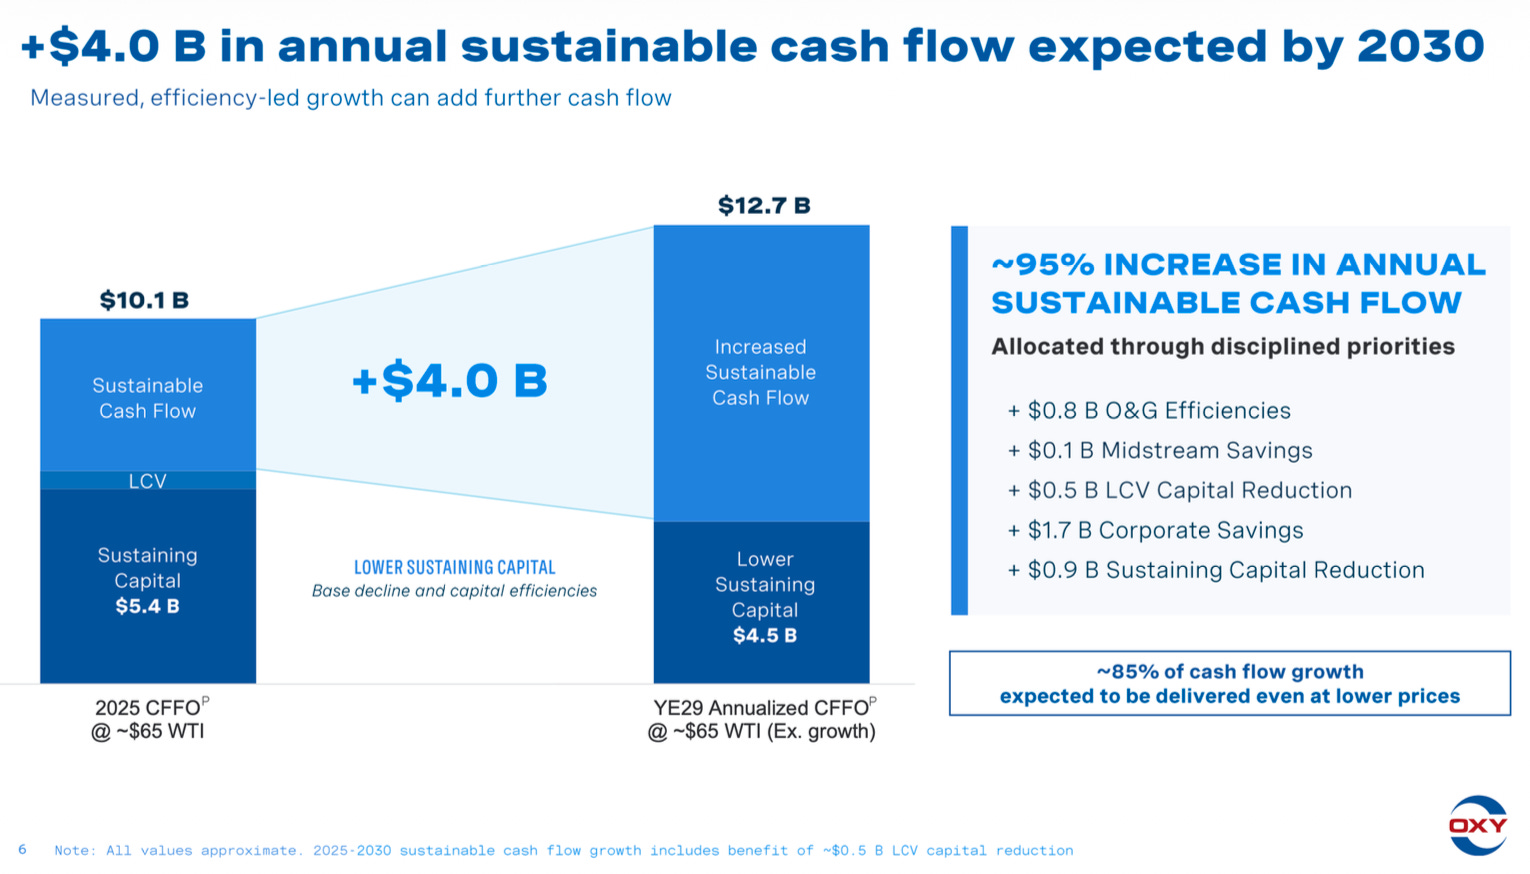
Occidental Petroleum’s debt should fall further after Q3 oil prices averaged $85 per barrel WTI and $91 Brent.
S Open Insights 16h ago 6 clicks
Apple’s HomeView strategy ties Siri, privacy and smart-home control to consumer trust in its vision for the home.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 23h ago 2 clicks
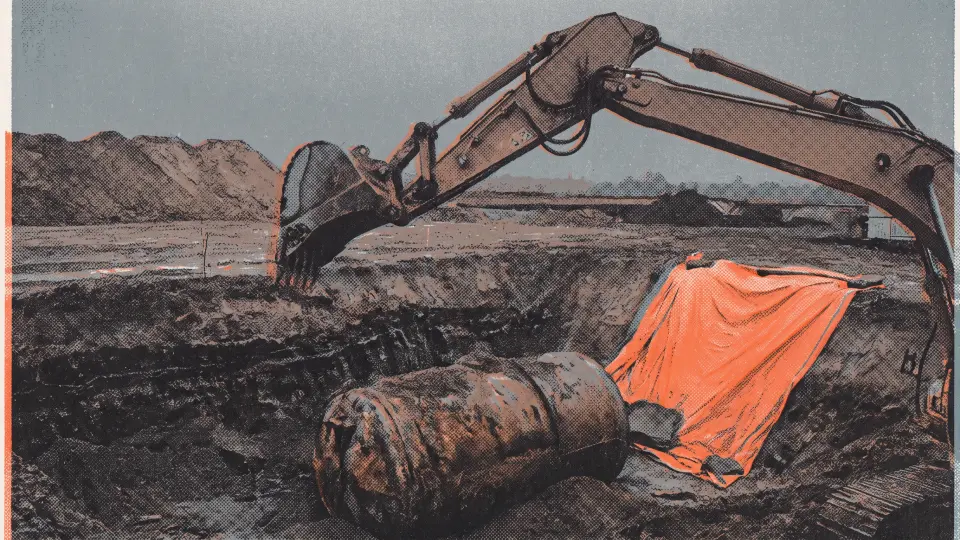
Digital Realty paid $120 million for Atlanta-area parcels including a former Army dump with buried carcinogens and military ordnance.
BL Hunterbrook 27h ago 22 clicks
Wells Fargo’s Q3 EPS beat and $12.5 billion net interest income failed to move shares, while WFC.PZ preferreds yield 7.10%.
SA Jeremy LaKosh 33h ago 6 clicks Semtech raised Q3 guidance and targets $3.2 billion of fiscal 2030 revenue, excluding upside from its AI data-center optical and copper…
S CV's Substack 44h ago 13 clicks
DigitalOcean’s CEO says the cloud company will not take on extraordinary leverage to fund its AI push.
BL The Technology Letter 47h ago 22 clicks
Optical-component vendor call covers 800G and 1.6T demand, AI cluster optical density, market share, pricing and 2027 growth for Coherent,…
S P Equity Research Oct 17 14 clicks
PayPal’s 10.3x forward earnings multiple and more than $6 billion in free cash flow frame a turnaround driven by cost cuts, Venmo and BNPL…
SA JR Research Oct 17 12 clicks Steve Eisman examines AI data-center debt, CoreWeave's tech correction and agentic AI's effect on banks as earnings season begins.
YT Steve Eisman Oct 16 22 clicks
OpenAI and Meta push AI agents forward as reward hacking remains a core challenge for model training.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. Oct 16 6 clicks
Meta ties AI agents and Meta Connect to its enterprise-platform opportunity.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. Oct 16 16 clicks
Stratechery’s weekly bundle covers Apple HomeView and SpaceX’s cellular ambitions.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. Oct 16 6 clicks
Bumble agreed to a $1.3 billion take-private deal, while Netflix cut about 1,000 jobs and Meta discussed its Muse superintelligence models.
S TSOH Investment Research Oct 16 11 clicks
GE Vernova’s 116 GW gas-turbine backlog and $5 billion in early-2026 data-center orders target AI-driven electricity demand, though its…
SA Todd Feldman Oct 16 3 clicks LLY · long Eli Lilly trades at 33 times this year’s earnings and 26 times next year’s, versus roughly 12 times for big pharma peers.
BL Value Investors Club Jul 18 2 clicks
CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
S WHAT ARE WE DOING? “Contrarians At The Gate” Oct 15 52 clicks
ASML’s patent filings point to a track-based die-to-wafer hybrid bonding tool that could challenge Besi in advanced logic packaging.
S SemiAnalysis Oct 15 12 clicks
CoreWeave’s 2032 notes yield over 15%, signaling a 54% default probability as borrowing costs exceed rental yields on AI infrastructure…
SA Dustin Quasney Oct 15 24 clicks