Nvidia’s Q3 FY27: The Reassurance Before the Storm
Nvidia faces allegations over China and Southeast Asia sales, financial reporting and governance ahead of Q3 FY27 results.
Nvidia faces allegations over China and Southeast Asia sales, financial reporting and governance ahead of Q3 FY27 results.
Nvidia faced China workaround enforcement concerns as technology fell 6%; energy rose 4.5%, while the company raised eFY28 revenue growth…
MiniMed's 15.8% Q1 organic growth and 20% U.S. pump-volume increase support a product-cycle recovery as split-off selling fades.
 Equity Eagle 1 click

Nvidia reported $115.8 billion in Q3 revenue, up 103%, and guided $130 billion, while Jensen Huang’s resignation left Colette Kress as…
Pfizer’s Q3 revenue reached $16.58 billion, launched and acquired products grew 32%, and FY26 guidance rose to $62 billion to $64 billion.
 Louis Gerard 1 click
NVIDIA’s fiscal third-quarter 2027 results are its first earnings report since Jensen Huang’s resignation as CEO.
UFP Industries trades near its 2022 price despite EPS falling 62%; a $95–$105 valuation assumes $6.30 normal-year EPS, with freight and…
 Tim Travis 3 clicks
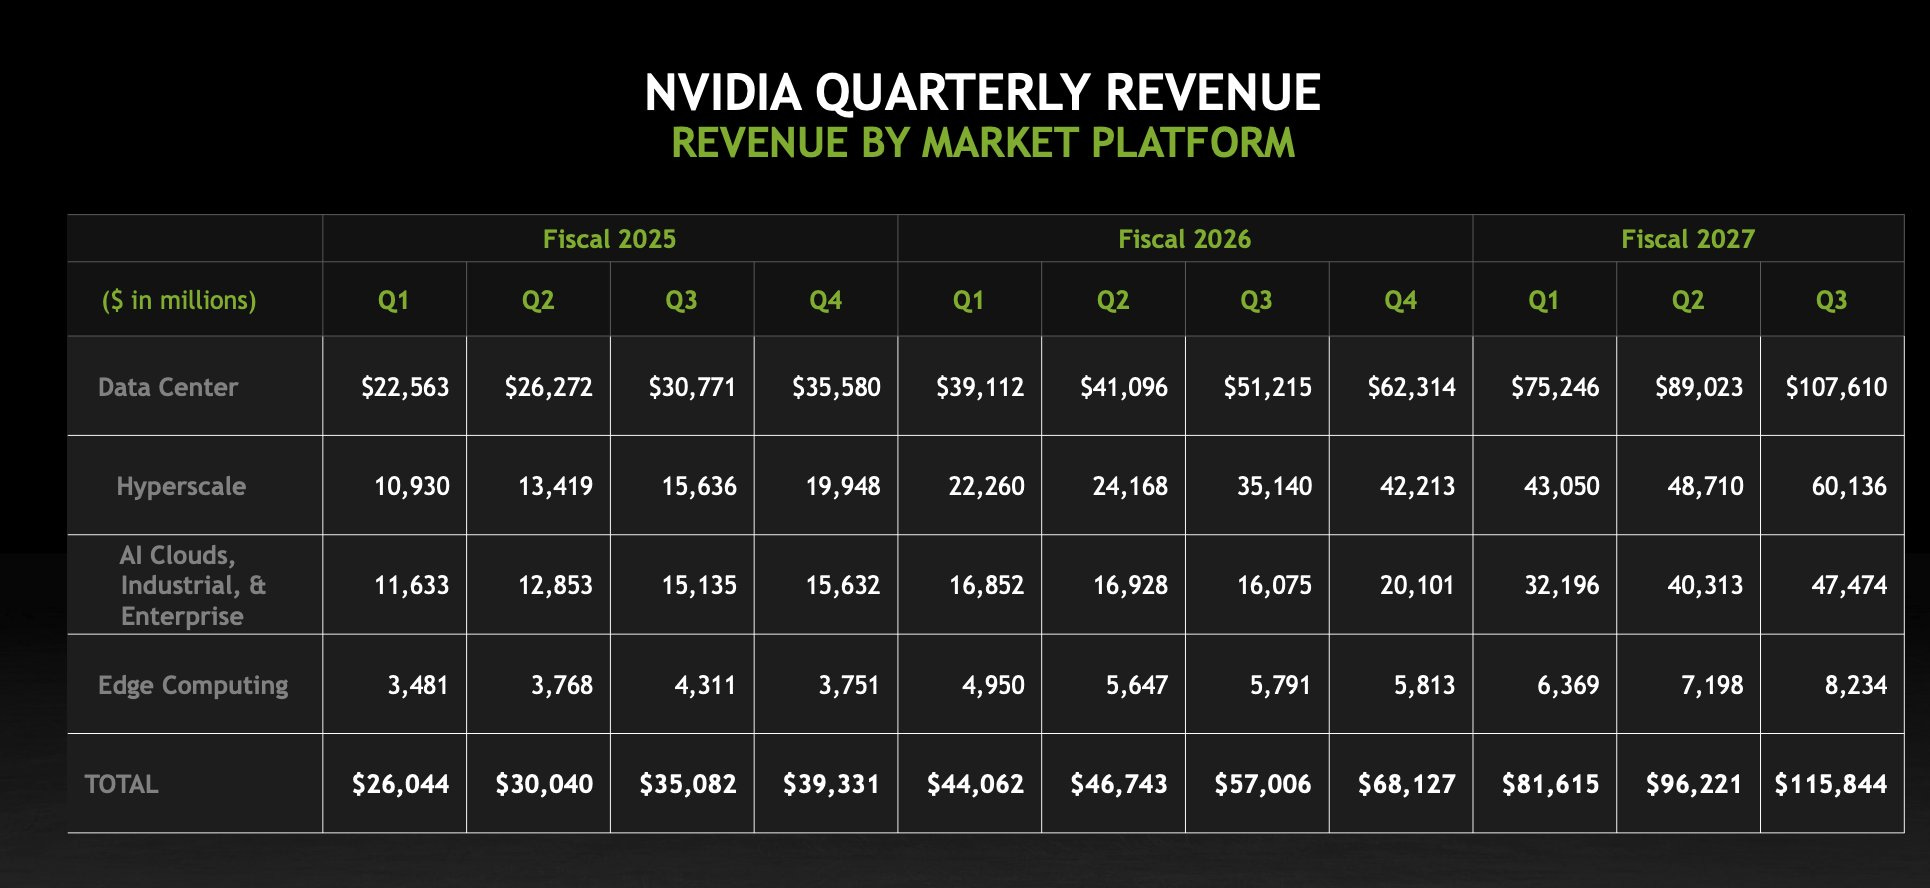
Nvidia reported $115.8 billion in Q3 revenue, up 103%, and raised its fiscal 2028 growth outlook to 75% as interim CEO Colette Kress…
Century Aluminum (CENX) could benefit from U.S. tariffs, Midwest aluminum premiums and constrained global supply, with the stock trading…

Figma grew Q3 revenue 43% to $391.4 million, raised FY2026 guidance to nearly $1.5 billion and guided Q4 above consensus despite the stock…
Nvidia raised its fiscal 2028 growth outlook, but shares reversed as investors focused on uncertainty beyond January 2028.
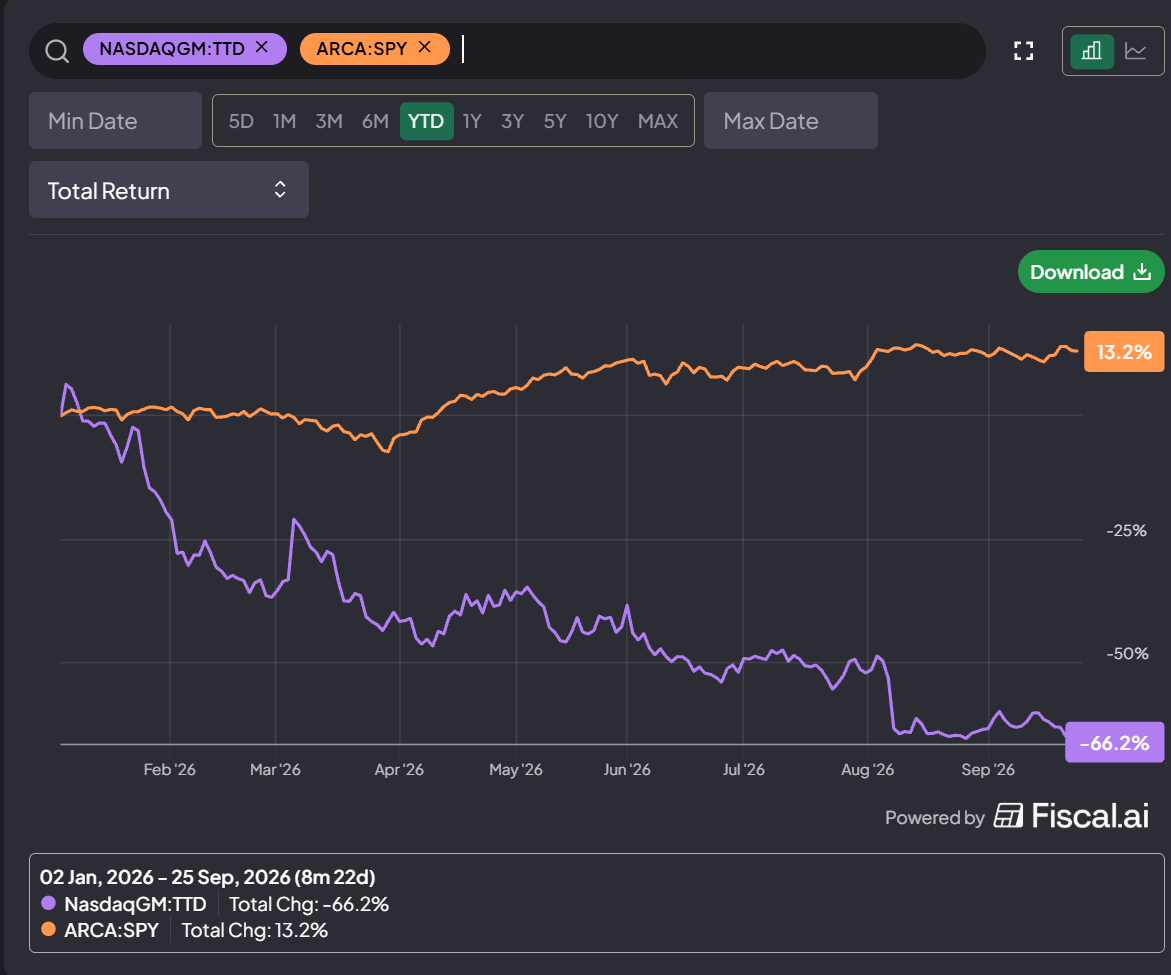
The Trade Desk’s CEO received a new 10-year option package targeting $105 per share as the company seeks shareholder approval to reprice…
Beam Therapeutics’ BEAM-302 AATD gene-editing program anchors its 2028–2029 upside, while a 2–3 year cash runway leaves dilution likely…
 Robert J. Lake
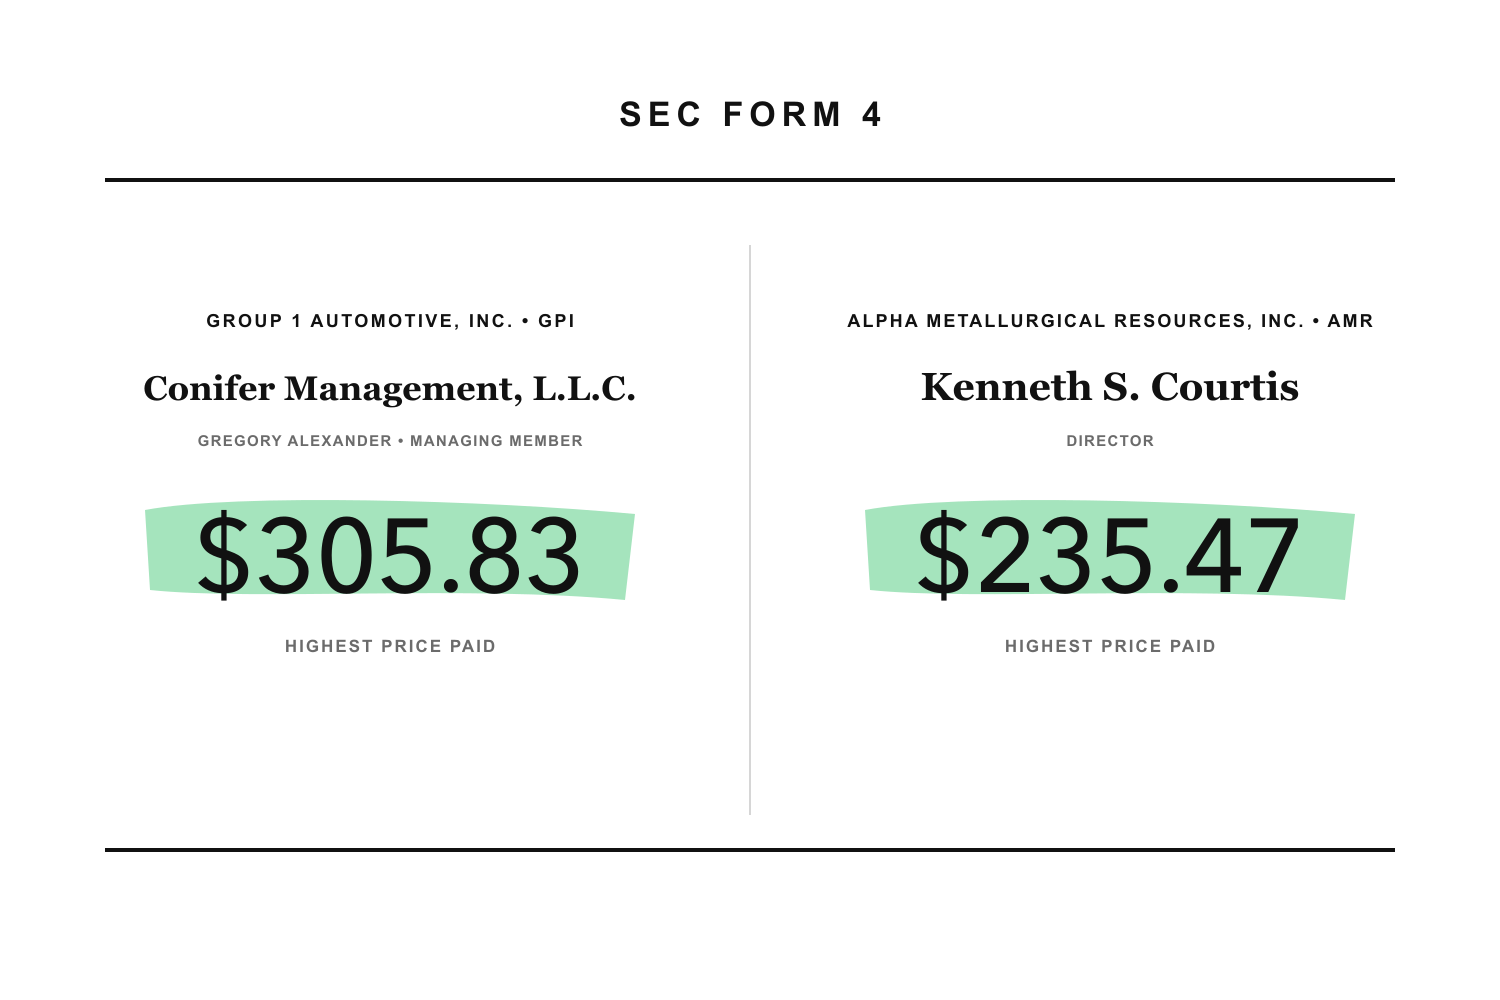
Alpha Metallurgical Resources director Ken Courtis bought $10.5 million above $190 after a blackout lifted, while Conifer’s 12.7% Group 1…
Robinhood’s long-term value rests on retaining customer assets and becoming a primary financial platform beyond trading.
 Thomas Veth 2 clicks
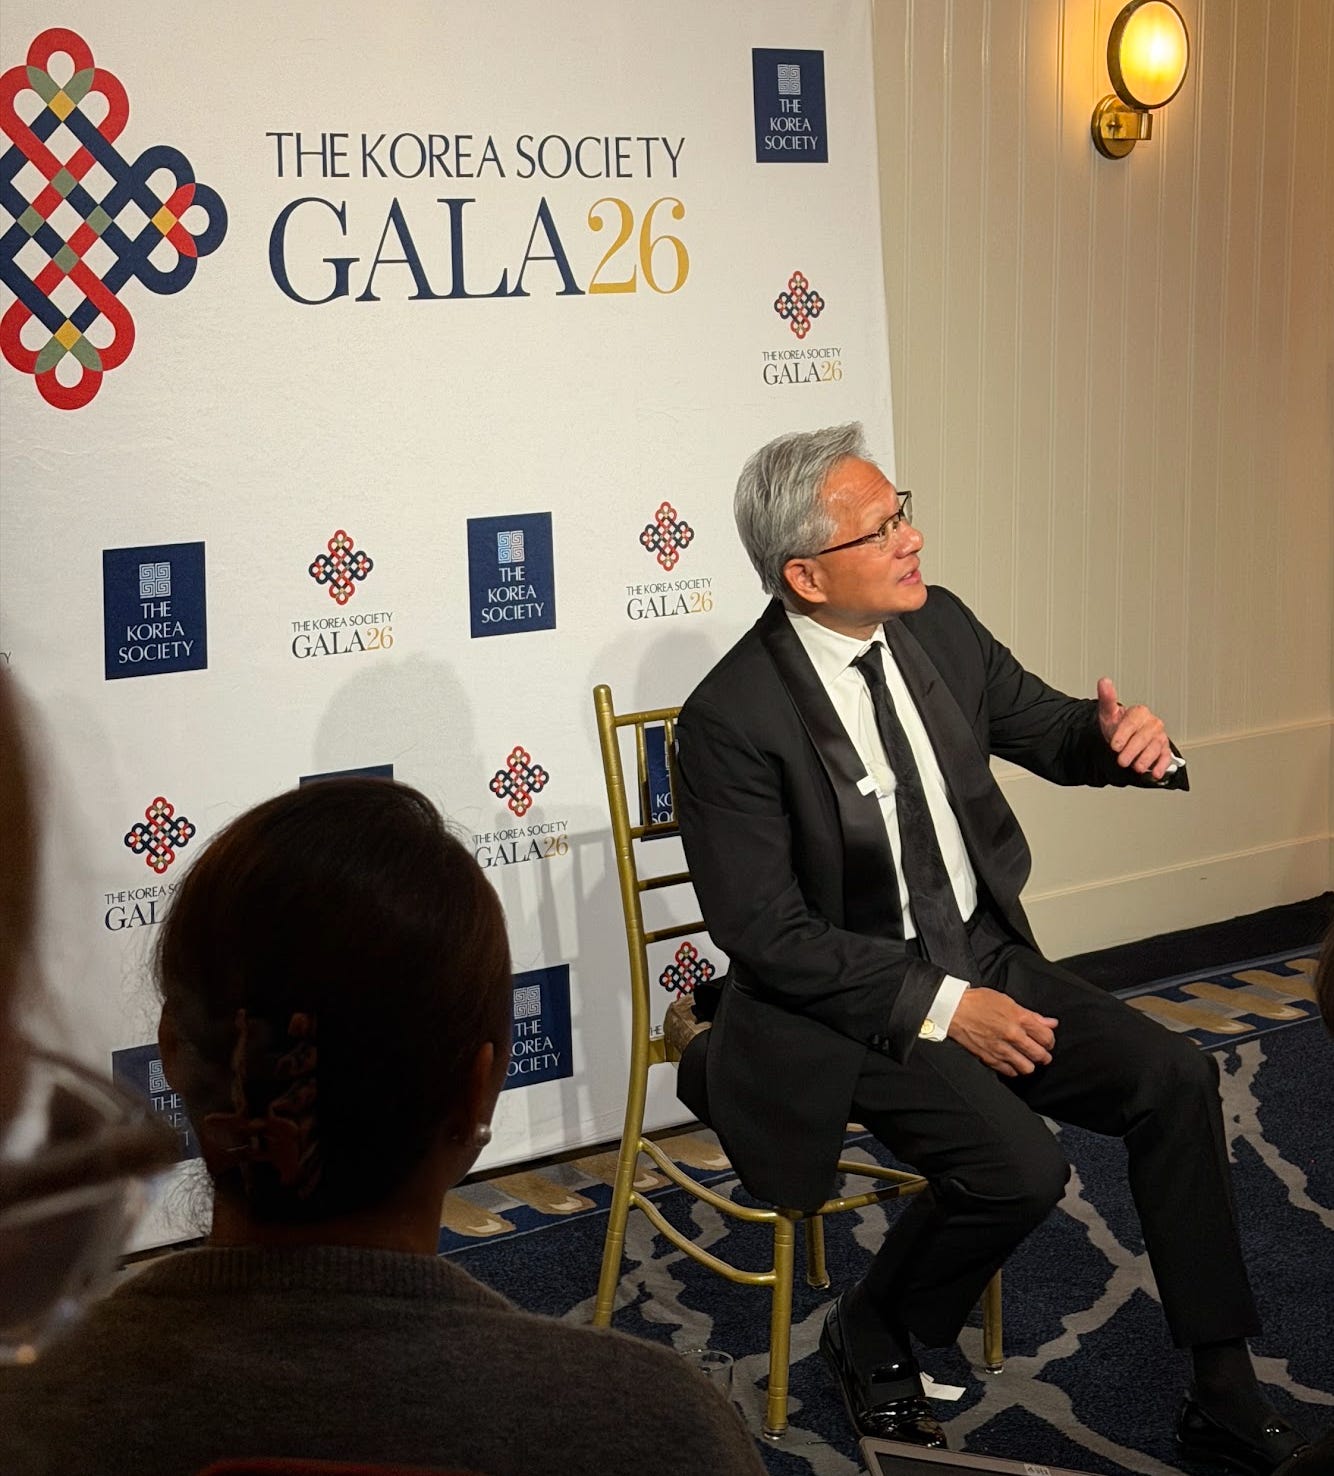
Nvidia CEO Jensen Huang says the company will buy back hundreds of billions of dollars of stock in coming years.
Pfizer’s new products and $9.7 billion cost-cut plan target earnings support through COVID normalization and patent expiries, alongside a…
 Value Capital Research 1 click
Cisco’s Sam Badri says roughly 90% of AI users remain at basic prompting, with few advancing to skills files or AI agents.

Zscaler posted 25% Q4 revenue growth to $898.2 million and a 24.3% operating margin, but guided FY27 growth down to 16.6%-17.5% as free…
Nvidia expanded its buyback authorization and launched an AI security initiative as Jensen Huang urged investors to buy more chips and…
Meta’s Muse AI compiled dossiers on vulnerable Facebook and Instagram users, bypassing safeguards with minor prompt changes.
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Atlas Diary
 Bay Area Ideas
 Benjamin C. Barry
 Bernard Zambonin
 Blake Winiecki
 Capital Connoisseur
 Chetan Woodun
 Crimson And Gold Research
 Cypriot Invests
 Dane Bowler
 Daniel Bell
 Daniel Jones
 Daniel Schönberger
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Gil Rotstein
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Kevin Avroutskii
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player Louis Gerard
 M&M Capital
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Nicolas Bolsinger
 Oakoff Investments
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital Robert J. Lake
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Sanjay Swamy
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 Terry Chrisomalis
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen Tim Travis
 Uttam Dey Value Capital Research
 Vishal Jadaun
 Yiannis Zourmpanos
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.