New Ask Claude or ChatGPT about any stock, using Bullpen. Bullpen in Claude or ChatGPT. 7 days free

Monday, November 16, 2026

Back to the front page

From X

Undiscovered Compounders on X

Tantalus Systems is our favorite long-term bet, and about 10% of our portfolio. $GRID.TO $TGMPF (Our Q3 update and our 144-page deep dive, full valuation model included, below.) The market prices it as if its best product almost didn’t exist. The company’s historical business is selling the communication chips built into new smart meters, to about 350 small US utilities (munis and co-ops). Around C$4.50, the price roughly pays for that business alone. The Gateway comes nearly for free. It plugs in between an old meter and its socket in 30 minutes and makes the meter smart without replacing it. Nobody else sells one today: the giants make their money selling new meters, so they have little interest in it. Why we think the market is wrong: 1. The base doesn’t leave. Only 1 utility has left Tantalus in 11+ years. It wins about 20 new ones a year, and already 19 in the first 9 months of 2026. 2. The Gateway is bought in steps, and each step multiplies the boxes sold to the same utility: - The network: 1 Gateway per 100-150 meters - Power quality at the feeder: 9 per feeder - Power quality at the transformer: 1 per 7-10 homes - Behind the meter (water heaters, thermostats, batteries): 1 per home From the feeder to the transformer, the TAM goes from about 170k boxes to 1.2M. Tantalus has delivered 10.8k so far. 3. Each box is worth more. Tantalus gets about $550 per Gateway, vs $100 per meter it equips with its Edge chip. Then $11/year of licensing vs $4. 4. Step 2 is an easy sell on price. Watching an average feeder (about 560 meters) takes 9 Gateways, about $5k. Replacing those meters with new smart meters costs about $140k. (It’s a bit more complicated in practice. The deep dive has the details.) 5. Adoption is speeding up. 92 utilities have ordered the Gateway (77 a quarter ago), and 53 are past the pilot (vs 37). None of the 40 finished evaluations ended in a technical rejection. 6. Tantalus now reads the data for utilities that can’t hire engineers anymore. At Bolivar (Tennessee), about 500 Gateways caught 1k+ momentary outages per meter in 9 months. The utility had no idea: it had paid for the data and nobody was reading it. That’s how Tantalus plans to sell step 2. 7. The balance sheet buys time: about $18M of net cash. And 10M of the 45M meters at munis and co-ops still have to go smart. Q3 looked bad: revenue flat YoY at $14.3M. Aclara, a meter maker that builds Tantalus’s chips into its meters, shipped no meters in September for lack of a component, and some utilities pushed deliveries back for lack of budget. No customer lost, no cancellation. The revenue moved to the next quarters, and ARR grew 14% YoY to $15.4M. Valuation (10-year model, 3 scenarios, exit on EV/Sales): - Weighted value: C$10.68 in 2031 and C$24.53 in 2036, i.e. 2.4x and 5.5x from C$4.50. - Bear case: C$3.16 in 2031 (-30%). - Cash stays on the balance sheet: no buybacks, no acquisitions. What would break the thesis on its own: - A serious Gateway incident in the field. Utilities are very conservative, and they talk to each other. - Power quality never sells at scale, and the Gateway stays stuck on step 1. What we’re watching: the first named utility that adds Gateways for power quality, beyond the ones running its network. The rest of Q3 is in the update. The other risks, the other opportunities and every valuation assumption are in the deep dive. Both are below or in our bio:

Fajasy on X

QXO's $QXO Q3 10-Q lists 635.2M potential shares beyond its 1.04B shares outstanding, and 383M of them are in the money at $12.58/share. In my June 7 deep dive, I noted that none of $QXO's convertible preferred shows up in its diluted share count while it reports losses. All 383M come from the $1B investment CEO Brad Jacobs' firm led in June 2024: → Convertible preferred: 219.0M shares at $4.566. → Warrants: 219.0M shares, half at $4.566, a quarter at $6.849, and a quarter at $13.698 (out of the money). The Series C preferred converts into another 129.0M shares at $23.25, out of the money for now. $QXO sold the Series C to a fund managed by Apollo $APO and other investors to help pay for lumber distributor Kodiak and insulation installer TopBuild. By my math, $QXO has ~1.46B diluted shares at $12.58/share, not 1.04B. So its equity is worth ~$18.4B, not the ~$13.1B market cap on 1.04B shares. Add the $3.0B Series C and ~$8.45B of net debt, and its EV is ~$29.9B, ~17x the ~$1.75B of consensus adjusted EBITDA Jacobs used as $QXO's starting point on the Q3 call. Net debt of ~$8.45B lands within the $7-9B I expected in my deep dive, but it's ~4.8x the $1.75B, not the 3.3-4.3x I estimated on $2.1B. Interest (including a one-time $15M fee on an unused bridge loan) and preferred dividends took $229M in Q3, 41% of $QXO's $557M of adjusted EBITDA. Q3 operating cash flow was only ~$1M, down from $213M in Q3 2025. Operating cash flow was -$145M through September, including $332M the 10-Q says went into seasonal working capital, mostly inventory and receivables. Jacobs also said on the Q3 call that the $4B of adjusted EBITDA $QXO is targeting for 2030 assumes all free cash flow until then goes to paying down debt. Spending the same free cash flow on small acquisitions could lift 2030 adjusted EBITDA to ~$5.5B instead, he said. Neither path includes the $500M buyback $QXO authorized on November 12. $QXO also said CFO Ihsan Essaid will move to vice chairman in January to oversee M&A and capital raising, and Dev Ahuja, CFO of aluminum maker Novelis since 2016, will take his place. Two numbers in the FY2026 10-K will show whether $QXO is paying down debt: 1) Operating cash flow: Positive for the year, after $145M went out through September. 2) Net debt: Below the ~$8.45B as of September 30. P.S. The ~1.46B counts the in-the-money preferred and warrants (the warrants net of their exercise price), the mandatory convertible preferred (which converts into common by May 15, 2028), stock awards, and 42.0M pre-funded warrants that cost $0.00001/share to exercise.

003100.KQ: grain share 25% to 38%

Sun Kwang (003100.KQ) raised grain market share from 25% to 38% as its founding family transferred 24% of the company to holding companies…

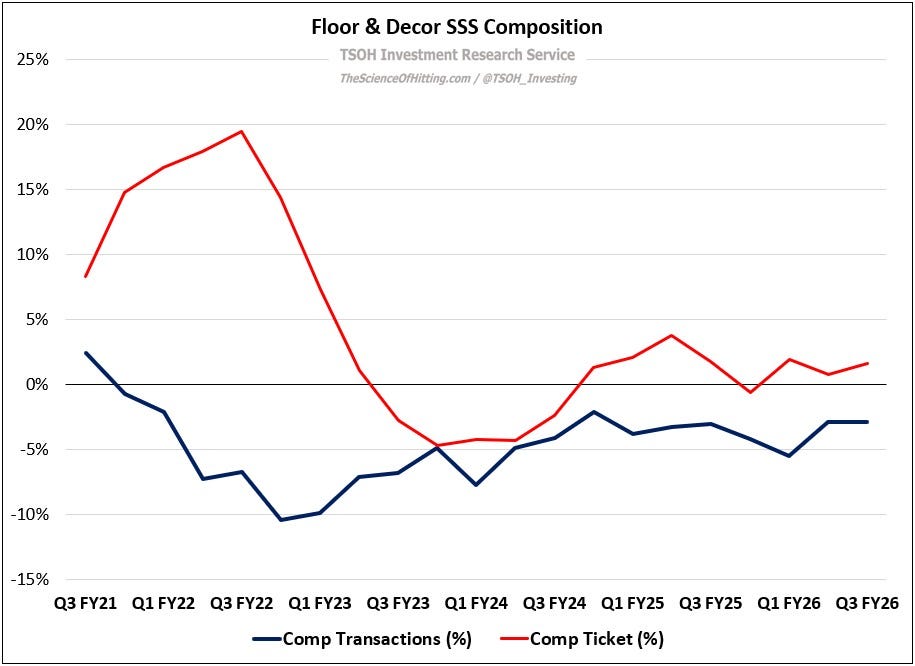
Floor & Decor: Still Waiting

Floor & Decor has logged 20 straight quarters of comp transaction declines, with Q3 quarter-to-date same-store sales down about 3.8% as…

WDC · long

Western Digital CORP

Western Digital, a hard-disk manufacturer, is pitched as a long after significant share-price moves deter investors.

Is The Bond Market Running On Empty?

U.S. Treasury yields are testing credit and equity markets, while the discussion also targets recent changes at Glass House (GLAS).

Reddit: DCF Valuation

Reddit’s DCF values shares at $225, driven by international ARPU expansion from $2.2 to $8.3 by 2035 and 38% operating margins.

Publications we follow

Every publication on this site, hand-picked.

130 publications

Newsletters 110

X accounts we follow

Every account on this site, hand-picked.

91 accounts

Investor letters we follow

376 firms

Sectors

Ordered by how often our editor reaches for them.