TSOH Weekly Roundup (11/13/2026)
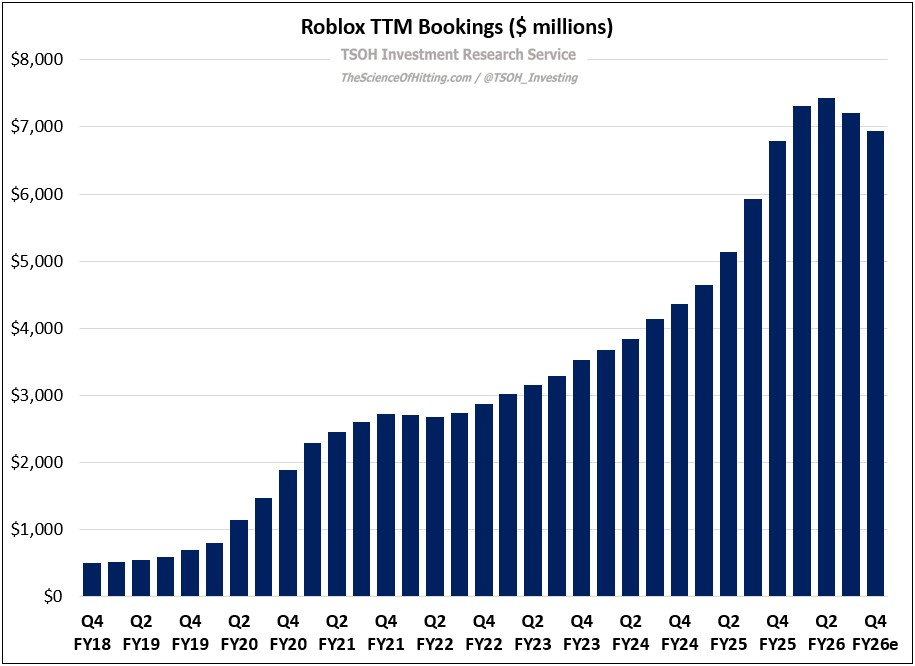
Tripadvisor’s CEO and CFO will depart after weak Q3 results, while Roblox’s CEO discusses AI and Berkshire repurchases $9.6 billion of stock.
Tripadvisor’s CEO and CFO will depart after weak Q3 results, while Roblox’s CEO discusses AI and Berkshire repurchases $9.6 billion of stock.

On $FLNC departures 😵
Sprouts Farmers Market is rated a buy at $50 after a 40% decline, contingent on maintaining store economics as same-store sales and margins…
 Louis Liu, Esq
Alternative asset managers earn durable fees on committed capital, but 2026 losses followed retail-credit redemptions, lender-fraud…
 Atlas Diary
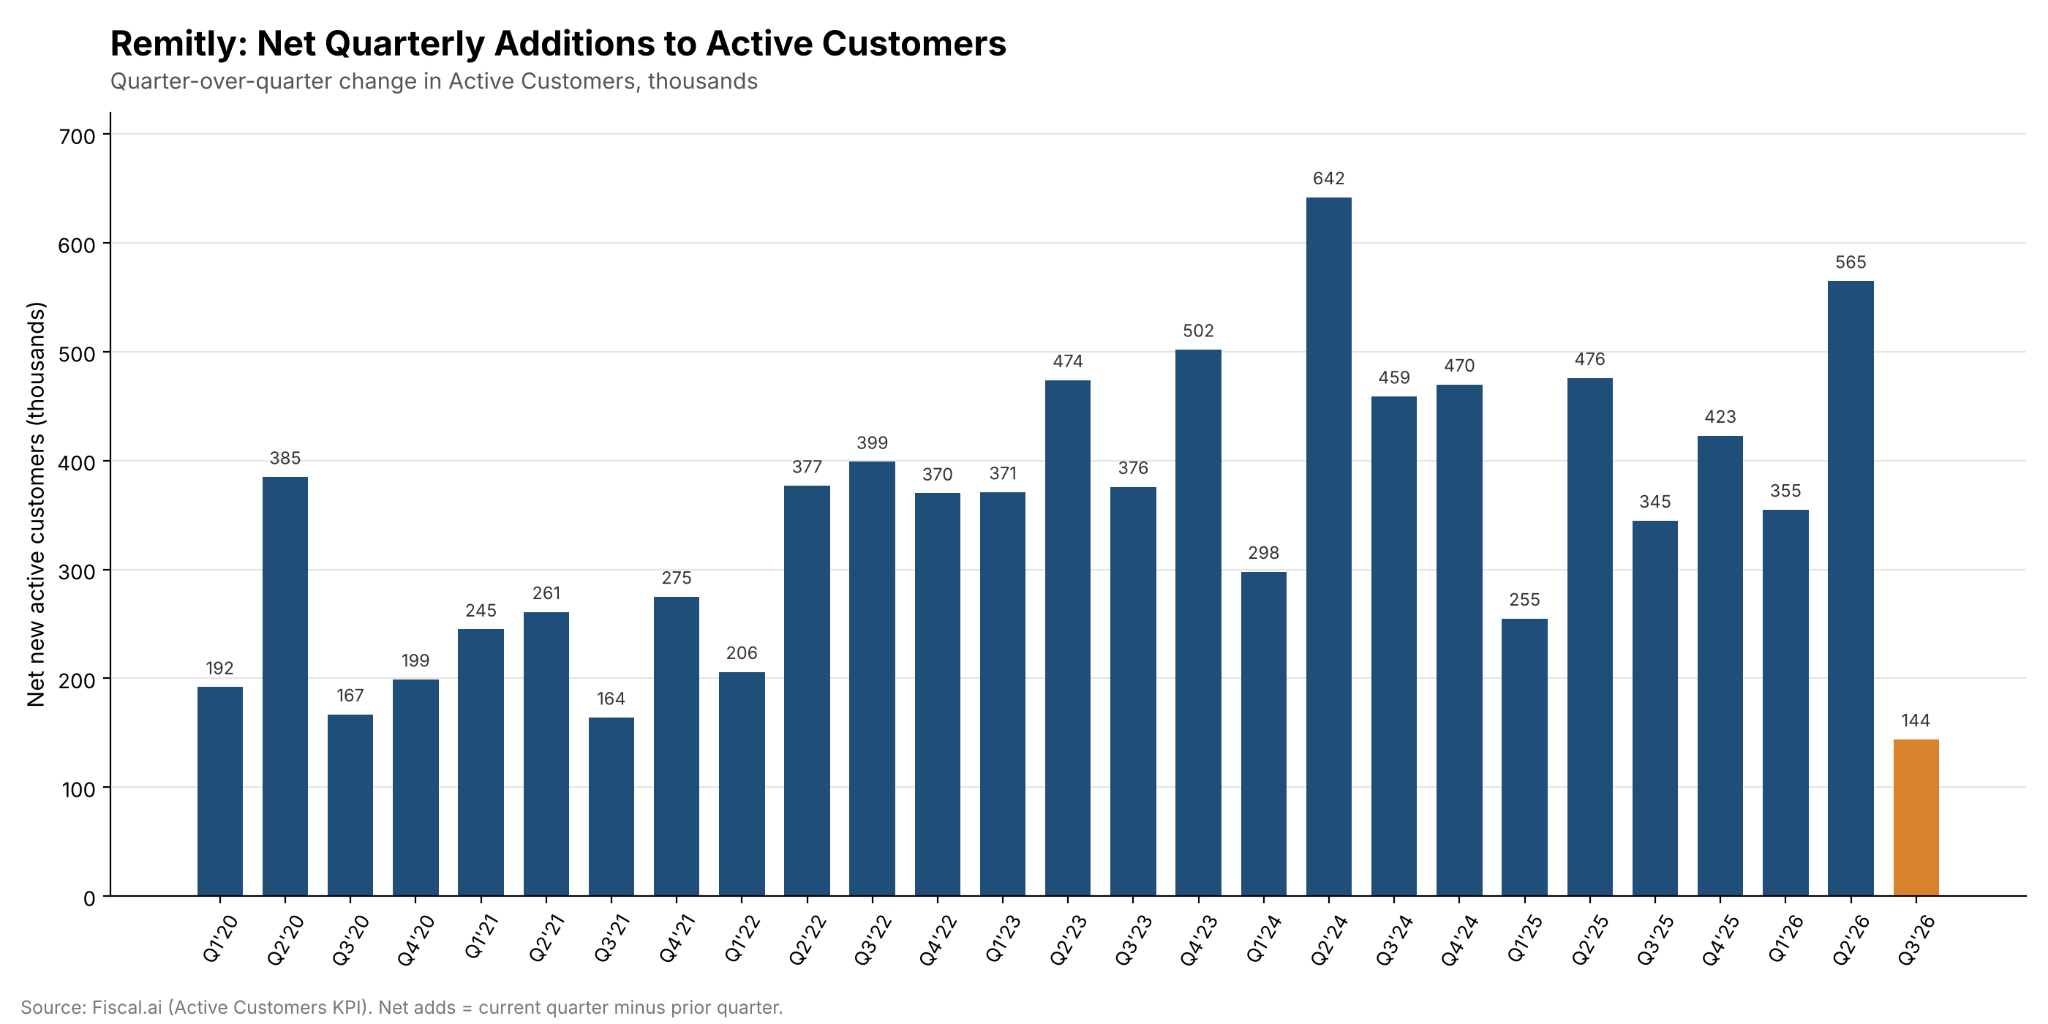
Remitly’s Q3 keeps its remittance growth thesis intact as spending cards, memberships and credit products target $1 billion in annual…
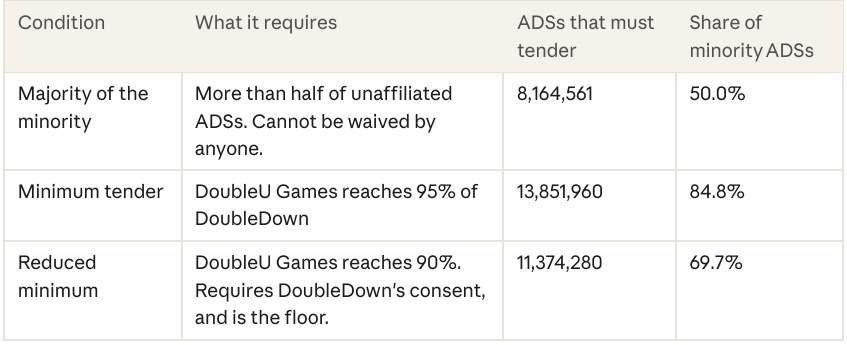
DoubleU Games raised its all-cash tender offer for DoubleDown Interactive minority holders to $16.25 per ADS from $11.25 after net cash…
Bloom Energy’s fuel cells offer data centers grid independence as Q3 operating income rose 518% on 138% revenue growth.
 Ignacio Planas Gonzalez 2 clicks
QXO's Q3 sales rose 79% to $4.9 billion after TopBuild and Kodiak acquisitions, while acquisition debt lifted interest expense to $163…
Nvidia CEO Colette Kress signals a pullback from the financial schemes pursued under Jensen Huang.
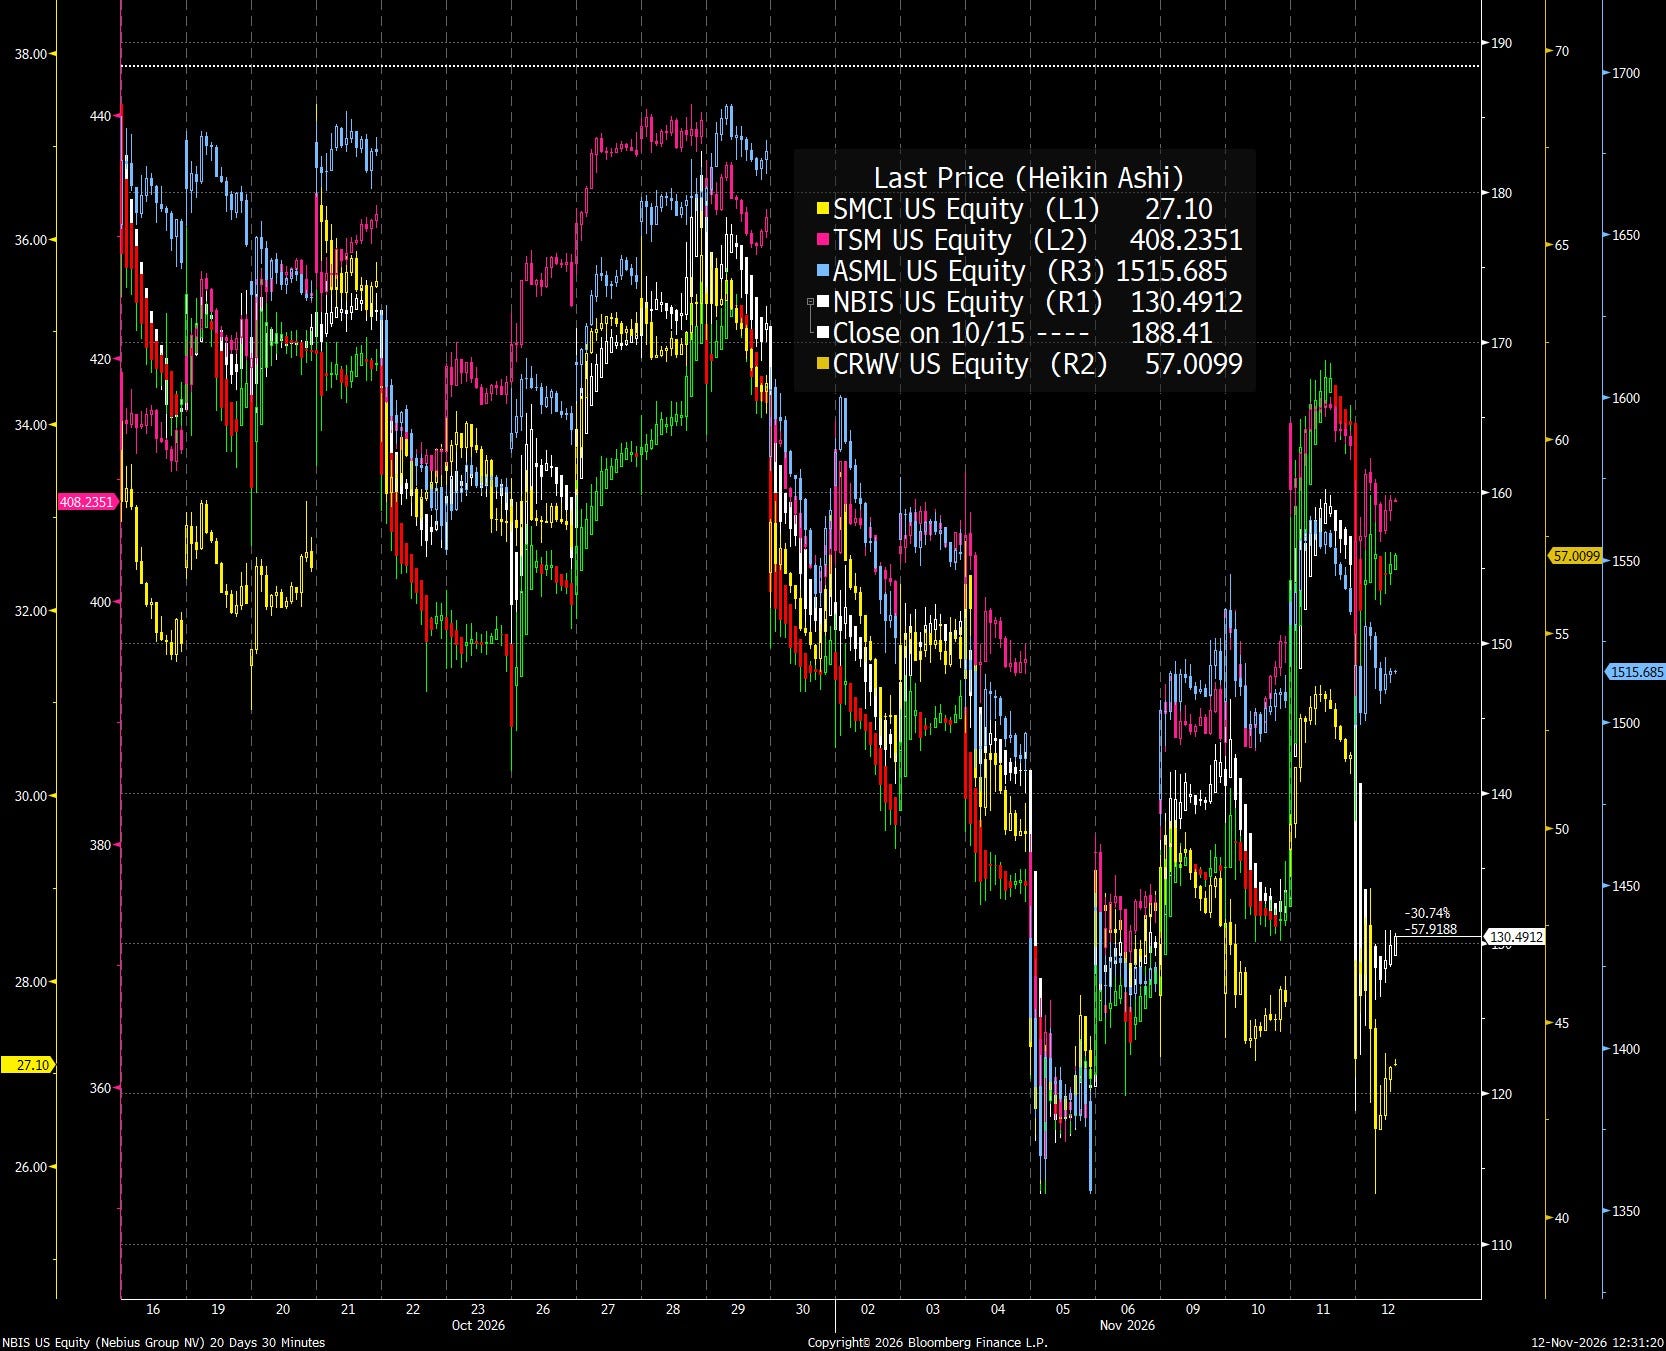
NVIDIA faces DOJ antitrust probes alongside inquiries into Megaspeed and Super Micro, after charges over $2.5 billion of GPUs allegedly…
Coursera trades at roughly $150 million enterprise value after Pale Fire Capital took 14.7%, with cash and Treasuries covering 83% of its…
UniQure’s Huntington’s disease BLA has a May 1, 2027 priority-review date, with an FDA advisory committee expected in late first quarter.
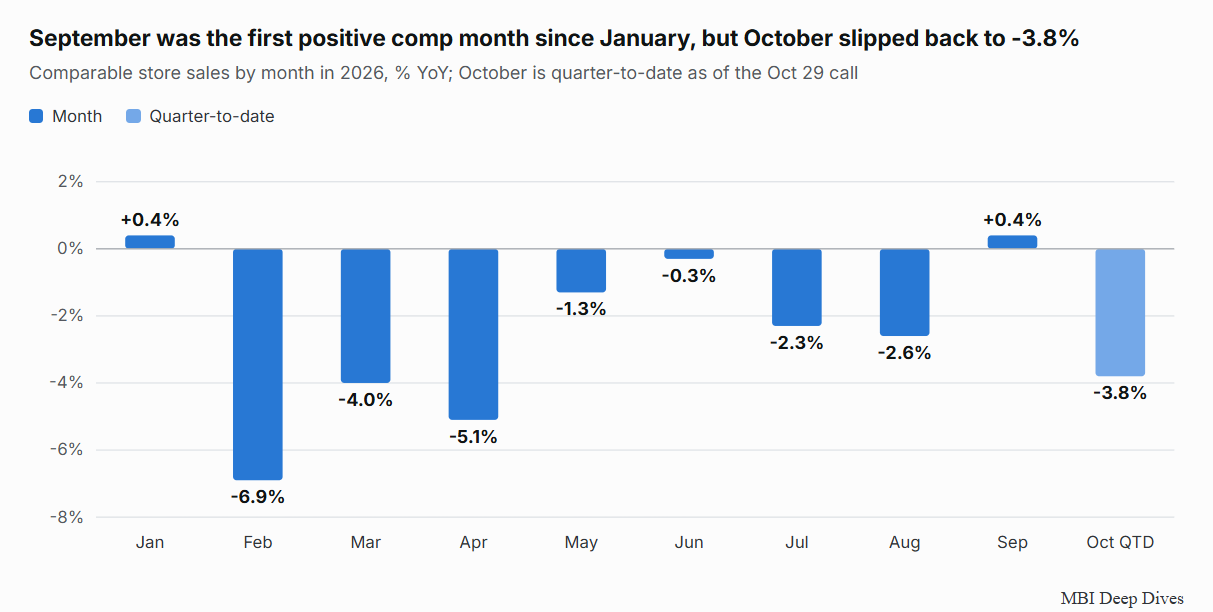
Floor & Decor cut its 2026 outlook again, with EBITDA guidance falling to $535-550 million and 2027 openings slowing to 10-15 as housing…
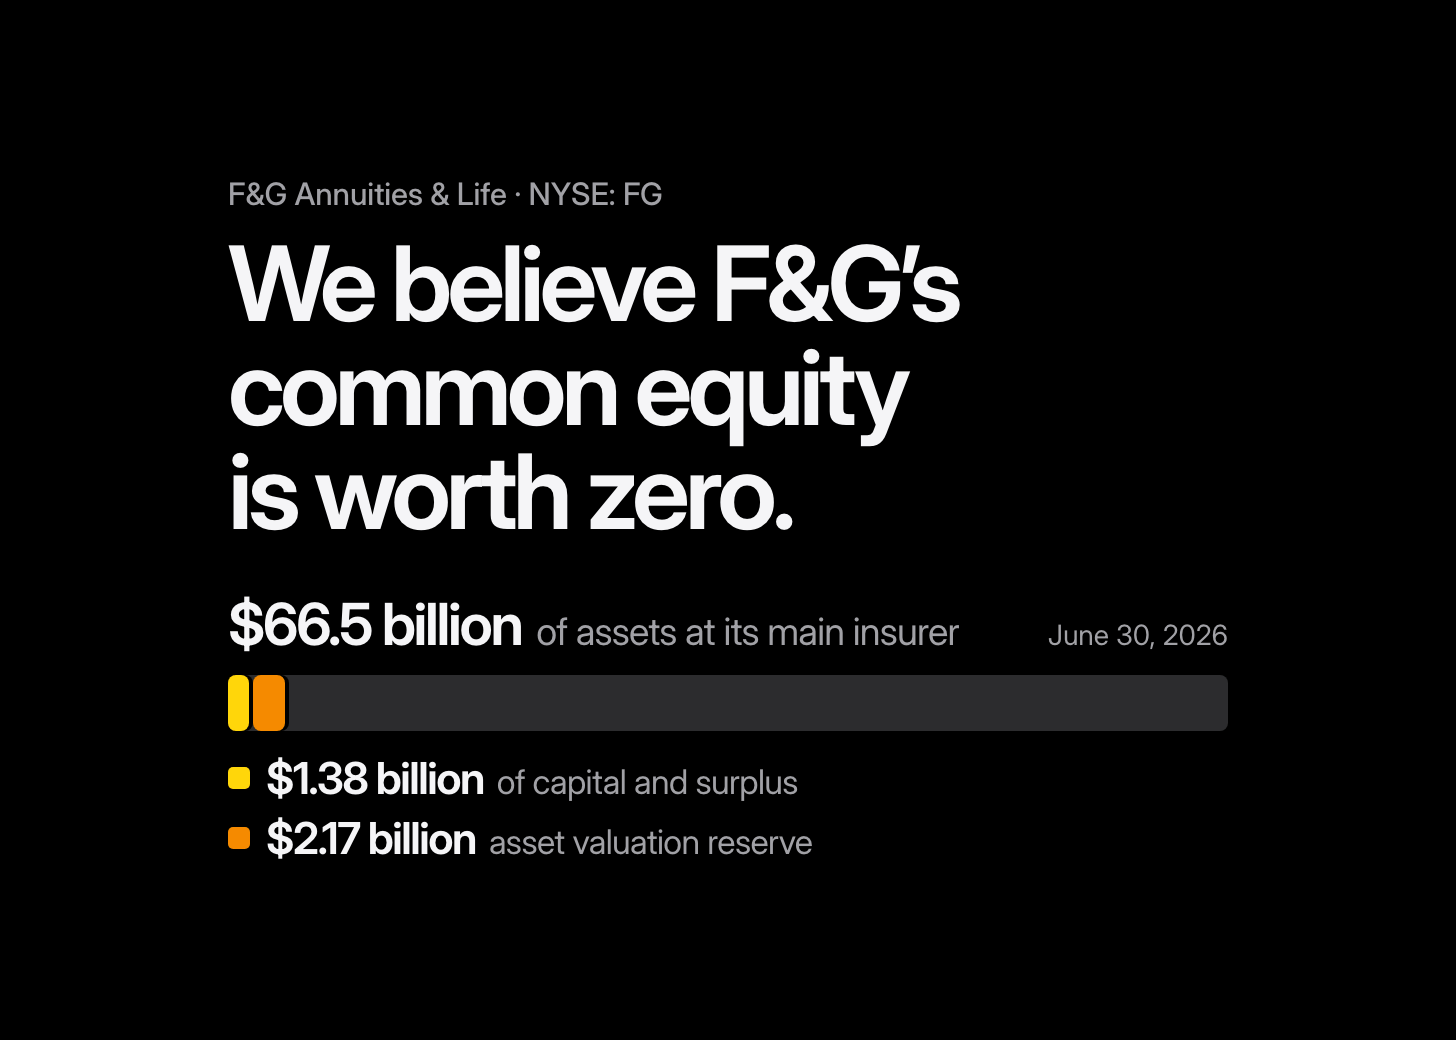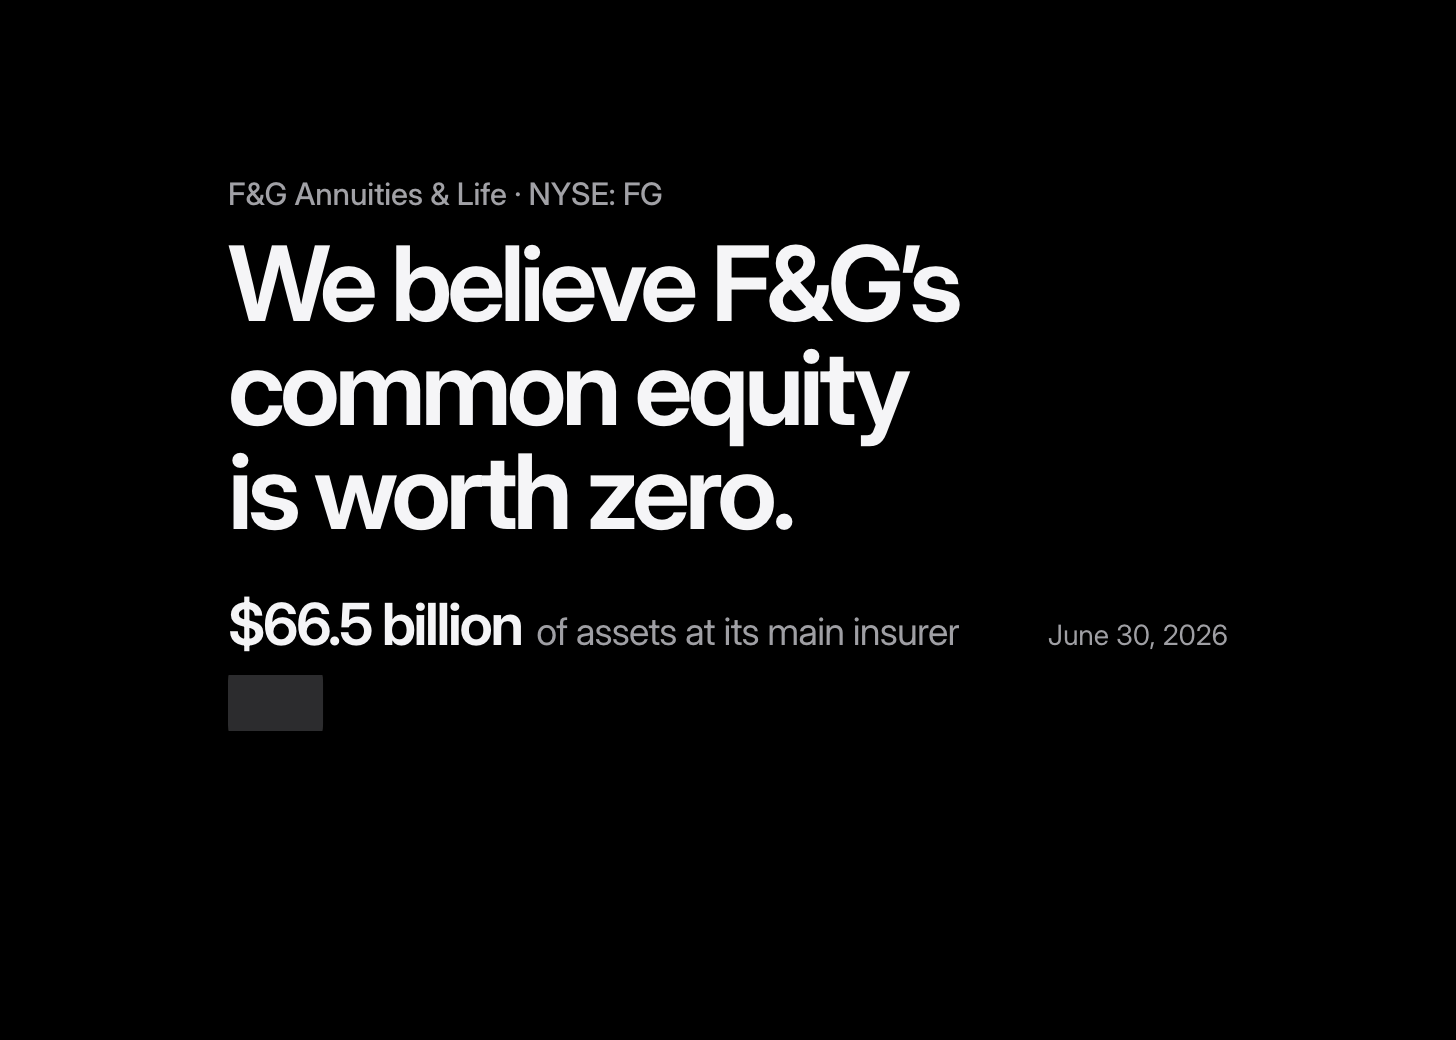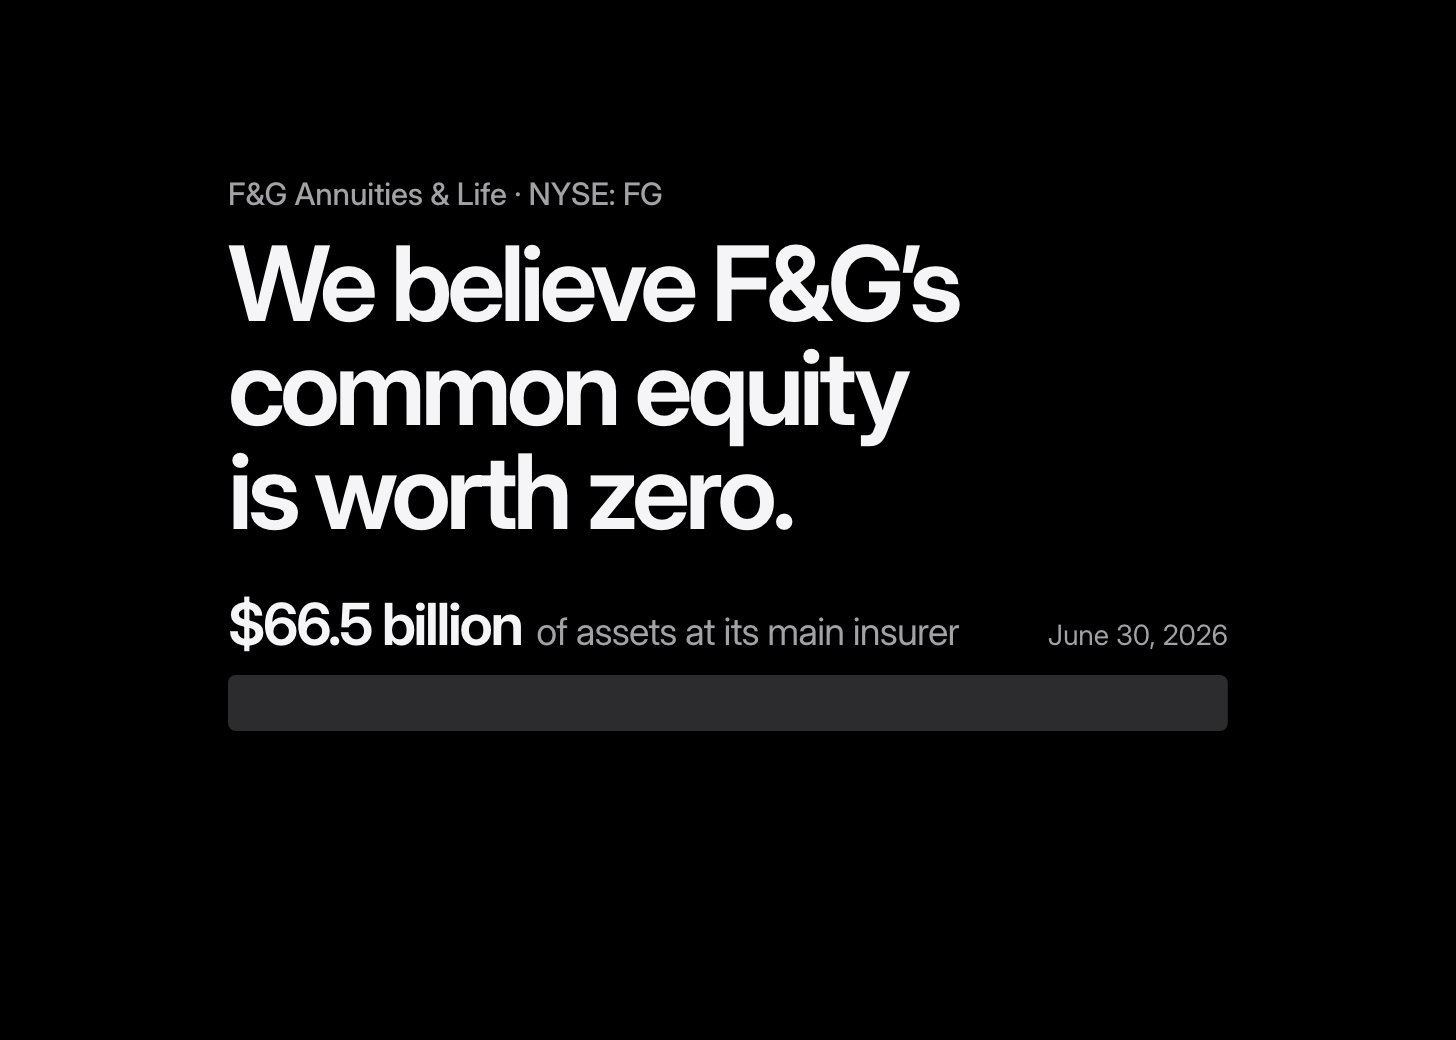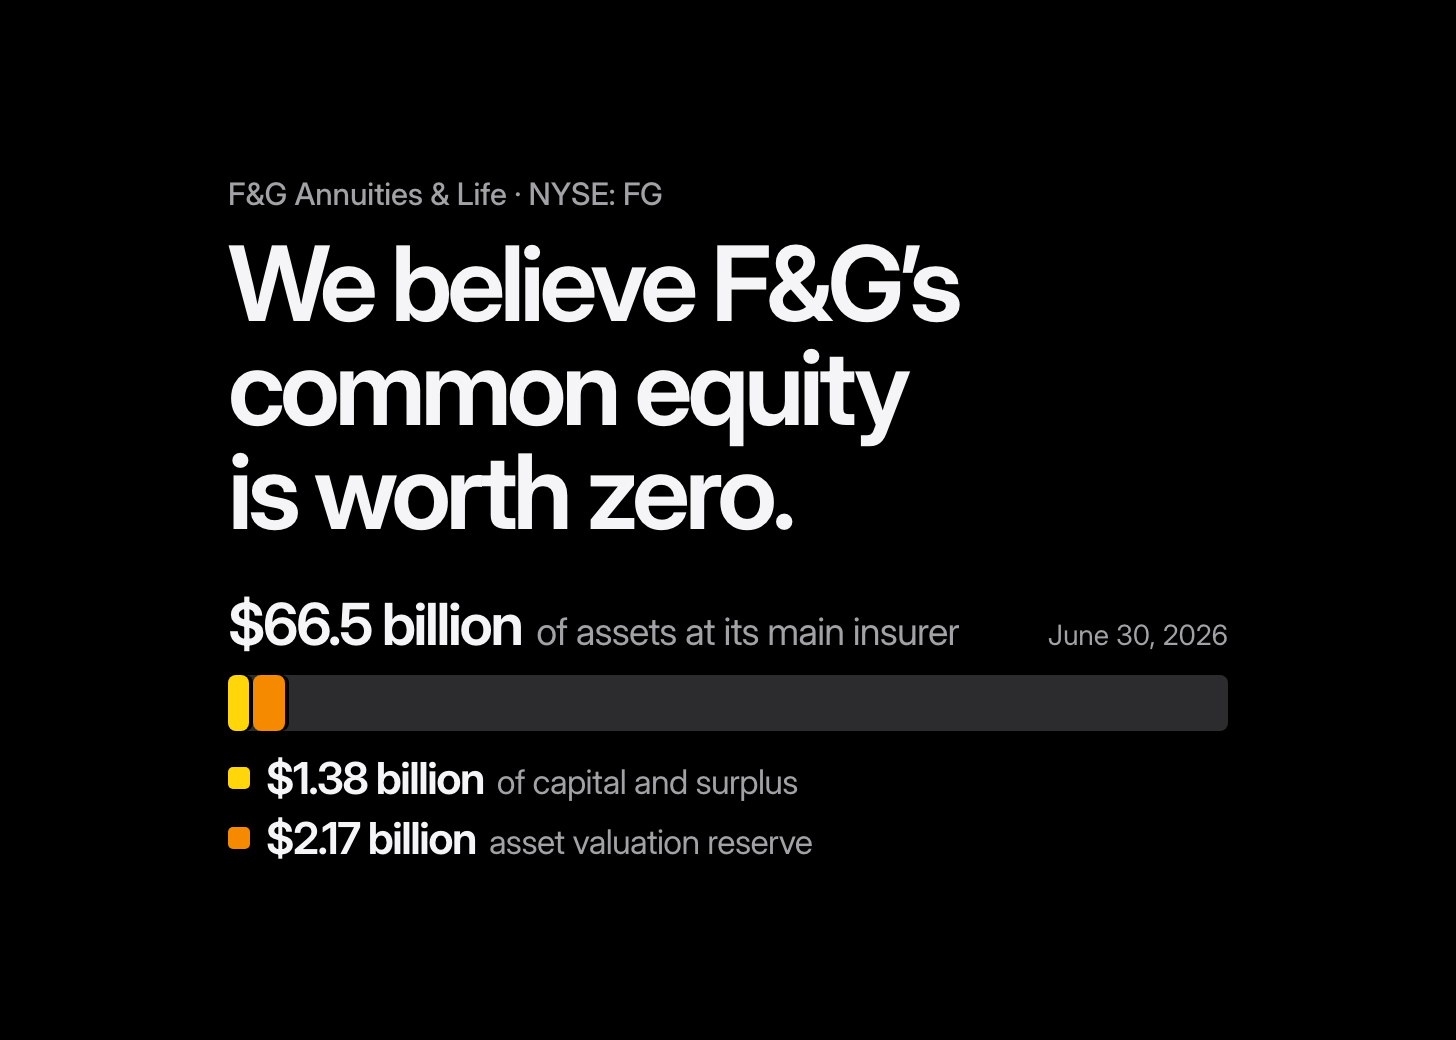
F&G’s main insurer held $66.5 billion of assets against $1.38 billion of statutory capital, while private credit, reinsurance dependence…
AutoNation’s new CEO Mike Manley brings Jeep and Fiat Chrysler experience after the dealer chain cycled through three leaders in 30 months.
Quanta Services' backlog rose 63% year over year to $64 billion as shares fell 30%, with AI and power-infrastructure demand driving revenue…
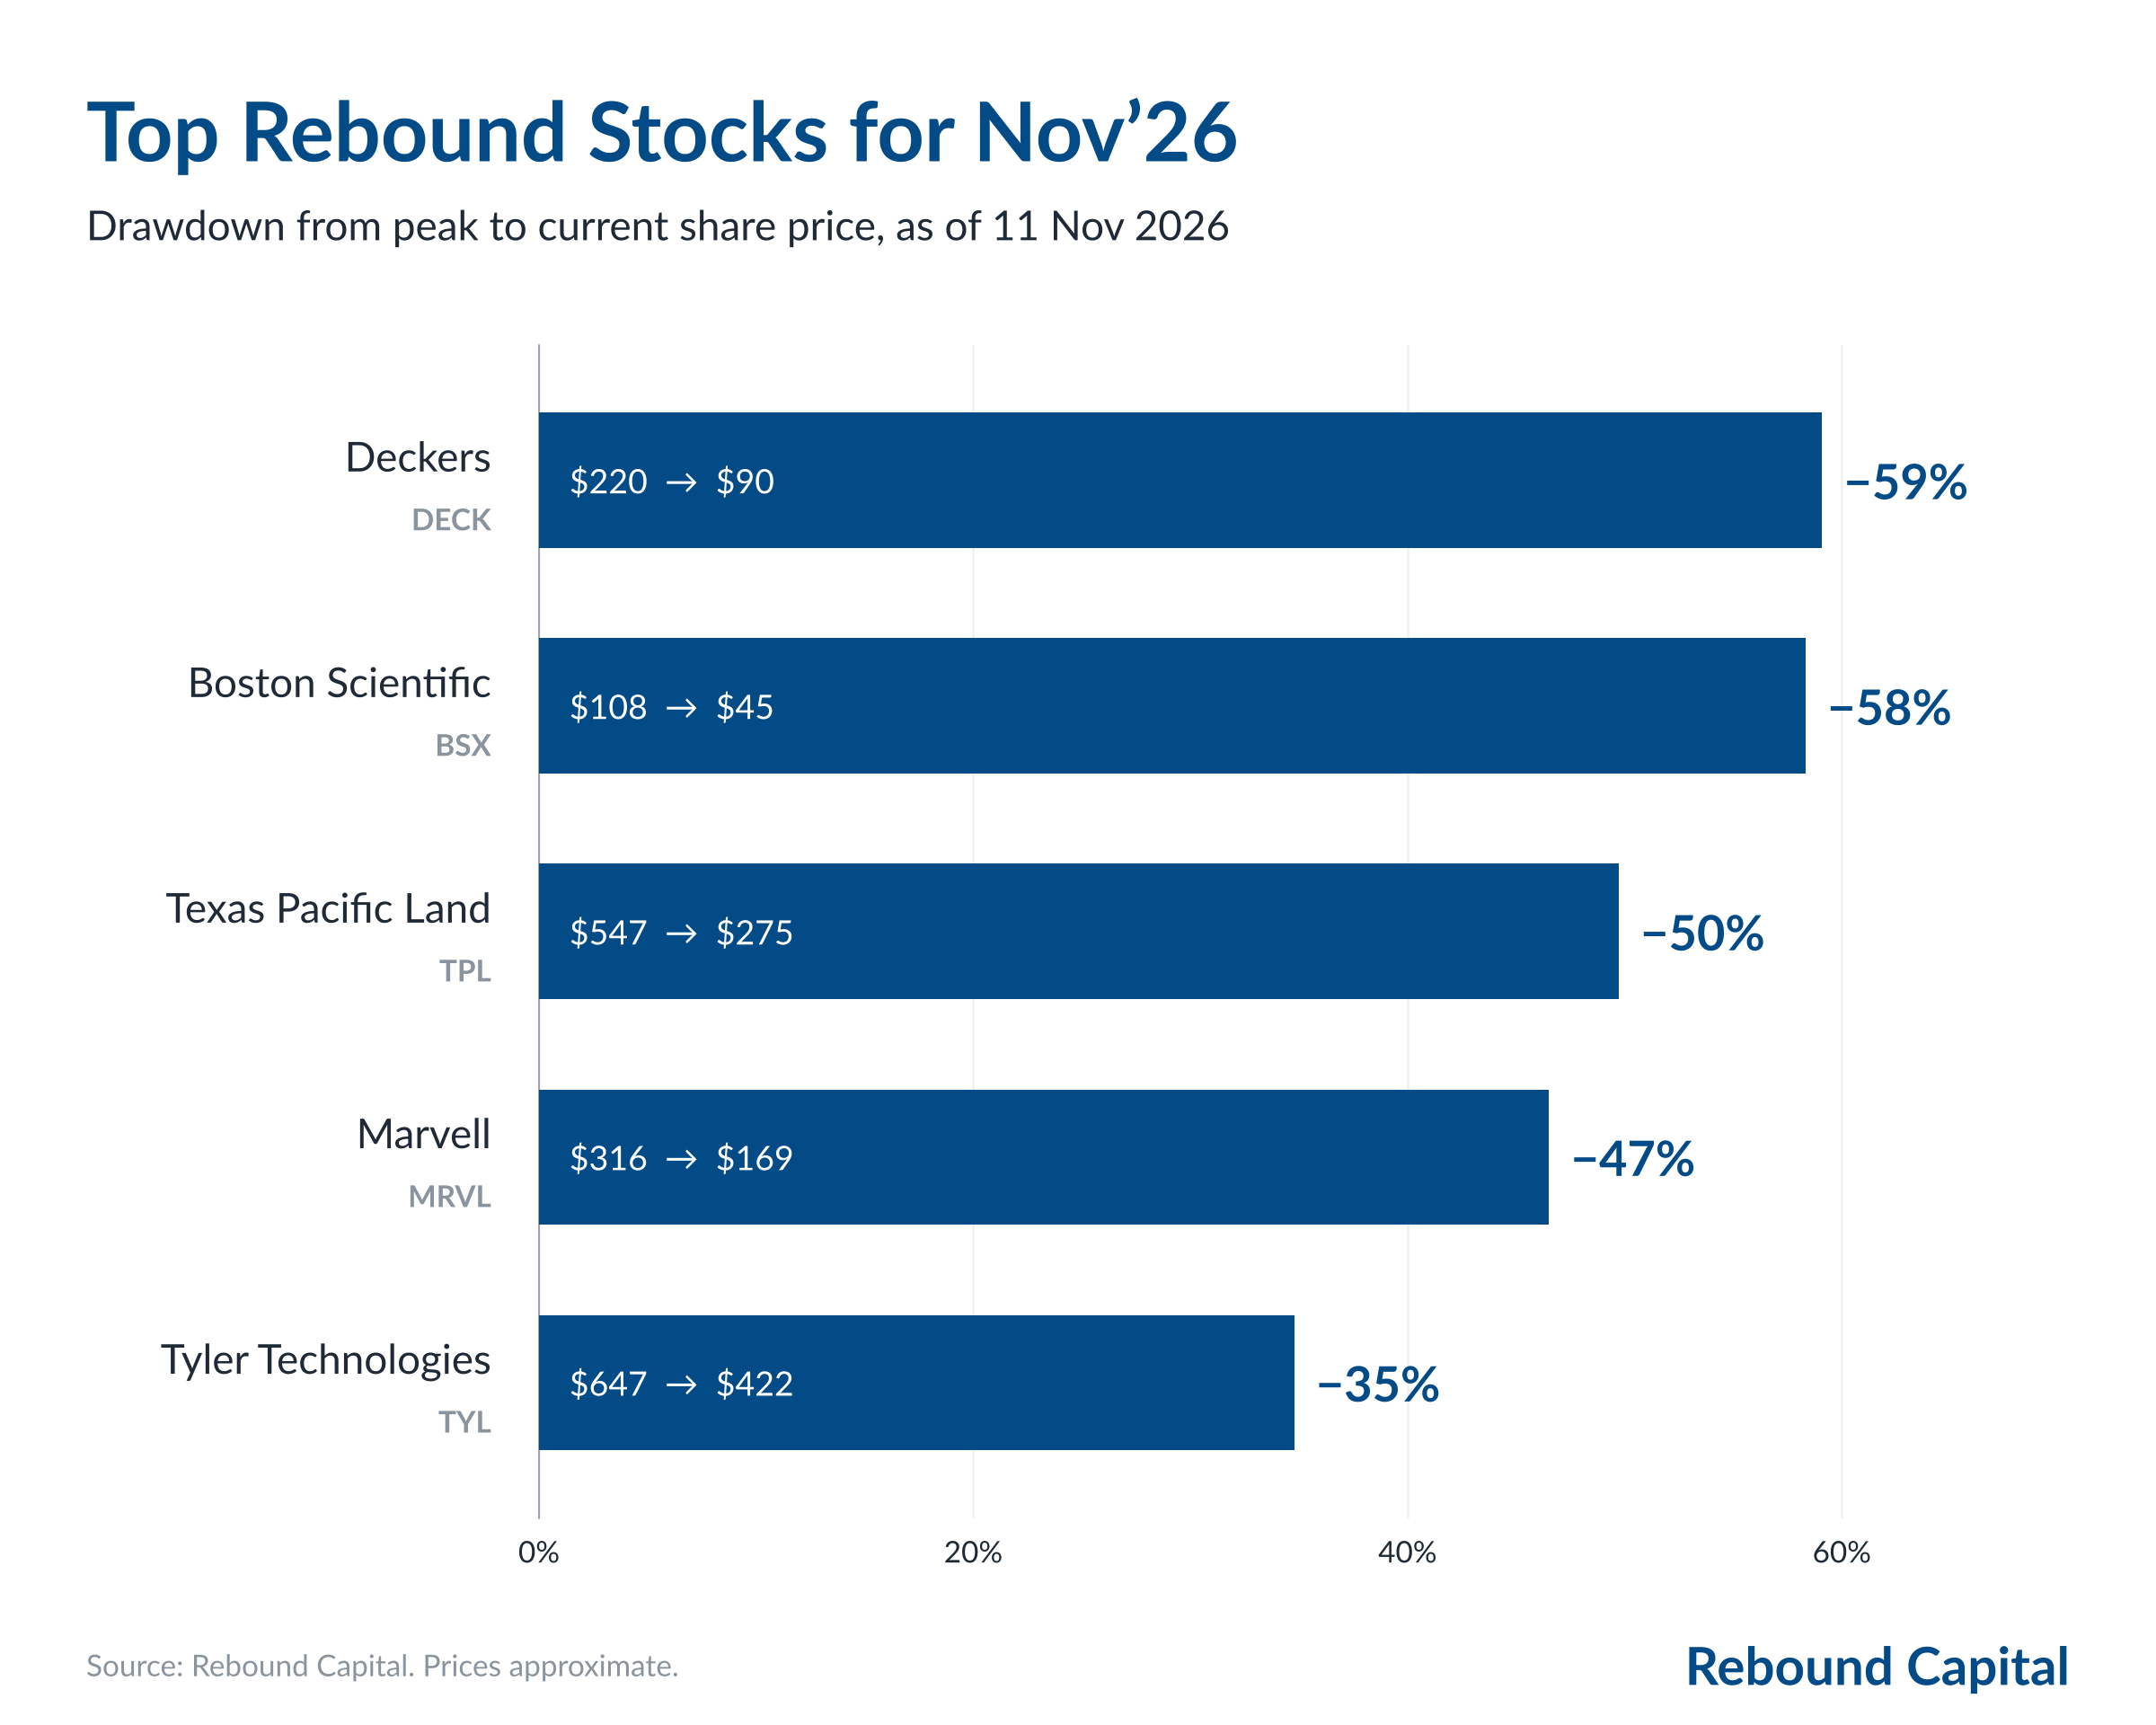
Texas Pacific Land's 50% selloff reflects faded data-center expectations, while its Permian royalty business generated $498 million of 2025…
International Seaways reported $291.4 million of Q3 adjusted net income and has 53% of Q4 booked at strong spot rates, supporting projected…
 Kevin Avroutskii 3 clicks
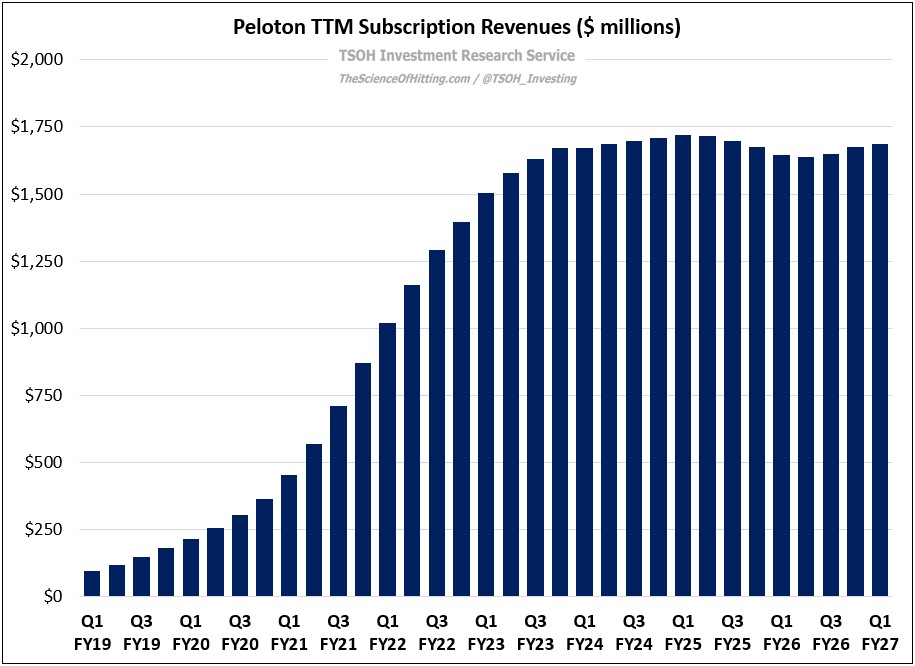
Peloton’s connected-fitness subscribers fell 9% year over year to 2.475 million, with another high-single-digit holiday decline forecast as…
DHT Holdings earned $1.68 per share in Q3 and projects Q4 EPS of $4.25, supporting a single-quarter dividend above 20% at projected spot…
 Melissa Tucker 4 clicks
 MONOY · long
MonotaRO, traded as MONOY in the U.S. and 3064 in Japan, is a Japanese MRO distributor recommended as a long.
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research Atlas Diary
 Bay Area Ideas
 Benjamin C. Barry
 Bernard Zambonin
 Blake Winiecki
 Capital Connoisseur
 Chetan Woodun
 Crimson And Gold Research
 Cypriot Invests
 Dane Bowler
 Daniel Bell
 Daniel Schönberger
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Gil Rotstein
 Given Mahlangu
 Henrik Alex
 High Alpha Professor Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian Kevin Avroutskii
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Louis Gerard
 Marc Gerstein Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Nicolas Bolsinger
 Oakoff Investments
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Sanjay Swamy
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.