Wednesday, November 4, 2026

Back to the front page

From X

@aleabitoreddit 1 click

Serenity on X

$COHR earnings transcript TLDR: Q: On $LITE + $MRVL merger. A. Customers will prefer an independent optical supplier without competitive conflicts (opportunity for other merchant laser suppliers) Q: Loop Capital asked about 2028 laser industry oversupply. A: No oversupply risk by 2028. Coherent’s entire current internal InP production is consumed by its own products while its expanding capacity. Q: On Chinese laser competition for CPO UHP lasers A: “We really only have one competitor” (hinting at $LITE). Q: On financing concerns for capacity expansion during this market scare A: Customer LTAs have prepayments, which are used for product capacity orders 2027 completely sold out, LTAs extend to 2030, customers placing orders into 2028. Q: On laser technology for CPO scale up from Bernstein, whether it’s VCSELs or CW lasers. A: CW for CPO scale out and scale up for 2026-2027. 2029-2030 sees scale in and chip to chip using micro-VCSELs, and 2028 opportunities for NPO scale up. So technology of choice is CW for CPO. - Coherent is seeing pricing power and raising margin targets, supporting view optical players get additional leverage for margin expansion - Massive new $20B 5Y LTA, anchored by UHP CW lasers, with other optical products mixed in - demand comes from growth in DC and conversion of copper interconnects to optics. The latter is bandwidth requirements, independent of DC growth. slower compute growth can coexist with sharply rising optical content per system TLDR: - nothing quite showing optical demand like $20B in LTAs anchored by high power lasers from 1 customer alone (not your frontier labs type commitments) - no industry wide laser oversupply risk by 2028 for InP lasers/EML - financing funded by revenue from LTAs and purchase orders. - doesn’t see Chinese competition for high end lasers, commentary casts doubts over China capability + capacity expansion claims - CW lasers weapon of choice for CPO, blended margins going up for optical players - optics more isolated in the event of a DC slowdown Quite wild to see fundamentals of optical players improve so much, while overall valuations crash.
@DeepSailCapital 1 click

Deep Sail Capital on X

Just a bit of my thoughts on the AI datacenter buildout: Texas has already stopped new data centers back in August, and that's the most important fact the market missed today. 1/ Abbott paused it in August. ERCOT stopped energizing new data centers of 75 MW or more and shelved a ~200 GW study batch. TCEQ stopped issuing permits. Hinojosa's moratorium will keep the existing pause in place on New permits instead of lifting it. She also said it targets new permits, not projects already under construction. So that just means next project goes to a friendly locale, not Texas. 2/ Ohio was already moving. DeWine froze the data center sales-tax exemption for new projects back in June. Acton's conditional moratorium is a pay your own power costs, use union labor, build on brownfields. That's a cost hit, not a ban outright. 3/ Congress can't ban anything. The Sanders/AOC moratorium bill would face a Trump veto through Jan 2029. 4/ What's already built or nearly built keeps going: • Stargate Abilene: 4 of 8 buildings live, the rest due this month • Fairwater Atlanta: ~636 MW running • Rainier Indiana: ~1 GW running • Hyperion Louisiana: not in play at all About 56.7 GW is under construction nationally and largely outside the pledges. 5/ Demand didn't change this week: • $ANET Q3 revenue $3.66b, +58.5% y/y, $360m above guide • $CLS guiding 2027 to $40b, roughly double 2026 • $MOD data center sales +95%, record backlog, a $4b+ deal for 2027–29 • Hyperscalers are on pace for $803b–$828b of 2026 capex and they're guiding 2027 higher 6/ The market half-figured it out. Texas-heavy builders and power names fell 7–23% ($HUT -23%, $VST -15%). Suppliers with national backlogs barely moved ($ANET -0.4%, $NVDA -0.8%). $NUAI is a zero now for sure. 7/ Where it's real: new 2027–28 capacity in TX/OH/GA gets slower and pricier, so it will shift to different locations. New projects go to friendly locales, TX/OH/GA lose out. 8/ AI component suppliers are still maxed out for the next few years, that demand doesn’t change, just where they ship it to does. 9/ Neoclouds still suck. Ain’t nothing gonna change that.
@DeepSailCapital 1 click

Deep Sail Capital on X

Just a bit of my thoughts on AI: Texas has already stopped new data centers back in August, and that's the most important fact the market missed today. 1/ Abbott paused it in August. ERCOT stopped energizing new data centers of 75 MW or more and shelved a ~200 GW study batch. TCEQ stopped issuing permits. Hinojosa's moratorium will keep the existing pause in place on New permits instead of lifting it. She also said it targets new permits, not projects already under construction. So that just means next project goes to a friendly locale, not Texas. 2/ Ohio was already moving. DeWine froze the data center sales-tax exemption for new projects back in June. Acton's conditional moratorium is a pay your own power costs, use union labor, build on brownfields. That's a cost hit, not a ban outright. 3/ Congress can't ban anything. The Sanders/AOC moratorium bill would face a Trump veto through Jan 2029. 4/ What's already built or nearly built keeps going: • Stargate Abilene: 4 of 8 buildings live, the rest due this month • Fairwater Atlanta: ~636 MW running • Rainier Indiana: ~1 GW running • Hyperion Louisiana: not in play at all About 56.7 GW is under construction nationally and largely outside the pledges. 5/ Demand didn't change this week: • $ANET Q3 revenue $3.66b, +58.5% y/y, $360m above guide • $CLS guiding 2027 to $40b, roughly double 2026 • $MOD data center sales +95%, record backlog, a $4b+ deal for 2027–29 • Hyperscalers are on pace for $803b–$828b of 2026 capex and they're guiding 2027 higher 6/ The market half-figured it out. Texas-heavy builders and power names fell 7–23% ($HUT -23%, $VST -15%). Suppliers with national backlogs barely moved ($ANET -0.4%, $NVDA -0.8%). $NUAI is a zero now for sure. 7/ Where it's real: new 2027–28 capacity in TX/OH/GA gets slower and pricier, so it will shift to different locations. New projects go to friendly locales, TX/OH/GA lose out. 8/ AI component suppliers are still maxed out for the next few years, that demand doesn’t change, just where they ship it to does. 9/ Neoclouds still suck. Ain’t nothing gonna change that.
@DeepSailCapital

Deep Sail Capital on X

Just a bit of my thoughts on AI: If AI buildout is really materially slowed down it’s a death sentence to American Economy / our AI pole position in the world. AI datacenter buildout saved us from a recession a few years ago, it is the only thing holding us back from one right now. An extremely bad outcome is China takes the lead in AI, US businesses use said Chinese AI to cut US jobs and the money saved is shipped to China, so we are net negative as a country. Now on to why I don’t think AI build cadence will be materially changed and it’s all posturing / the easy trade for tourists. Texas has already stopped new data centers back in August, and that's the most important fact the market missed today. 1/ Abbott paused it in August. ERCOT stopped energizing new data centers of 75 MW or more and shelved a ~200 GW study batch. TCEQ stopped issuing permits. Hinojosa's moratorium will keep the existing pause in place on New permits instead of lifting it. She also said it targets new permits, not projects already under construction. So that just means next project goes to a friendly locale, not Texas. 2/ Ohio was already moving. DeWine froze the data center sales-tax exemption for new projects back in June. Acton's conditional moratorium is a pay your own power costs, use union labor, build on brownfields. That's a cost hit, not a ban outright. 3/ Congress can't ban anything. The Sanders/AOC moratorium bill would face a Trump veto through Jan 2029. 4/ What's already built or nearly built keeps going: • Stargate Abilene: 4 of 8 buildings live, the rest due this month • Fairwater Atlanta: ~636 MW running • Rainier Indiana: ~1 GW running • Hyperion Louisiana: not in play at all About 56.7 GW is under construction nationally and largely outside the pledges. 5/ Demand didn't change this week: • $ANET Q3 revenue $3.66b, +58.5% y/y, $360m above guide • $CLS guiding 2027 to $40b, roughly double 2026 • $MOD data center sales +95%, record backlog, a $4b+ deal for 2027–29 • Hyperscalers are on pace for $803b–$828b of 2026 capex and they're guiding 2027 higher 6/ The market half-figured it out. Texas-heavy builders and power names fell 7–23% ($HUT -23%, $VST -15%). Suppliers with national backlogs barely moved ($ANET -0.4%, $NVDA -0.8%). $NUAI is a zero now for sure. 7/ Where it's real: new 2027–28 capacity in TX/OH/GA gets slower and pricier, so it will shift to different locations. New projects go to friendly locales, TX/OH/GA lose out. 8/ AI component suppliers are still maxed out for the next few years, that demand doesn’t change, just where they ship it to does. 9/ Neoclouds still suck. Ain’t nothing gonna change that.
@aleabitoreddit

Serenity on X

Cyberoffense/defense is probably going to eat up a TON of compute and end up a continuous compute-intensive arms race. Even $AMZN CEO thinks cybersecurity would take up 20% of tokens consumed for the next year. It's literally a problem of how much you throw at compute for vulnerability discovery + model capability, from of my chats w/ Horizon3. And this is going to become a nation state issue, as seen with the implications already with PHP to vulnerabilities with banks/infrastructure from AI swarms. But people see this and throw money at $CRWD, $NET, and others, which I was saying was a bubble. If it's a compute issue, the economics go to the infra, from neoclouds to $NBIS to networking like $AAOI. We'll likely see swarms go wild from aggressor nation states in the next few years. And any country, whether that's Japan or EU that don't have their own capabilities might suffer severe damage. US spent $11T+ cumulatively (inflation adjusted) on Nuclear weapons and we're like ~$1.8T into the the "cyber-nuclear weapon" equivalent of that And this is not even including the endless other economic implications from AI in other fields from advancing cancer discovery to workforce automation with physical AI. It's hard to measure AI sustainability if $50K in compute spend from a foreign actor can take down $10B of your own infrastructure. AI has become a bipartisan national security issue, and even Democrats would not want China overtake the US in this field.

Coupang: 3Q26 Business Recap

Coupang’s product-commerce growth rose 9% as data-leak effects fade, while management expects margins to return to pre-incident levels by…

update on Gartner

Gartner’s growth has stalled after federal contract losses and cautious commercial spending, raising questions about its competitive…
Recycle Bin

Used aircraft engines can be repurposed as gas turbines, easing data center power constraints while tightening aviation supply.
TWLO Q3 FY12/26 Earnings Review

Twilio's Q3 revenue rose 20% to $1.56 billion, but Q4 organic growth guidance fell to 11% to 12% and RPO declined 28%.
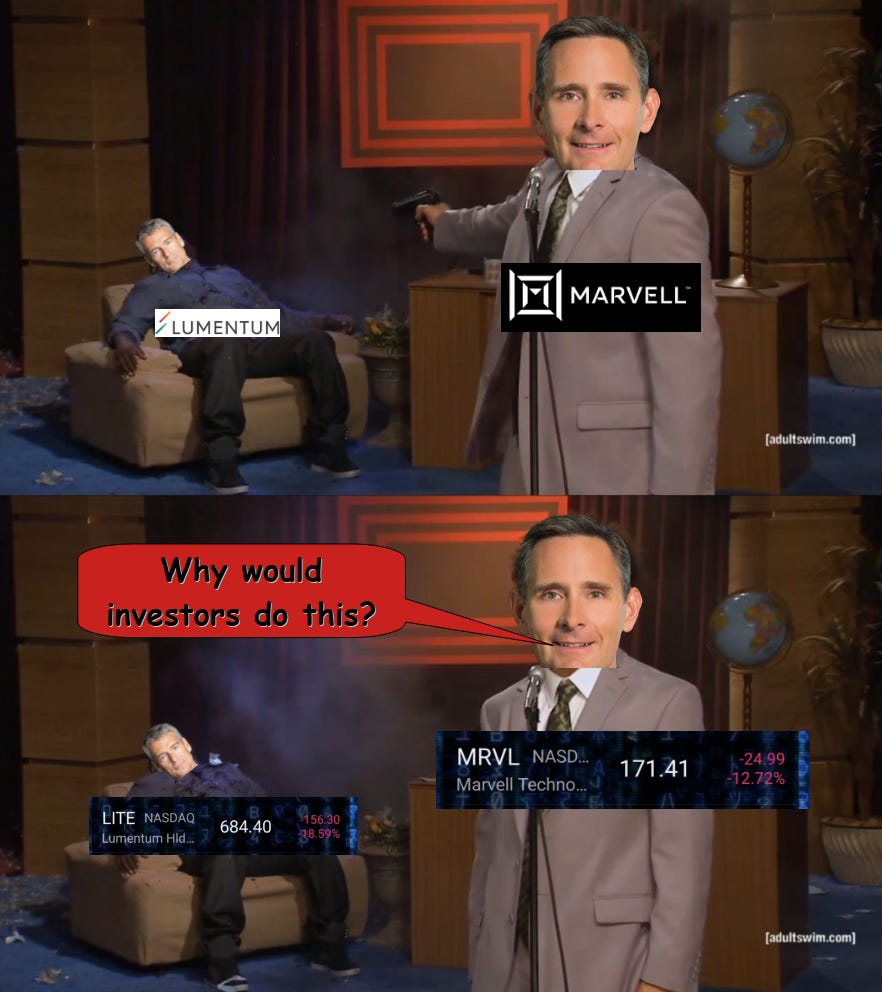
Marvellous Value Destruction

Marvell’s proposed Lumentum deal risks alienating Cloudlight customers and losing engineering talent, despite limited optical integration…
INVH · long

Invitation Homes INC

Invitation Homes owns more than 85,000 homes valued at $43 to $48 per share, versus a roughly $30 share price, with occupancy above 96%.
Power Semiconductors: The Follow-Up

STMicroelectronics, Navitas and Wolfspeed offer contrasting power-semiconductor cases tied to NVIDIA’s 800V AI data-center architecture,…
Copart 4Q26 Business Update

Copart's U.S. insurance volumes fell 7.5% in 4Q26, largely from one customer loss, while international insurance units rose 11.2% and…
Research Roundup Vol. LII

Dell’s AI-server demand and Microchip’s data-center components lead updates on Cirrus Logic and STMicroelectronics, alongside a weekly…
Adobe 3Q26 Update

Adobe’s fiscal 3Q26 revenue grew 13%, while ARR growth slowed to 9.3% excluding Semrush.

Publications we follow

Every publication on this site, hand-picked.

129 publications

Newsletters 109

X accounts we follow

Every account on this site, hand-picked.

91 accounts

Investor letters we follow

359 firms

Sectors

Ordered by how often our editor reaches for them.