SiriusXM: Dirt Cheap, Looming Catalysts, Short Squeeze Candidate
SiriusXM trades at 6.5 times free cash flow, a 15% yield, with high short interest and catalysts that could drive a short squeeze.
SiriusXM trades at 6.5 times free cash flow, a 15% yield, with high short interest and catalysts that could drive a short squeeze.
$NN An investor bought 5,000 Sept $15 option contracts today for $1.40. Assuming shares were $25 post NPRM, these have a 7x return or an implied 15% chance of happening. I think at $1.40, these options were priced far below intrinsic value. I like this trade very much. Very smart
@TreyHenninger $THVB is similar to TRUX. I was taught to be skeptical of the SBA loan sellers. There are a few banks that have maintained decent mortgage origination income.
Cedar Creek Partners Q2 letter released. 12.6% in 1H26 net of fees and expenses. $SODI $EXCE $HRBR $PHIG $ENDI $QUCT $STLE $SLBK $RVRF https://t.co/d794sYsHAT
Hmmm so what happens to China WFE and local semicap? $ACMR https://t.co/zCLlueeF3O
@GalianoTiramani Anyone can get investors with Facebook ads and anything reg b. The jetai SPAC team said the same exact thing as you here $JTAI after they had investors into their SPAC deal from paid ads - they were 99% of the targets https://t.co/w9DtXdT3Po
Newest out. Philip Morris International: Juggernaut $PM $BTI $MO $IMBBY $STG $HAYPP https://t.co/cVKgrcU86T
Dorchester Minerals' 9.5% normalized yield and debt-free royalty model are offset by limited upside at $29.71, as extraordinary…
 Atlas Diary 3 clicks
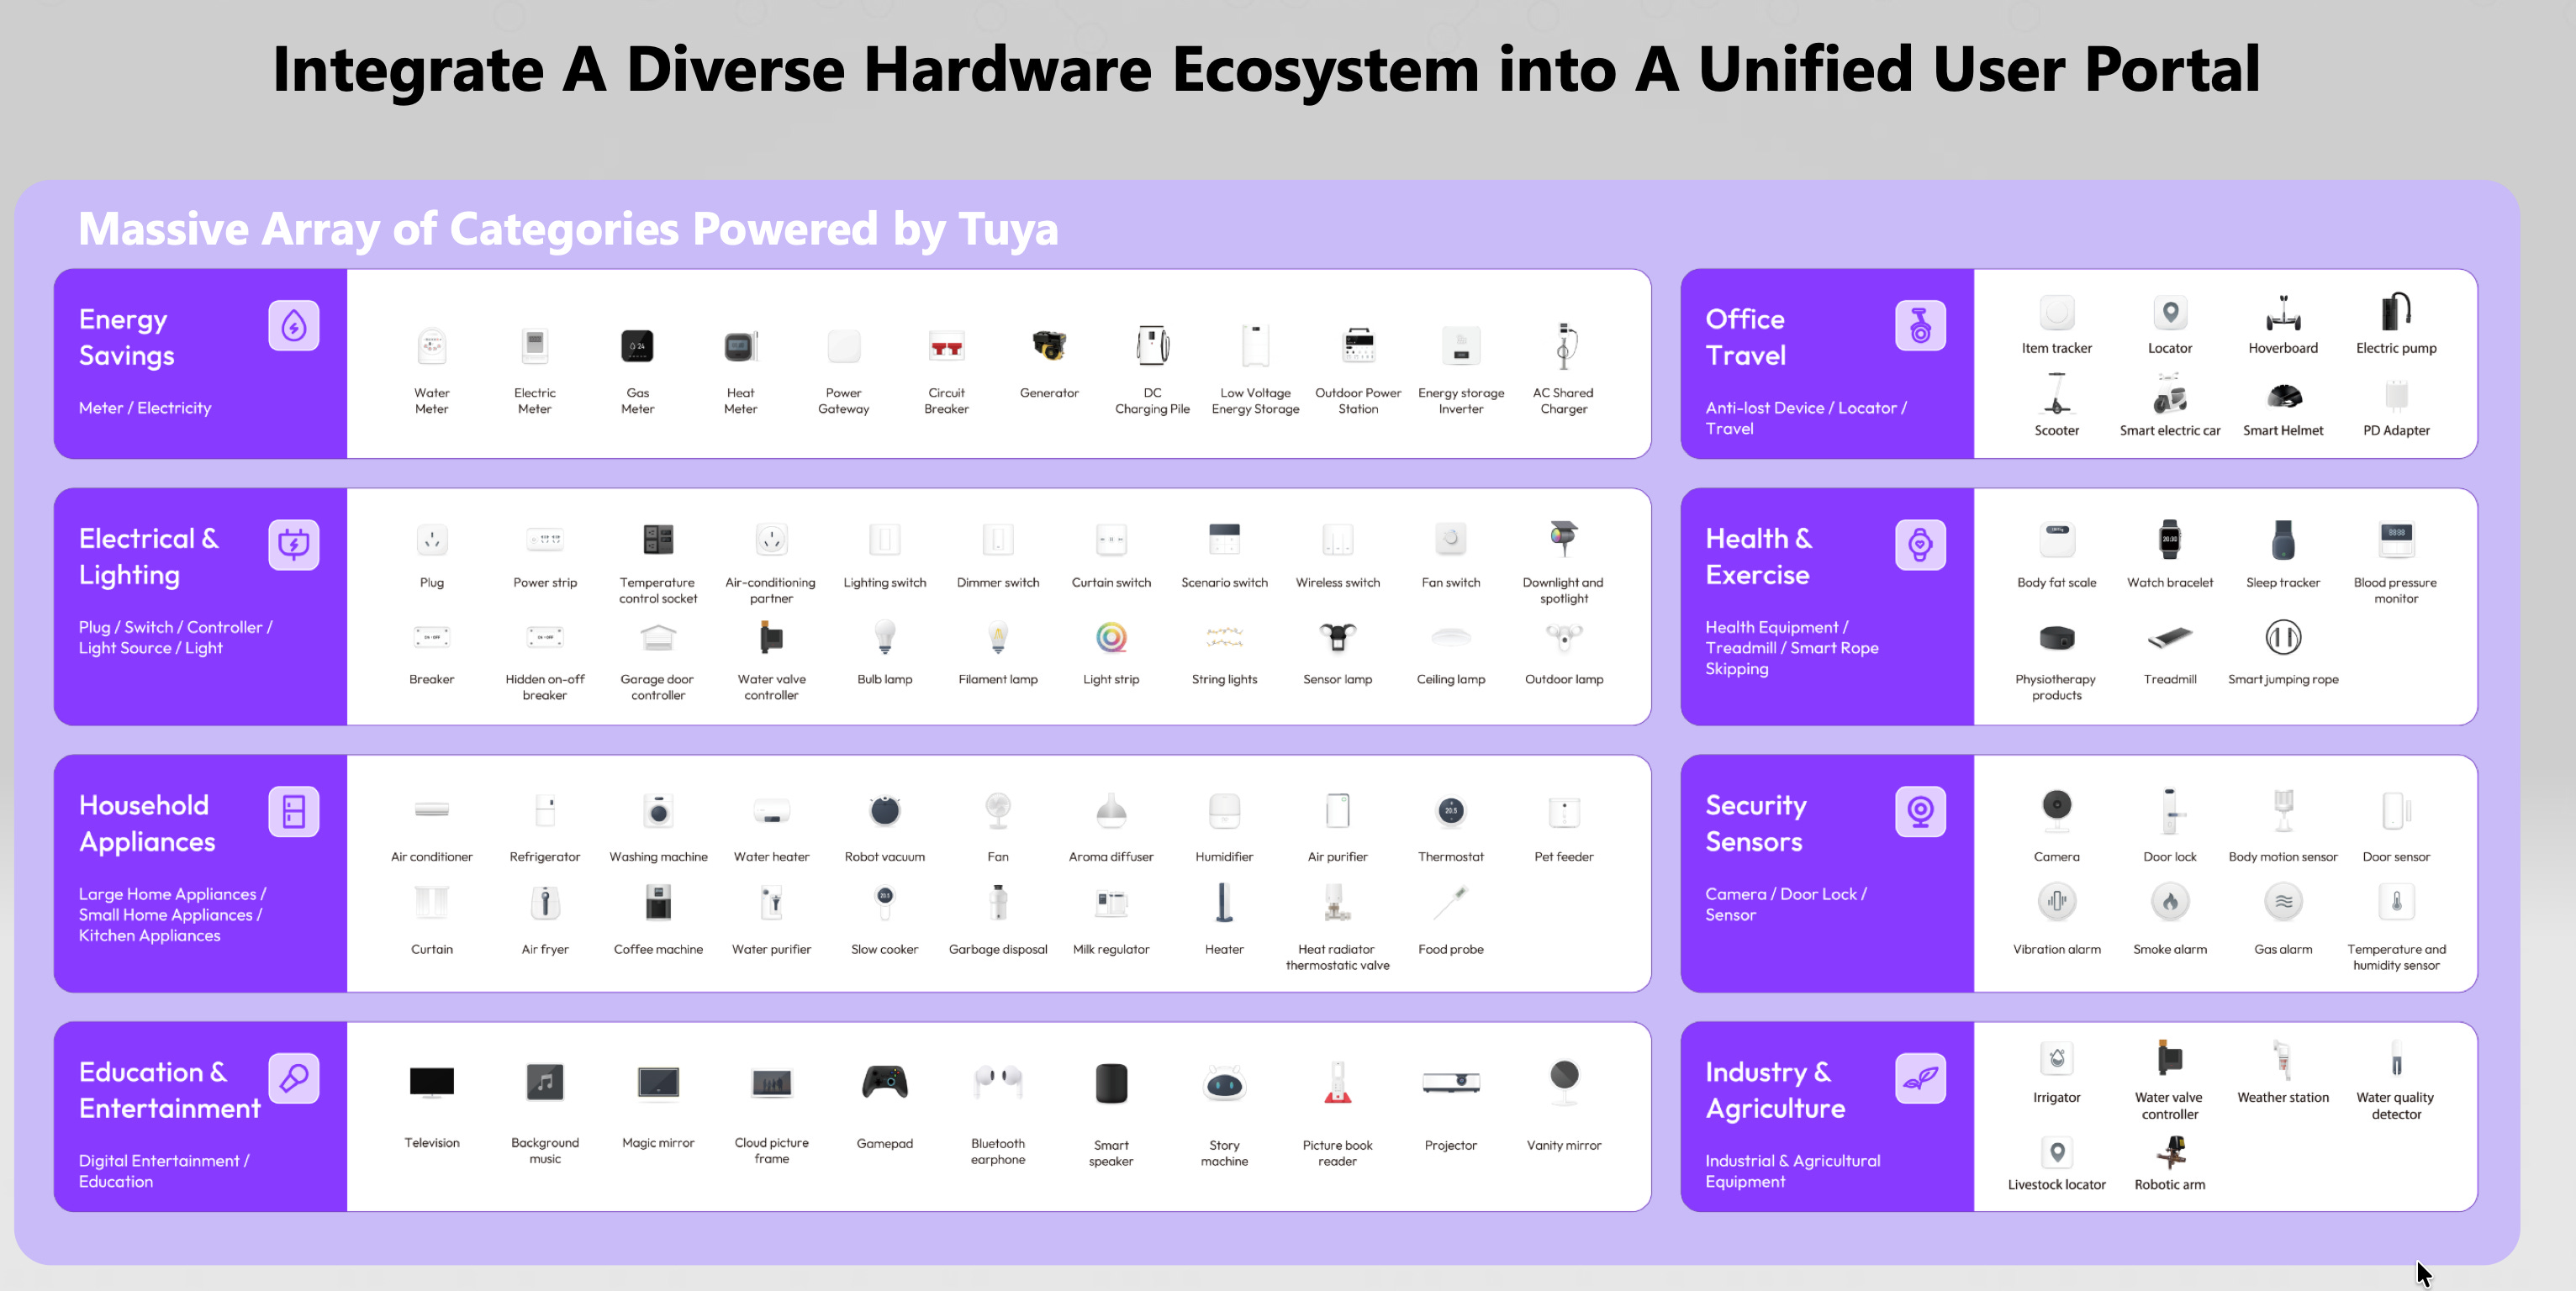
Tuya’s $976 million cash pile equals 94% of its $1.04 billion market cap as its smart-home platform returned to 16% revenue growth in Q2…
Fannie Mae and Freddie Mac could leave conservatorship through a 2026 restructuring and IPO, monetizing the government’s equity stake while…
 Glen Bradford 5 clicks
PesoRama will reach 54 JOi Dollar Plus stores by November after raising C$28.4 million, funding more than 50 additional Mexican store…
Modine, soon Modexus Solutions, has a $4 billion hyperscaler cooling contract but must ramp factory output and restore margins as data…
Dream Finders Homes’ controlling owner borrowed against DFH stock before the homebuilder agreed to finance an acquisition with costly…
Park Aerospace’s 11% Q2’27 sell-off overlooks sole-source PAC-3 rocket-motor materials and A320neo engine composites, with missile capacity…
UniQure's Huntington's gene therapy faces an FDA accelerated-approval decision around November 1 after three-year data met both agency…
 Bhavneesh Sharma 16 clicks
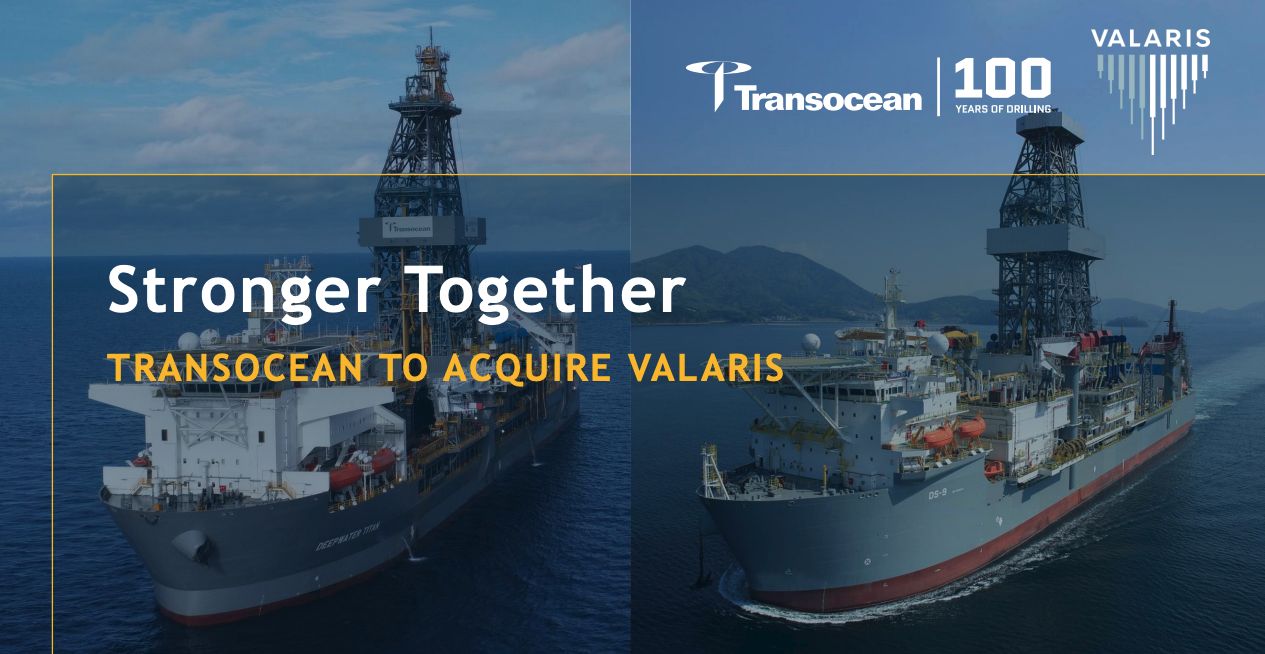
Transocean’s Valaris merger clears regulators, creating a 68-rig offshore driller controlling four in 10 global drillships.
October 2026 market commentary covers SOLS’s cancelled merger, a hypothetical Starbucks-Chipotle deal, Russell 2000 weakness and AI…
 SMWB · long
Similarweb (SMWB) is presented as a long, revisiting the company’s digital-intelligence business after two prior VIC write-ups.
NGL Energy Partners' capex more than quadrupled year over year as ABL borrowings and long-term debt rose, worsening its cash-generation…
 Long Player
Shenandoah Telecommunications’ Glo Fiber buildout ends this year, and private infrastructure investors’ repeated fiber deals frame a…
El Pollo Loco plans 18 to 20 FY26 openings, including 15 franchised New York stores over five years, as asset-light expansion and…
 Pedro Goulart 1 click
SED Energy's proposed Ventura merger projects a 22% to 40% dividend yield, but idle tender barges, debt and repayments materially reduce…
GitLab targets a 2027 inflection as agentic AI, software sovereignty demand and GitHub reliability issues lift win rates, first orders and…
 Ignacio Planas Gonzalez 1 click
Park Aerospace reported 27% revenue growth and 72% EPS growth, supported by composite materials for Airbus engines and PAC-3 rocket motors.
CarGurus, the largest U.S. auto-shopping marketplace, trades near $29 despite roughly $1 billion in expected revenue, $300 million in free…
Vicor uses ITC exclusion-order cases to license power-module patents, with published royalty multipliers rising from 1.0x before filing to…

Charles Lemonides argues the 18-year bull market has not reached its late-stage liftoff, pairing value-oriented semiconductor longs with…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Ryan Canady
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.