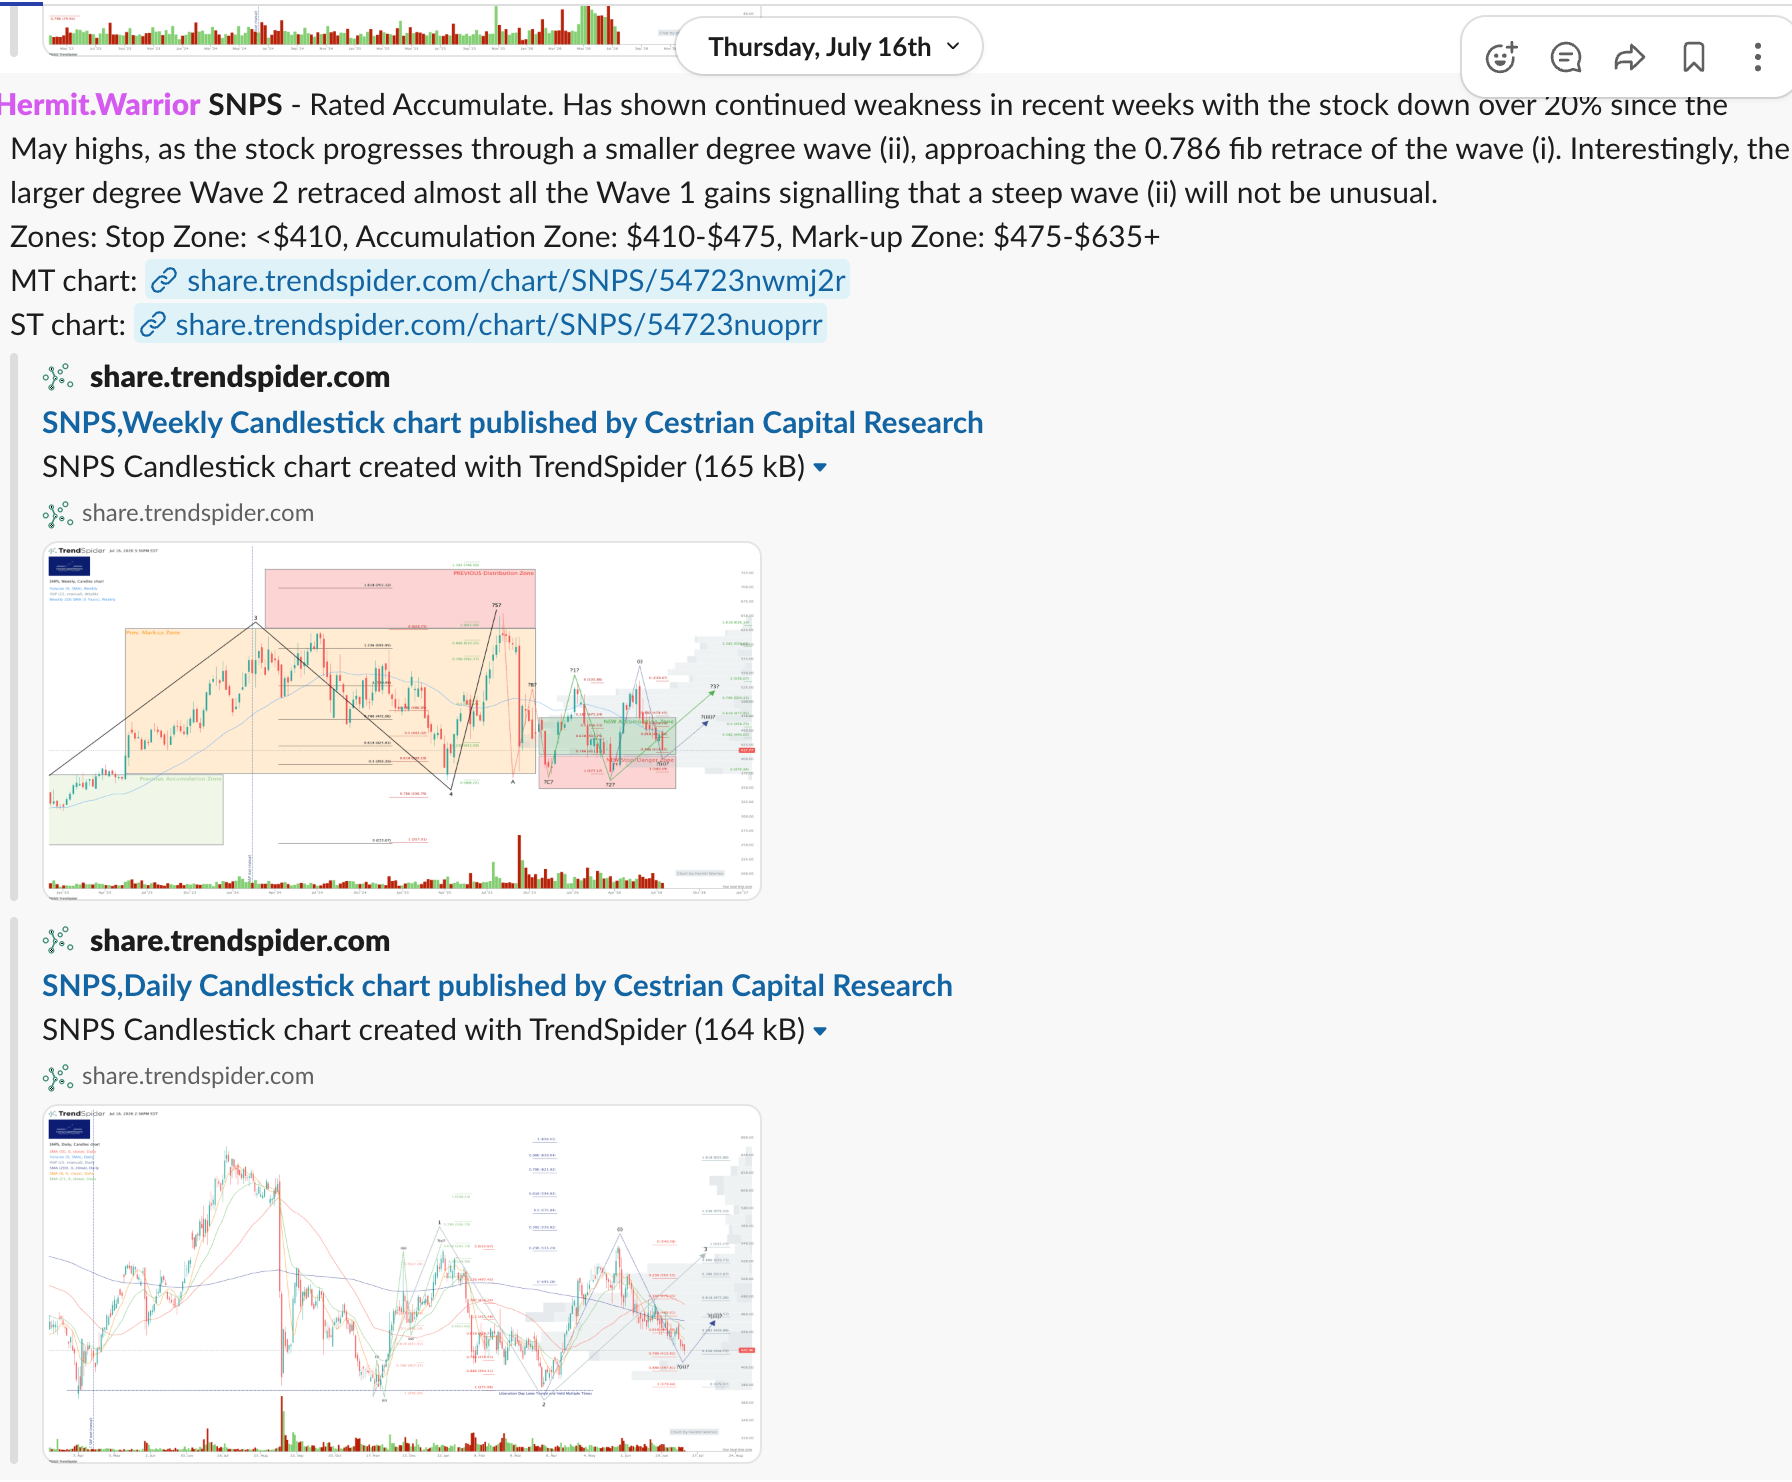
Synopsys (NASDAQ: SNPS) Stock Rating: DISTRIBUTE Ahead Of Q4 FY10/26 Earnings
Synopsys moved to Distribute after Q3 revenue rose 42% on Ansys, while organic growth was 7% and the stock traded at 11.1 times trailing revenue.
Synopsys moved to Distribute after Q3 revenue rose 42% on Ansys, while organic growth was 7% and the stock traded at 11.1 times trailing revenue.
Continue reading here for what a budget slip would do to $BWXT’s stock in my bear case: https://t.co/bPIYua98gd
GameStop $GME is doing the classic “pitch a tent” chart https://t.co/V41u9jWU8r
Isn’t this super bullish $CRDO because it means $LITE can’t supply a lot of the demand with optical, thus AECs likely see a larger demand in cases where they work? https://t.co/9gR7NQ2erE
Continue reading here for why lower HPDU costs mean less revenue but more profit for $BWXT: https://t.co/bPIYua98gd
AppLovin's Ads Manager targets middle-market e-commerce advertisers as Q3 guidance calls for 47% sales growth, while legal and compute-cost…
 Jack Elias 3 clicks
Robinhood’s AI agents, 24/7 equity trading and 10:1 crypto perpetual futures encourage higher retail trading velocity, leverage and…
Yellow Cake and Cameco say U.S. utilities have contracted only 40% of 2030 uranium needs, setting up a new contracting cycle as…
Special-situations survey profiles 26 activist, capital-return, M&A and strategic-alternative catalysts, led by buybacks at Under Armour,…
Millrose told Goldman its Lennar purchases had rent-to-own tenants lined up, but most analyzed homes were advertised for rent and showed…
Nike's 4.8% dividend yield masks payout ratios above 100% of forward EPS and inadequate free cash flow coverage, while China sales declines…
 Sensor Unlimited
Vertiv's 33% stock decline followed a 2026 forecast increase, despite a $15 billion backlog and rising AI data-center demand for power and…
Undercovered Dozen spotlights 12 lesser-covered stocks, including Brookfield Renewable, Annaly Capital and Seagate.
 The Undercovered Dozen
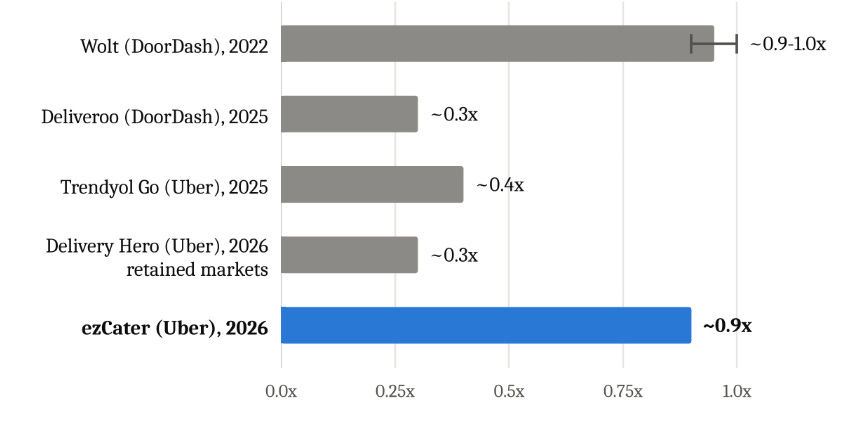
Uber’s $2.3 billion cash purchase of ezCater extends its buy-versus-build strategy and raises questions about the price and capital…
L3Harris upgraded to Accumulate after a 38% stock decline, backed by 8% Q2 revenue growth, a $42 billion backlog and planned Missile…
OpenAI’s enterprise privacy push and Synopsys’s Factory 2 royalty model anchor a technology roundup, alongside oil above $100 and Bitcoin’s…
Adobe rates Accumulate at $189-$266 after Q3 FY26 revenue grew 12.9%, while management guided slower growth and RPO growth decelerated.
 VEEV · long
Veeva Systems is a vertical software company valued as if its best growth years are behind it.
On Holding (ONON) is gaining sportswear share, expanding store space and launching soccer with Kylian Mbappé as investors debate U.S.
Rollins’ recurring pest-control base requires ongoing spending to replace departing customers, a concern tied to its nearly 50%…
Intuit’s $21.4 billion software franchise faces AI-driven pricing pressure in tax and accounting, even as QuickBooks and TurboTax retain…
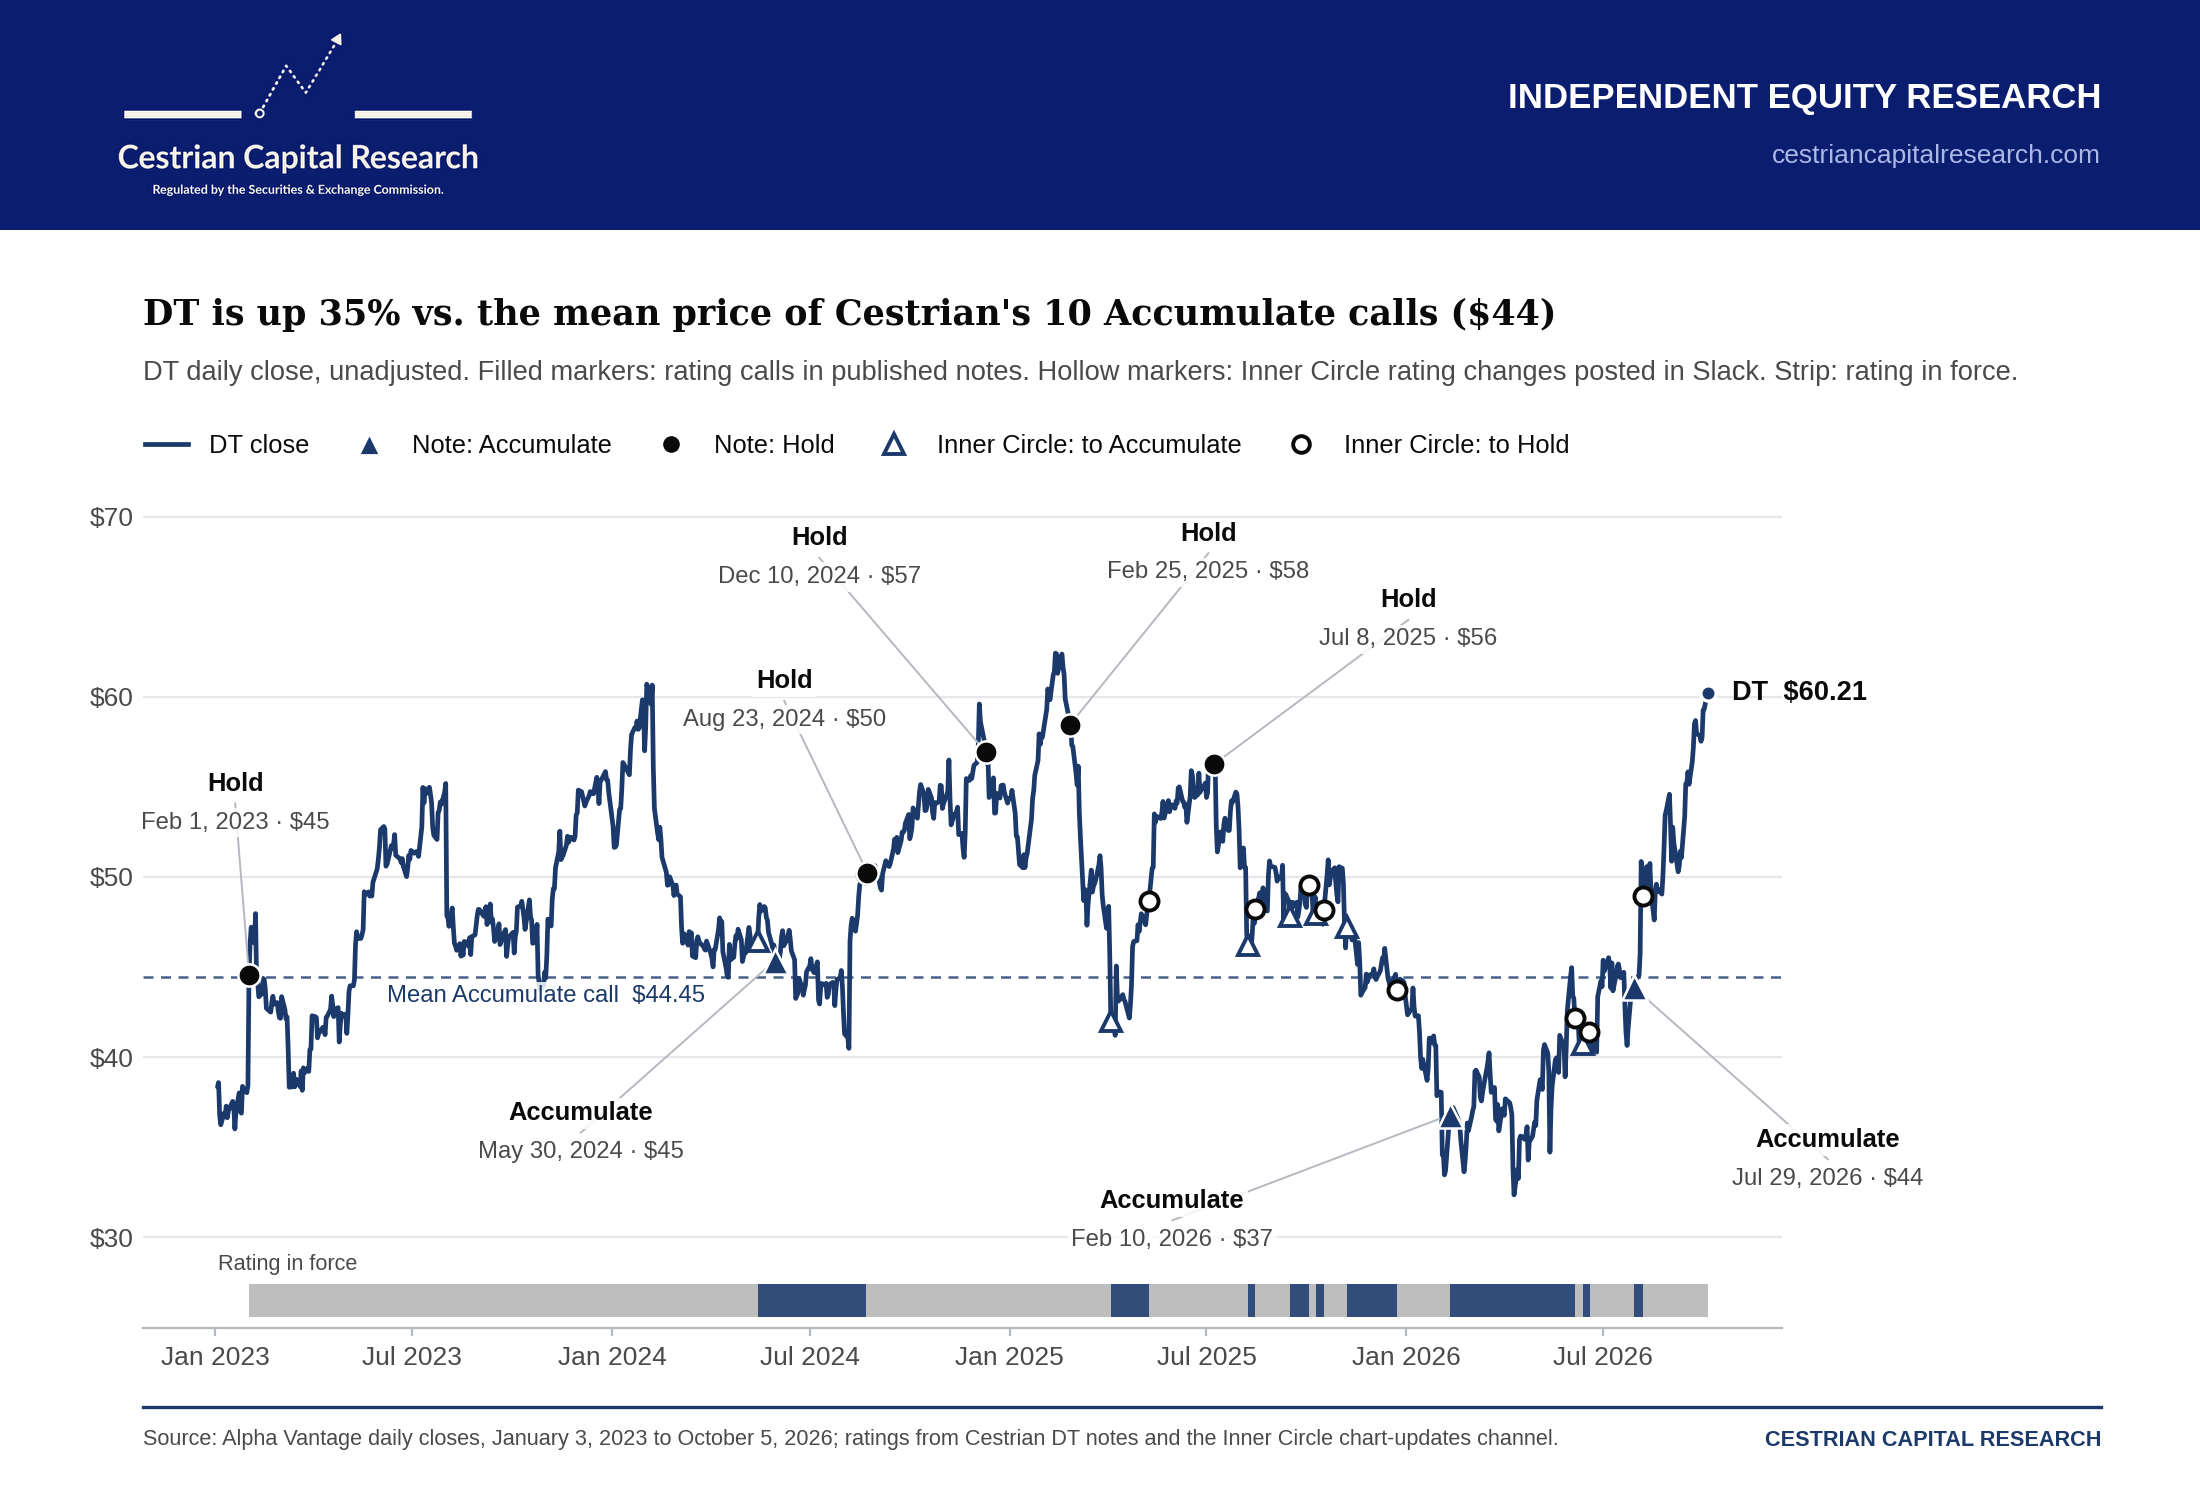
Dynatrace is rated Distribute after a 90% rally to $60.21 nears $62 resistance, while revenue and RPO growth decelerate ahead of November…
Nebius gains preferred sovereign infrastructure status for Palantir’s enterprise AI stack, using its customer base to accelerate modular…
 Petri Dish Reports 3 clicks
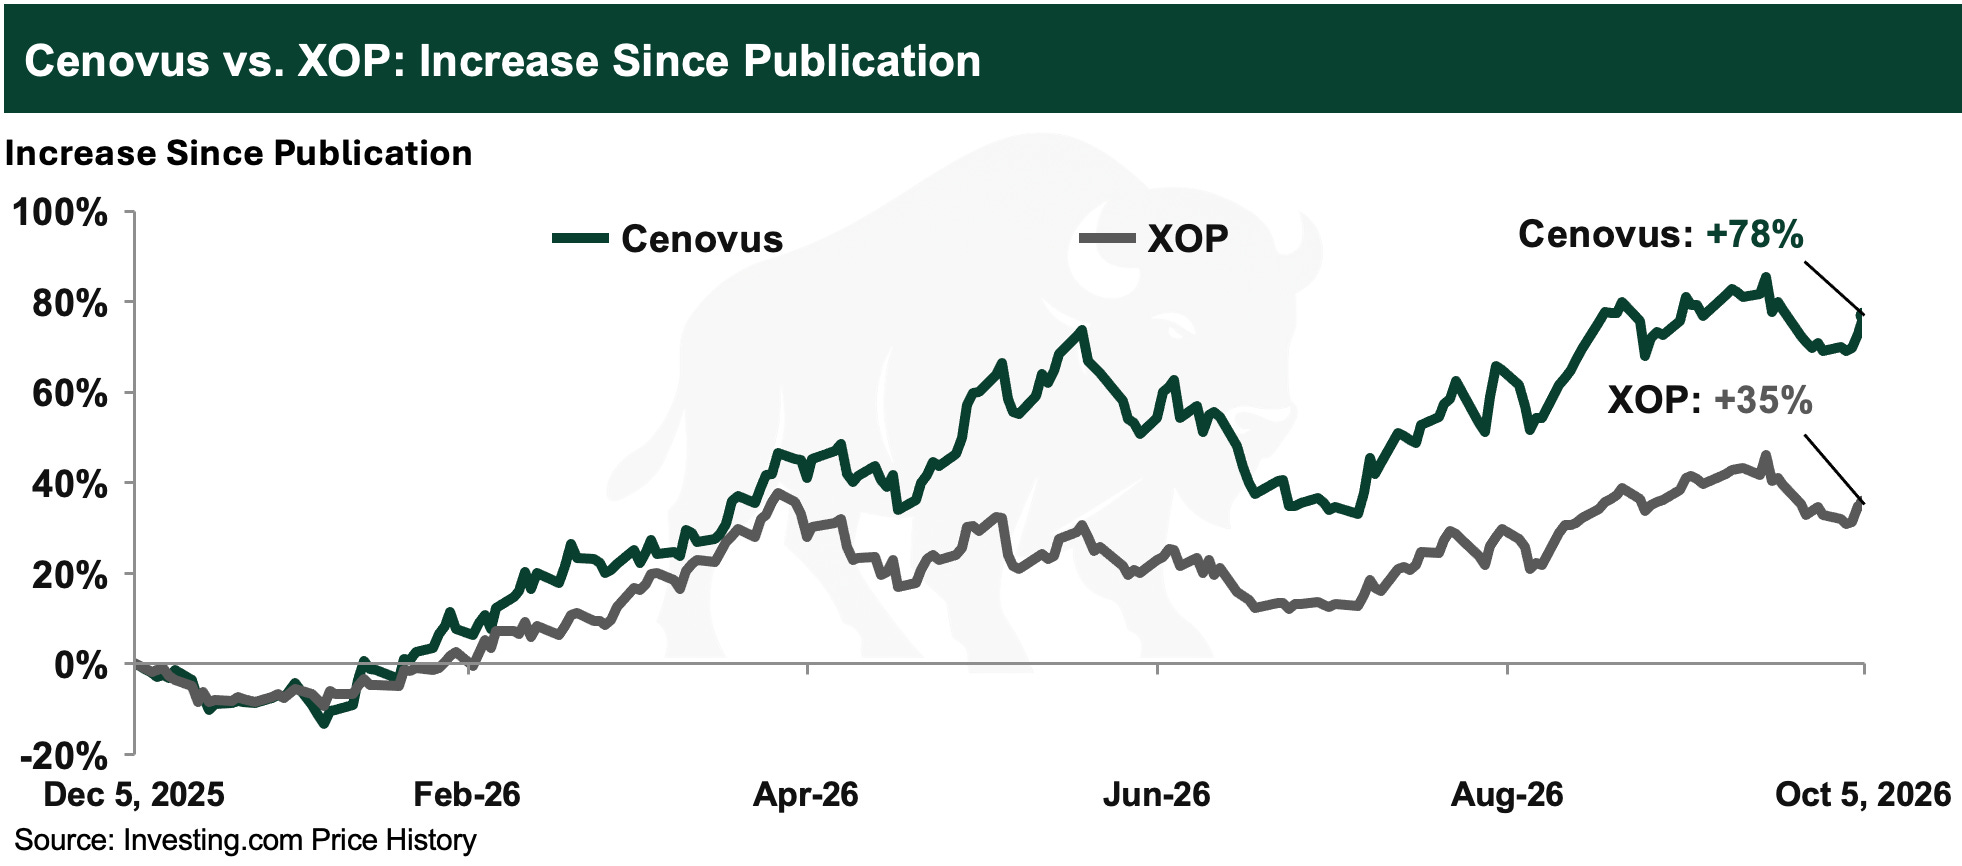
Cenovus Energy, up 78% in 10 months, is sold after agreeing to buy Athabasca Oil for $5.7 billion at a rich valuation.
Canterra Minerals increased Lundberg indicated tonnage 55% to 26.1Mt, with 226.2Kt of contained copper equivalent, supporting a Buchans…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.