EXCLUSIVE: Lennar’s Big New Customer Is Its Own Spinoff, Millrose
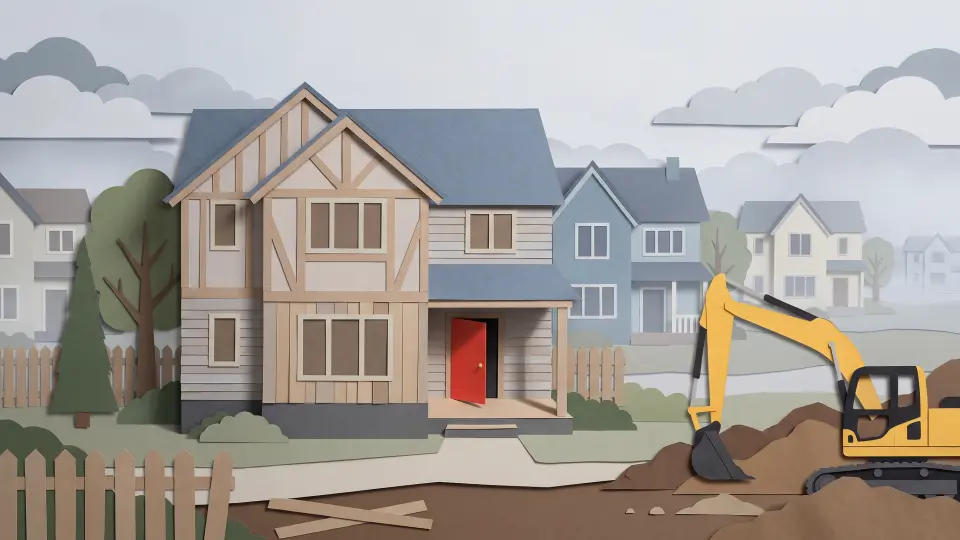
Lennar is selling homes to former spinoff Millrose, whose revenue largely comes from Lennar and whose largest voting shareholder is Lennar’s CEO.
Lennar is selling homes to former spinoff Millrose, whose revenue largely comes from Lennar and whose largest voting shareholder is Lennar’s CEO.
@JJNews002 bought a little of it too $ABVX
big news in fintech land $NU Monzo in talks with Brazil’s Nubank about sale https://t.co/B0Yx5Lt4Yw
We are delighted that $PSUS and $PS are now listed on the Mexican Stock Exchange. We will be visiting our Mexican shareholders next month and look forward to a long-term relationship. https://t.co/HwMJ8tZS34
@_Housing_Guy_ Structural deficit in houses will need to balance eventually. Cycle will cycle eventually (rates, inflation economy ect). Company won’t go bankrupt and will chug along until then. Transition to capital light $NVR model not fully priced in.
Cloudflare is building HTTP 402 payments for AI agents, using its web network to let publishers charge bots for content access.
Nike’s second Latticework program examines the company and the global athletic footwear and apparel industry for professional investors.
Nike grew from a $1,000 shoe-distribution venture in 1964 into the largest sports brand, using athlete endorsements, product innovation and…
ServiceNow expects AI annual contract value to reach $1.5 billion by year-end, with assist-pack consumption pricing supporting growth…
 Jetstream Research 1 click
Rocket Lab reported Q2 revenue up 62% to $234.1 million and backlog up 137% to $2.36 billion, while operating losses and cash burn…
AAR’s $1.8 billion acquisition of a 65% stake in MRO Holdings adds widebody aircraft maintenance and targets a 19% to 20% EBITDA margin by…
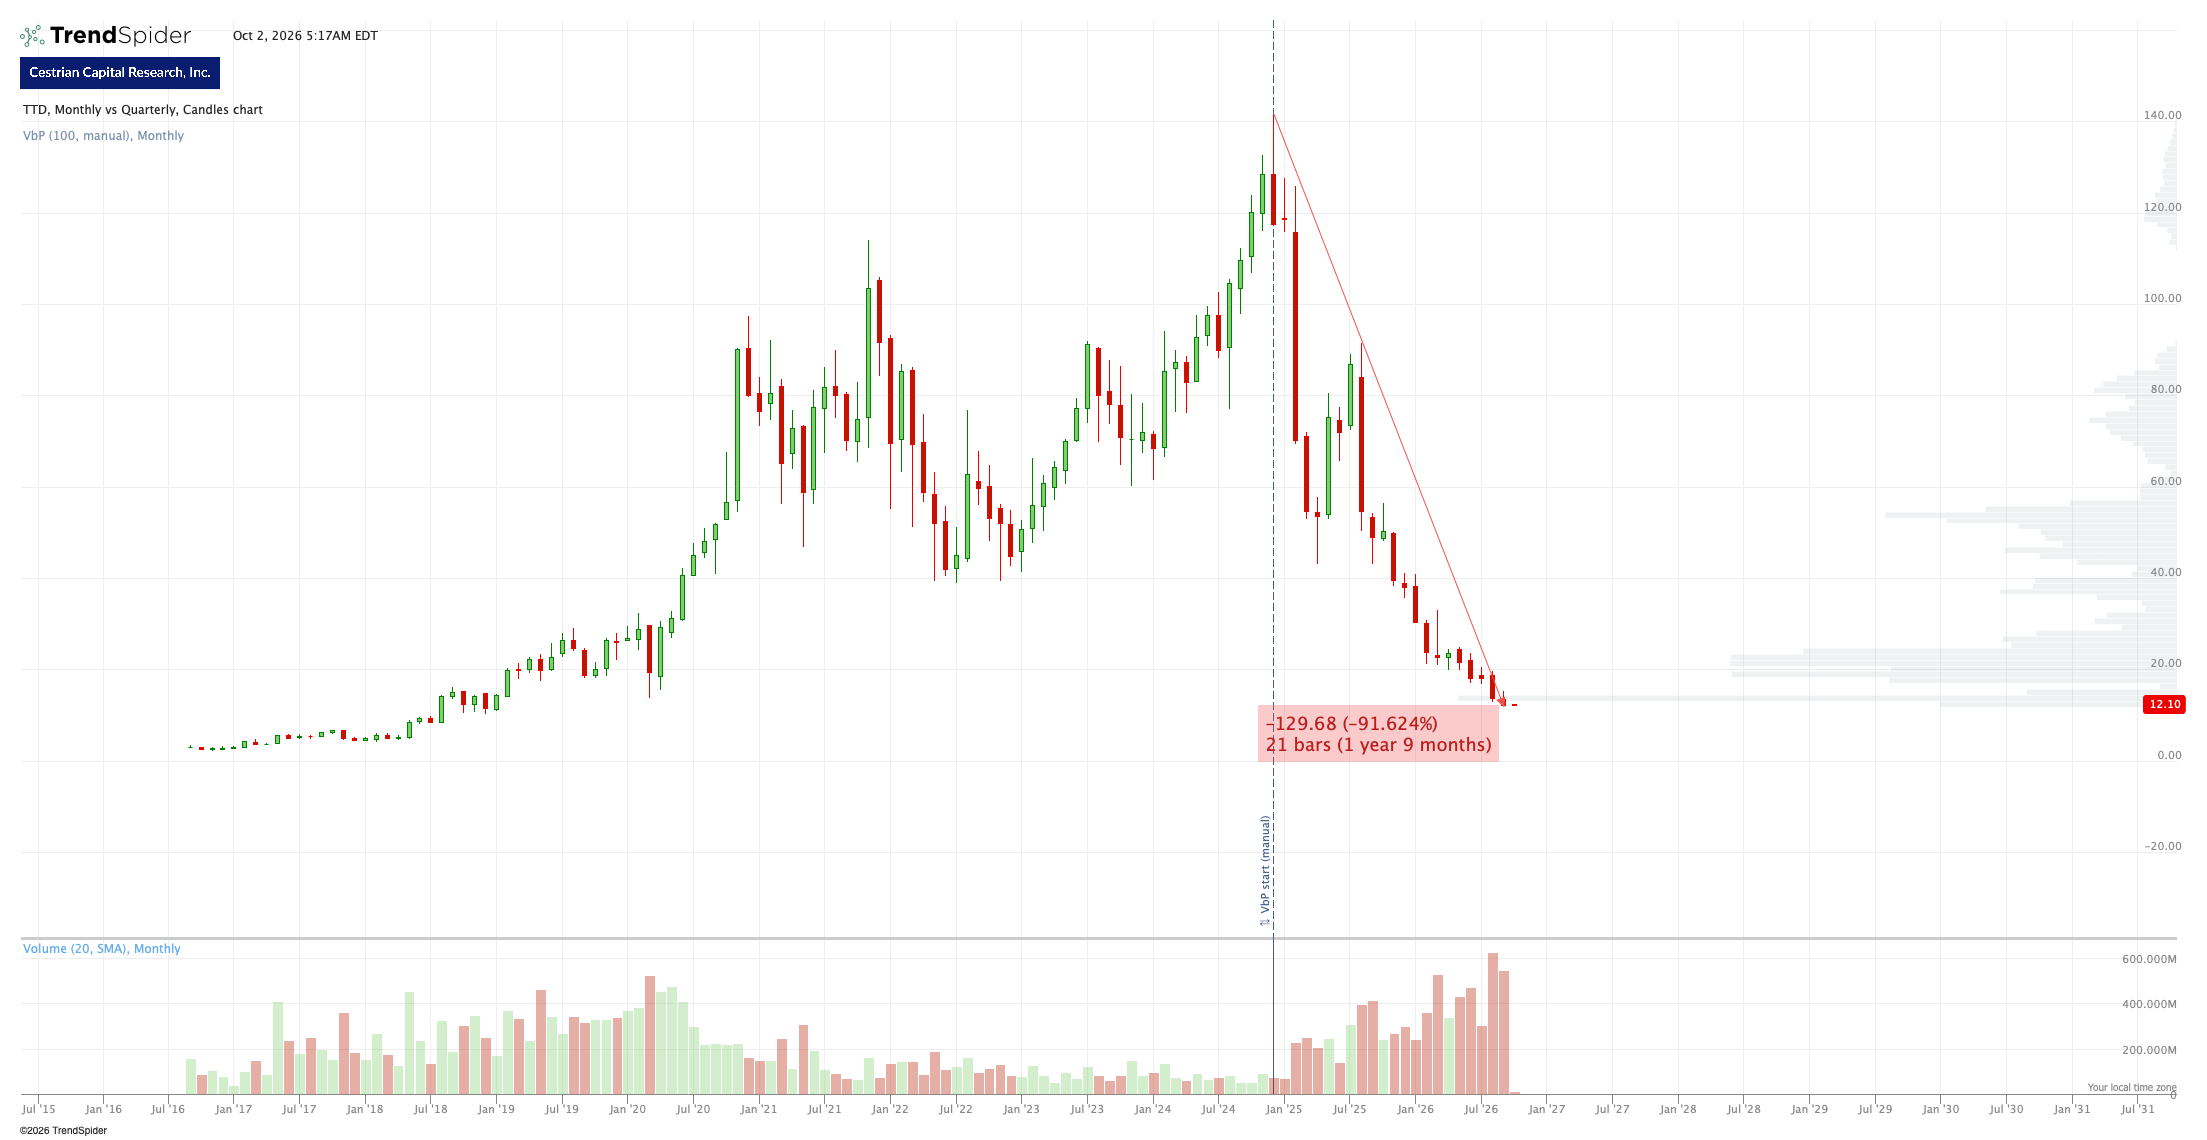
The Trade Desk's Q2 revenue grew 3% to $715 million as Q3 guidance called for a year-over-year decline; TTD has fallen over 90% from its…
Belden targets net leverage of 2.9x by 2027 from 3.9x, using RUCKUS's 65%+ gross margins and free cash flow to reduce debt.
 Lee Bailey
CrowdStrike faces a trim at a $270 billion valuation and 140x free cash flow, despite AI-driven cybersecurity demand and a $20 billion ARR…
Mattel rose 19% on takeover speculation, but a potential $20-per-share bid, margin pressure and CEO transition leave its standalone…
 Seeking Profits
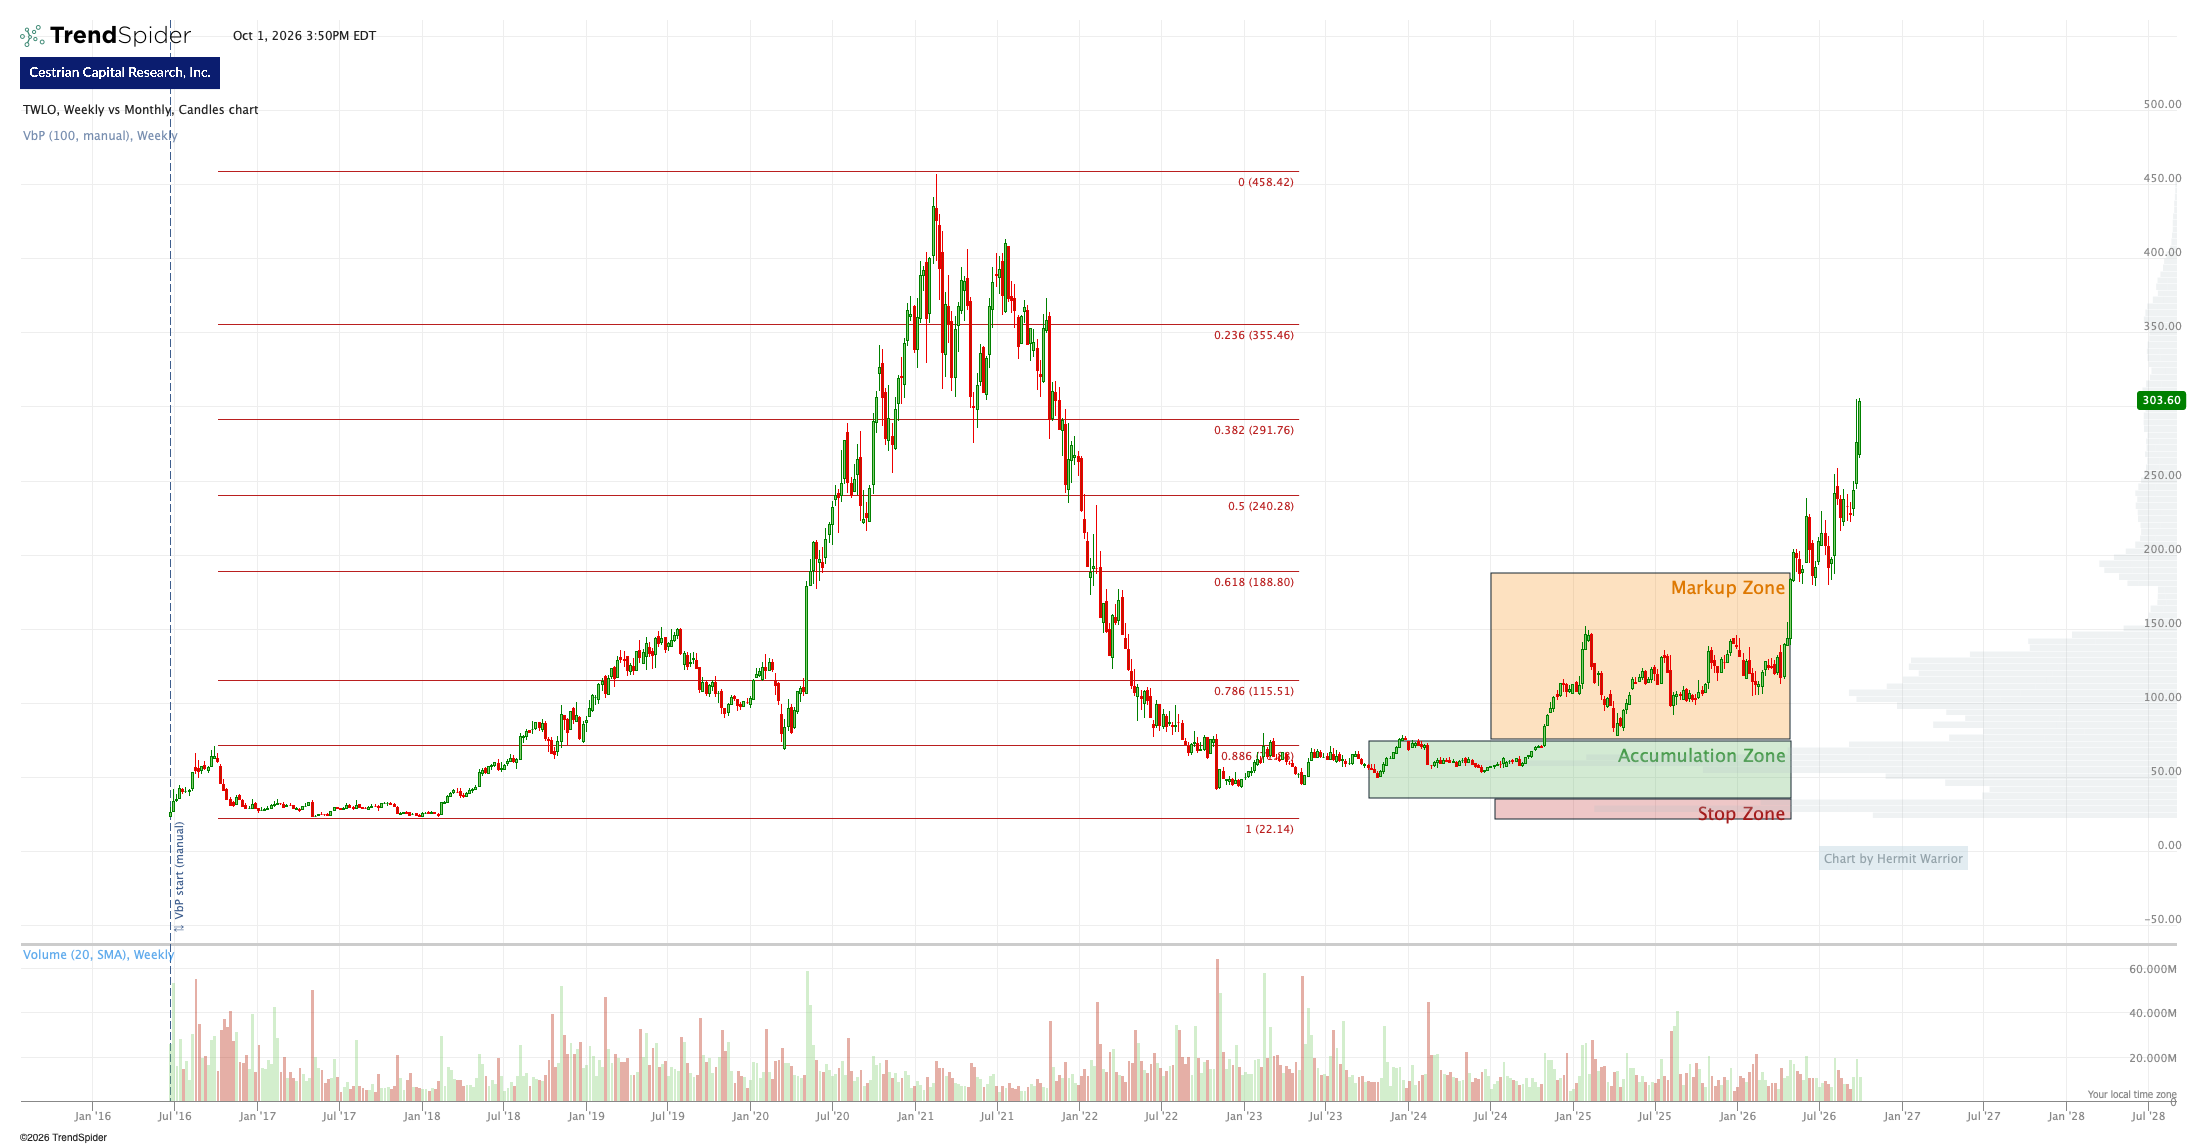
Twilio posted Q2 revenue of $1.50 billion, up 22%, and guided 16% Q3 growth; the note rates TWLO Hold at $305, with a $260 risk line.
Anthropic spent $2.75 per revenue dollar in 2025 and committed $518 billion to compute, while AI debt at CoreWeave, Oracle and data-center…
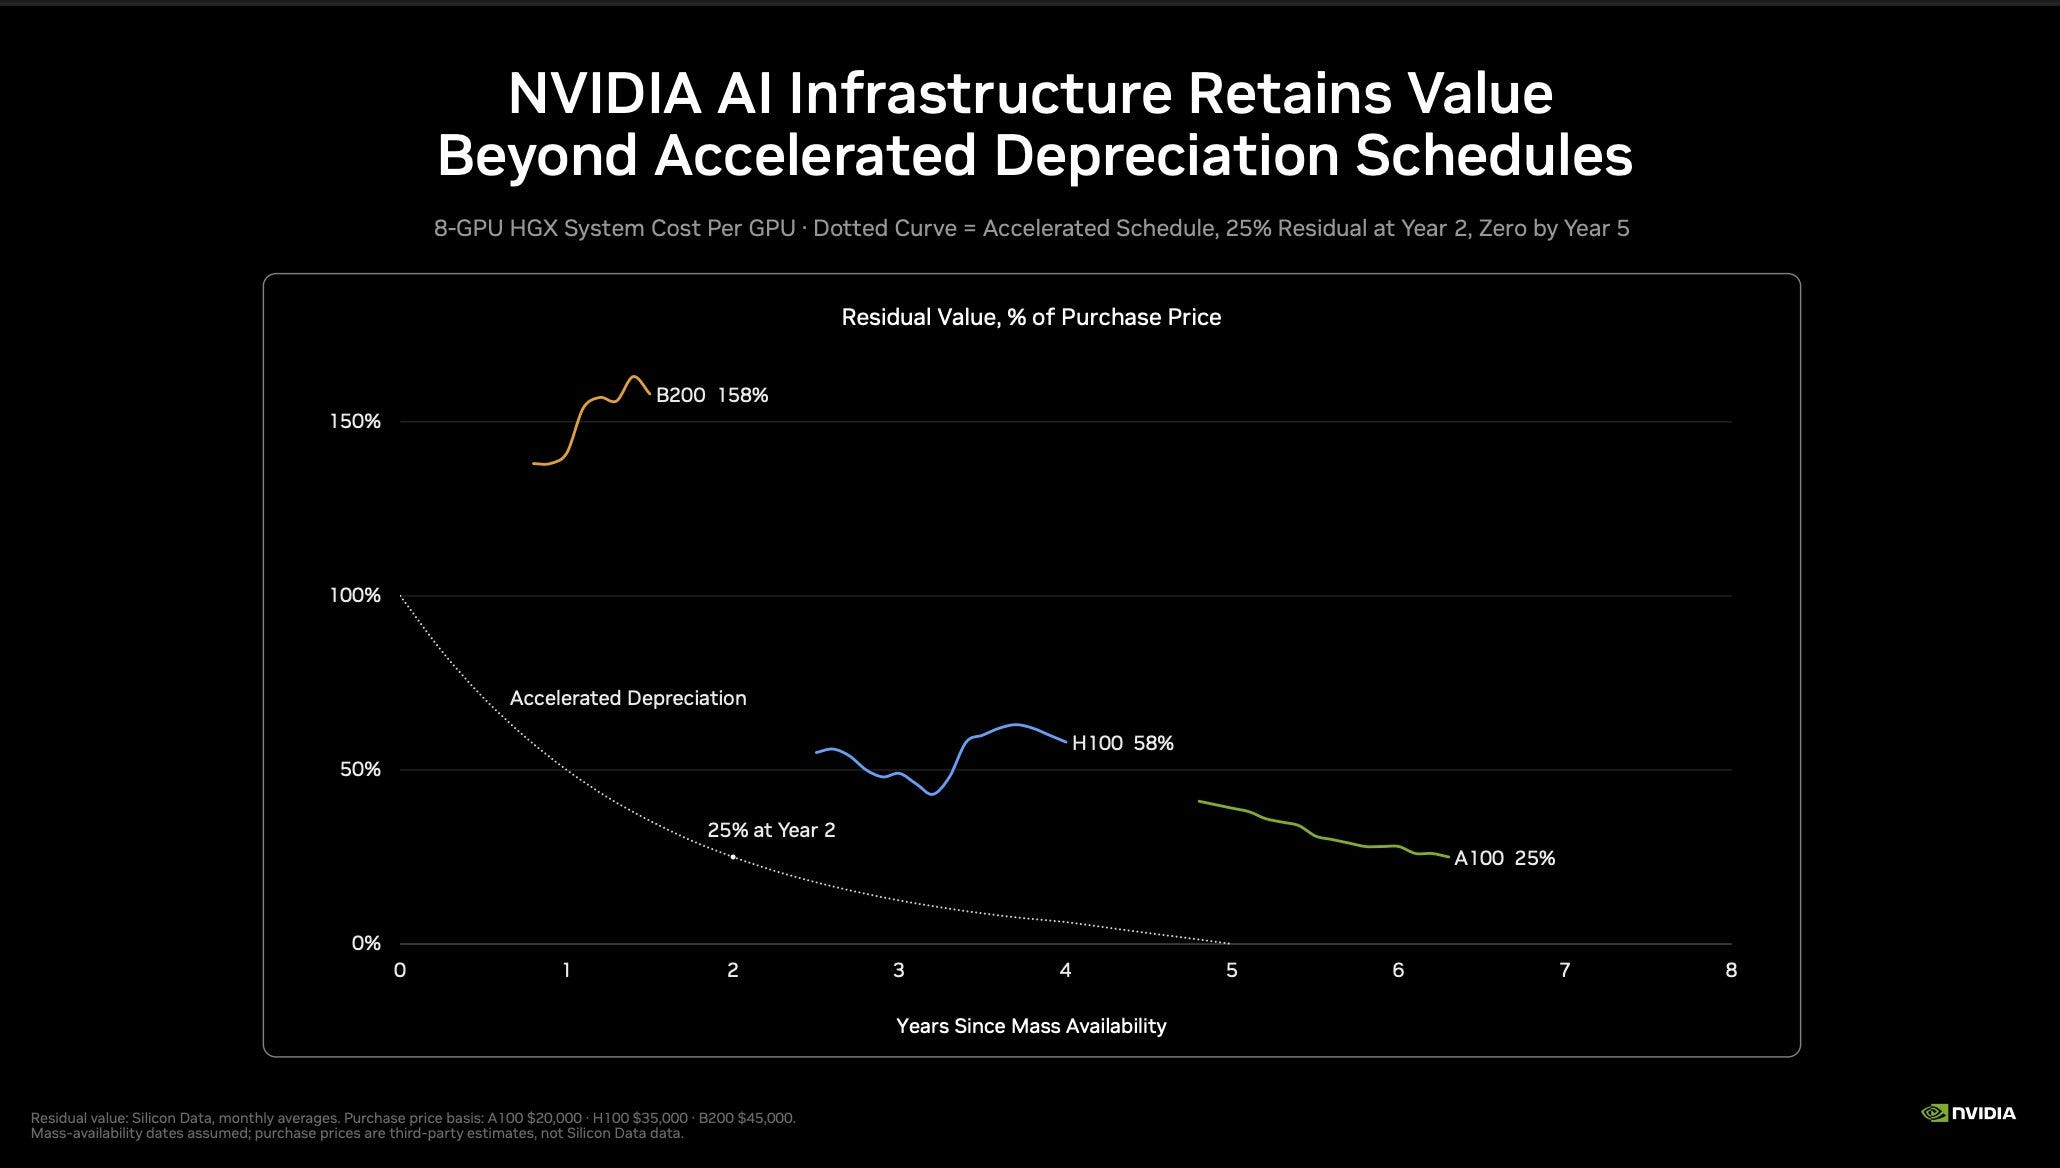
Nvidia argues A100, H100 and B200 GPUs retain value beyond five-year depreciation schedules, reviving comparisons with the 1960s…
Muse could sidestep ads by becoming a neutral commerce agent, while DoorDash and Airbnb build proprietary agents that steer users toward…
Chipotle's Q2 revenue rose 9.3% as traffic and market share grew; the case rests on pricing catching inflation to restore margins.
 The Alpha Analyst
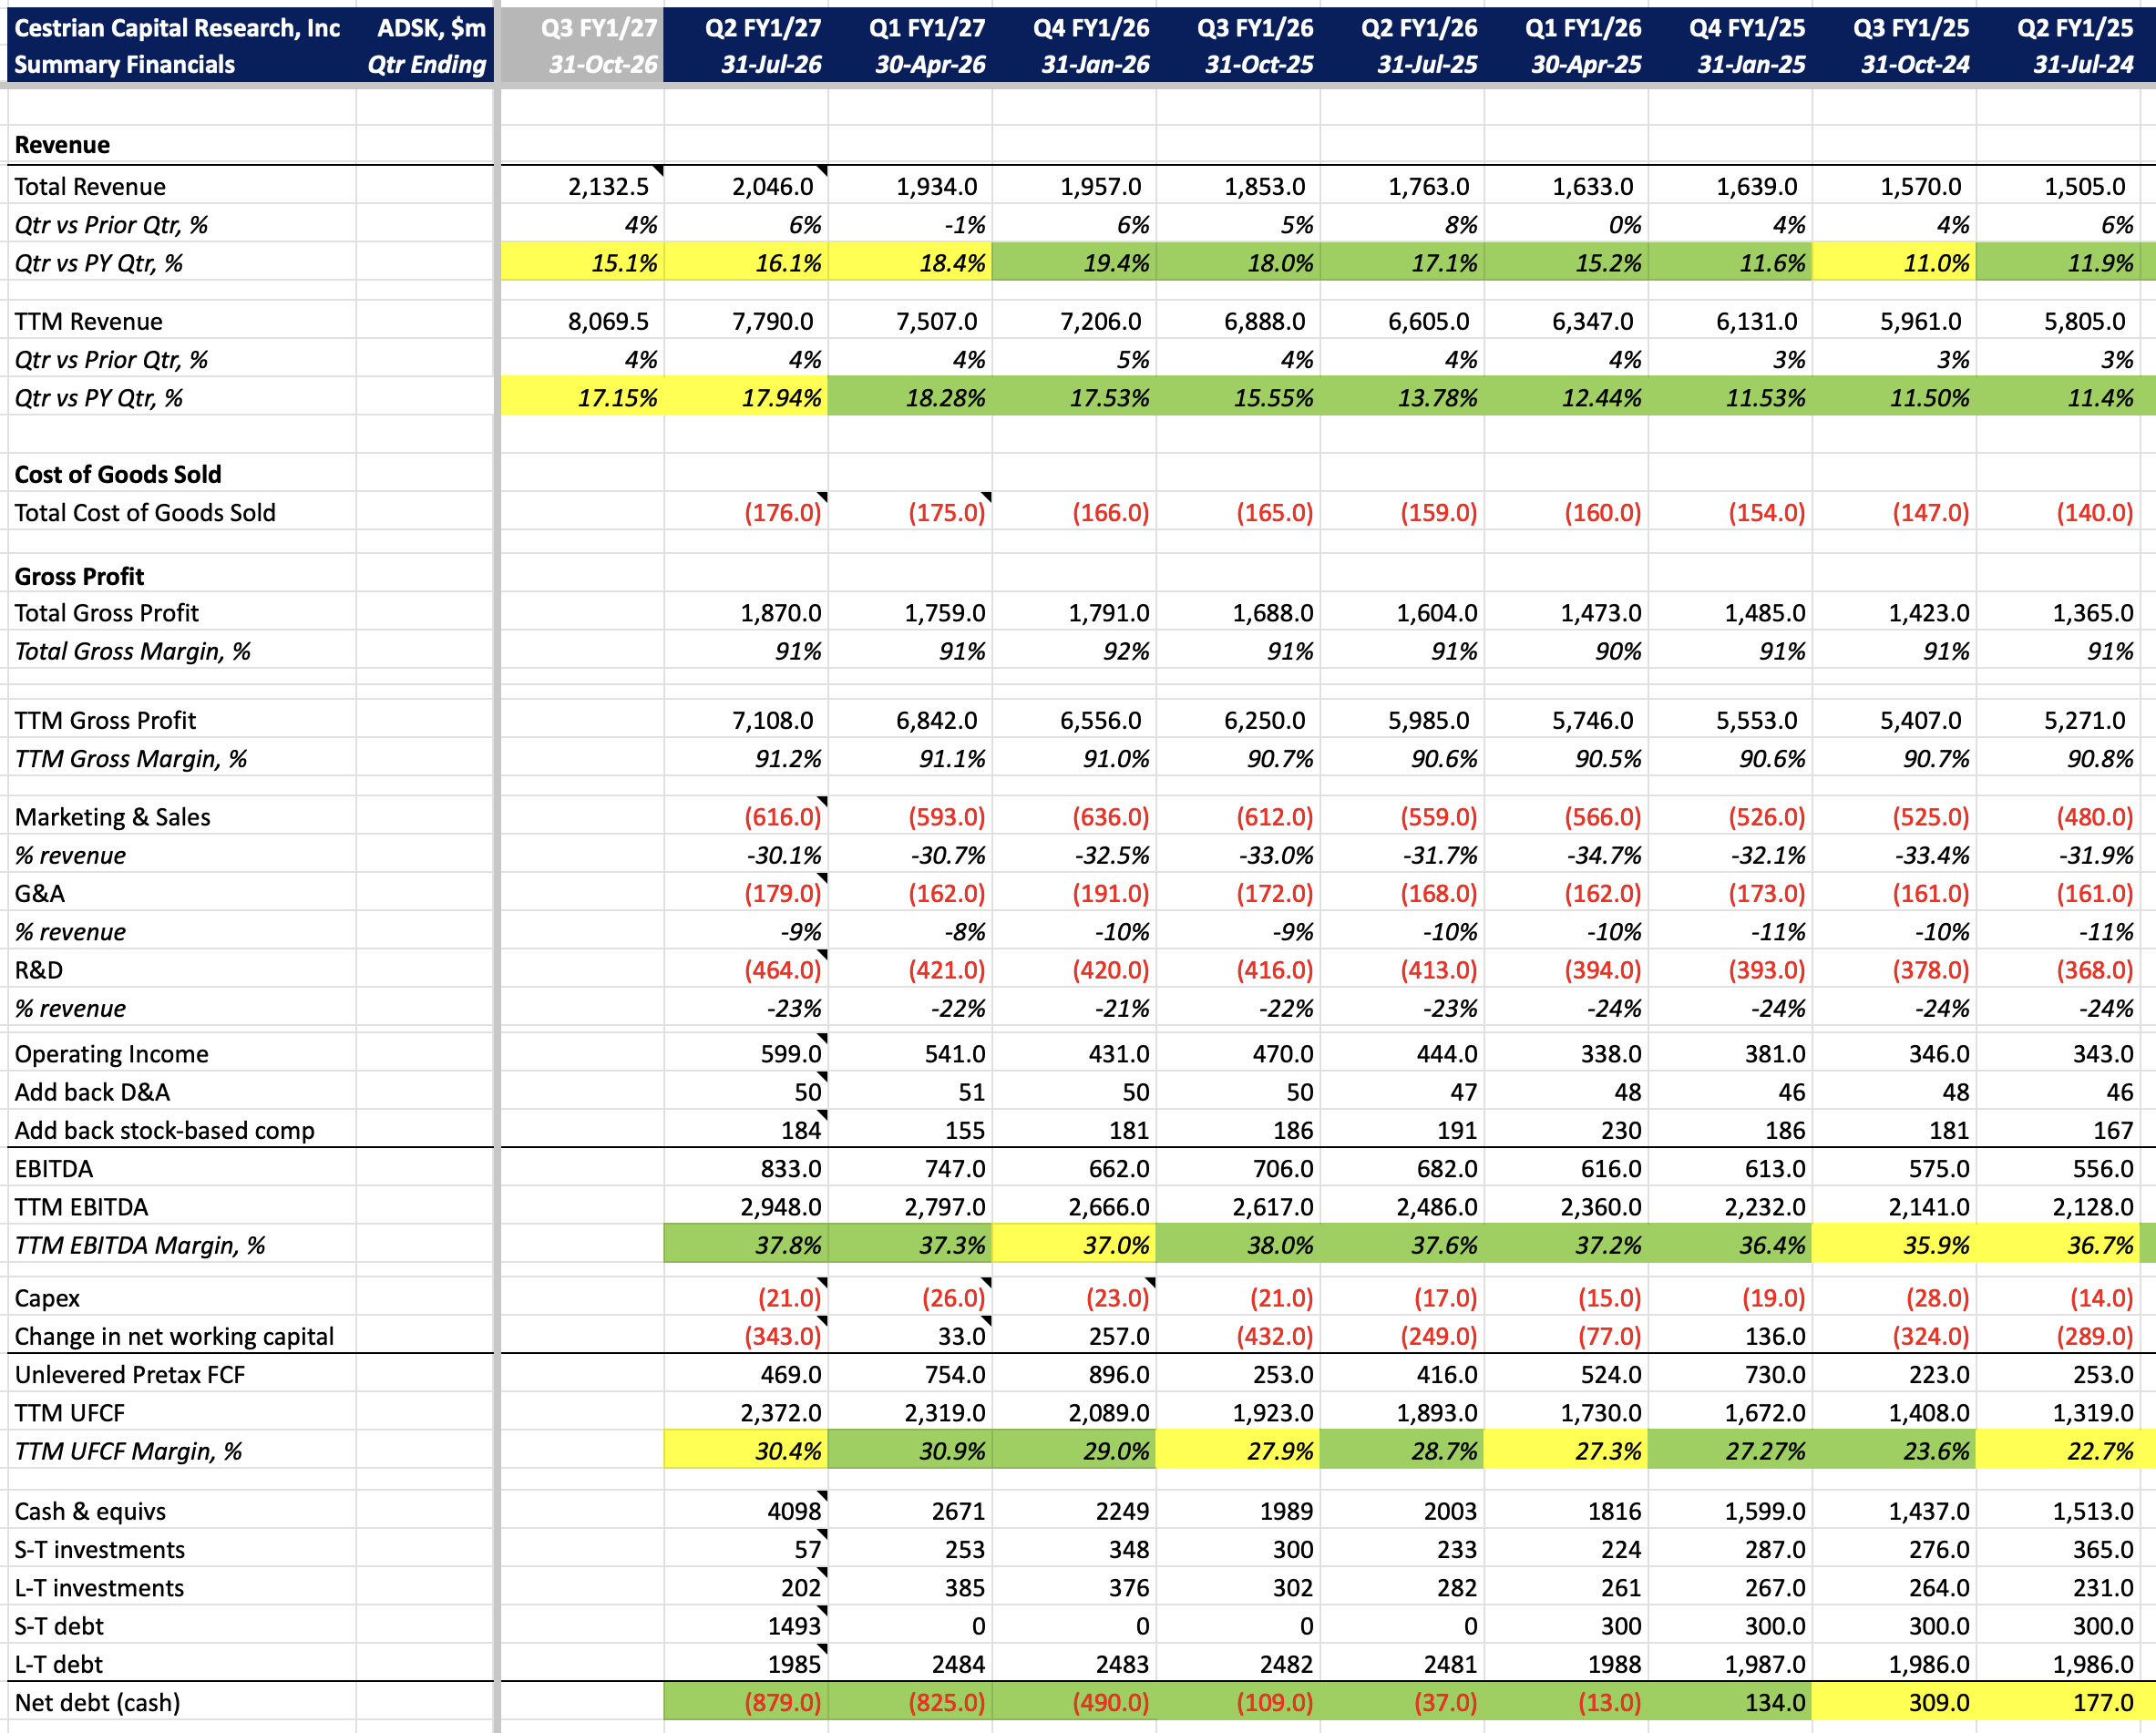
Autodesk reported Q2 revenue growth of 16% to $2.05 billion, while RPO growth slowed to 2%; FY2027 guidance calls for $8.30 billion to…
YieldMax HOOD Option Income Strategy ETF pays high weekly income from Robinhood volatility, but return-of-capital distributions and a 0.99%…
 Ivan Gaddari
Ethos Technologies ($LIFE) sells AI-driven life insurance while relying heavily on multilevel marketing agencies using aggressive cold…
Karman Holdings reported 58% Q2 revenue growth, $1.3 billion backlog and margin expansion while replacing leadership and remediating…
Innodata's 45% pullback resets its valuation after two quarters of 50% revenue growth, though two customers still supply 71% of revenue and…
 Kurt Christensen 1 click
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.