The Next Consumer is a Computer
Meta’s Muse illustrates how persistent AI agents shift compute from per-query to per-user, driving heavier GPU, CPU and memory demand.
Meta’s Muse illustrates how persistent AI agents shift compute from per-query to per-user, driving heavier GPU, CPU and memory demand.
Newest out. Philip Morris International: Centered "Q1'26 note" $PM $BTI $MO $IMBBY $HAYPP $STG https://t.co/QWIjmx81rA
1M, 6M and 5Y $MAPS chart. Sometimes a stock was just a 💩, is still a 💩 and will always remain a 💩 https://t.co/GOAKZYTZrT
I just published my Earnings Update about the Q1 2026 of Evolution $EVO $EVVTY. You can find it in the Portfolio section of the blog :) https://t.co/QXlBS93lji
What did I tell you guys 100 times?? Wait until we're finished doing the works! $RDCM https://t.co/15NpmF6Ytc https://t.co/2l52A8yhZ3
@ramahluwalia how much are you investing in $acn as a % of your book?
Solitron Devices $SODI releases preliminary Q4 results. Annual meeting this Friday. https://t.co/89tXyZdnYY
Yuanbao pairs a 10.2% dividend and cash exceeding its market value with 33.5% first-half profit growth from AI-enabled Chinese insurance…
Vicor, Rayonier, Accenture and nine other lesser-covered stocks make up Seeking Alpha’s Undercovered Dozen.

Ben Pouladian argues AMD’s Helios racks cannot match NVIDIA GPUs’ fungibility and financing appeal as agentic AI shifts the bottleneck to…
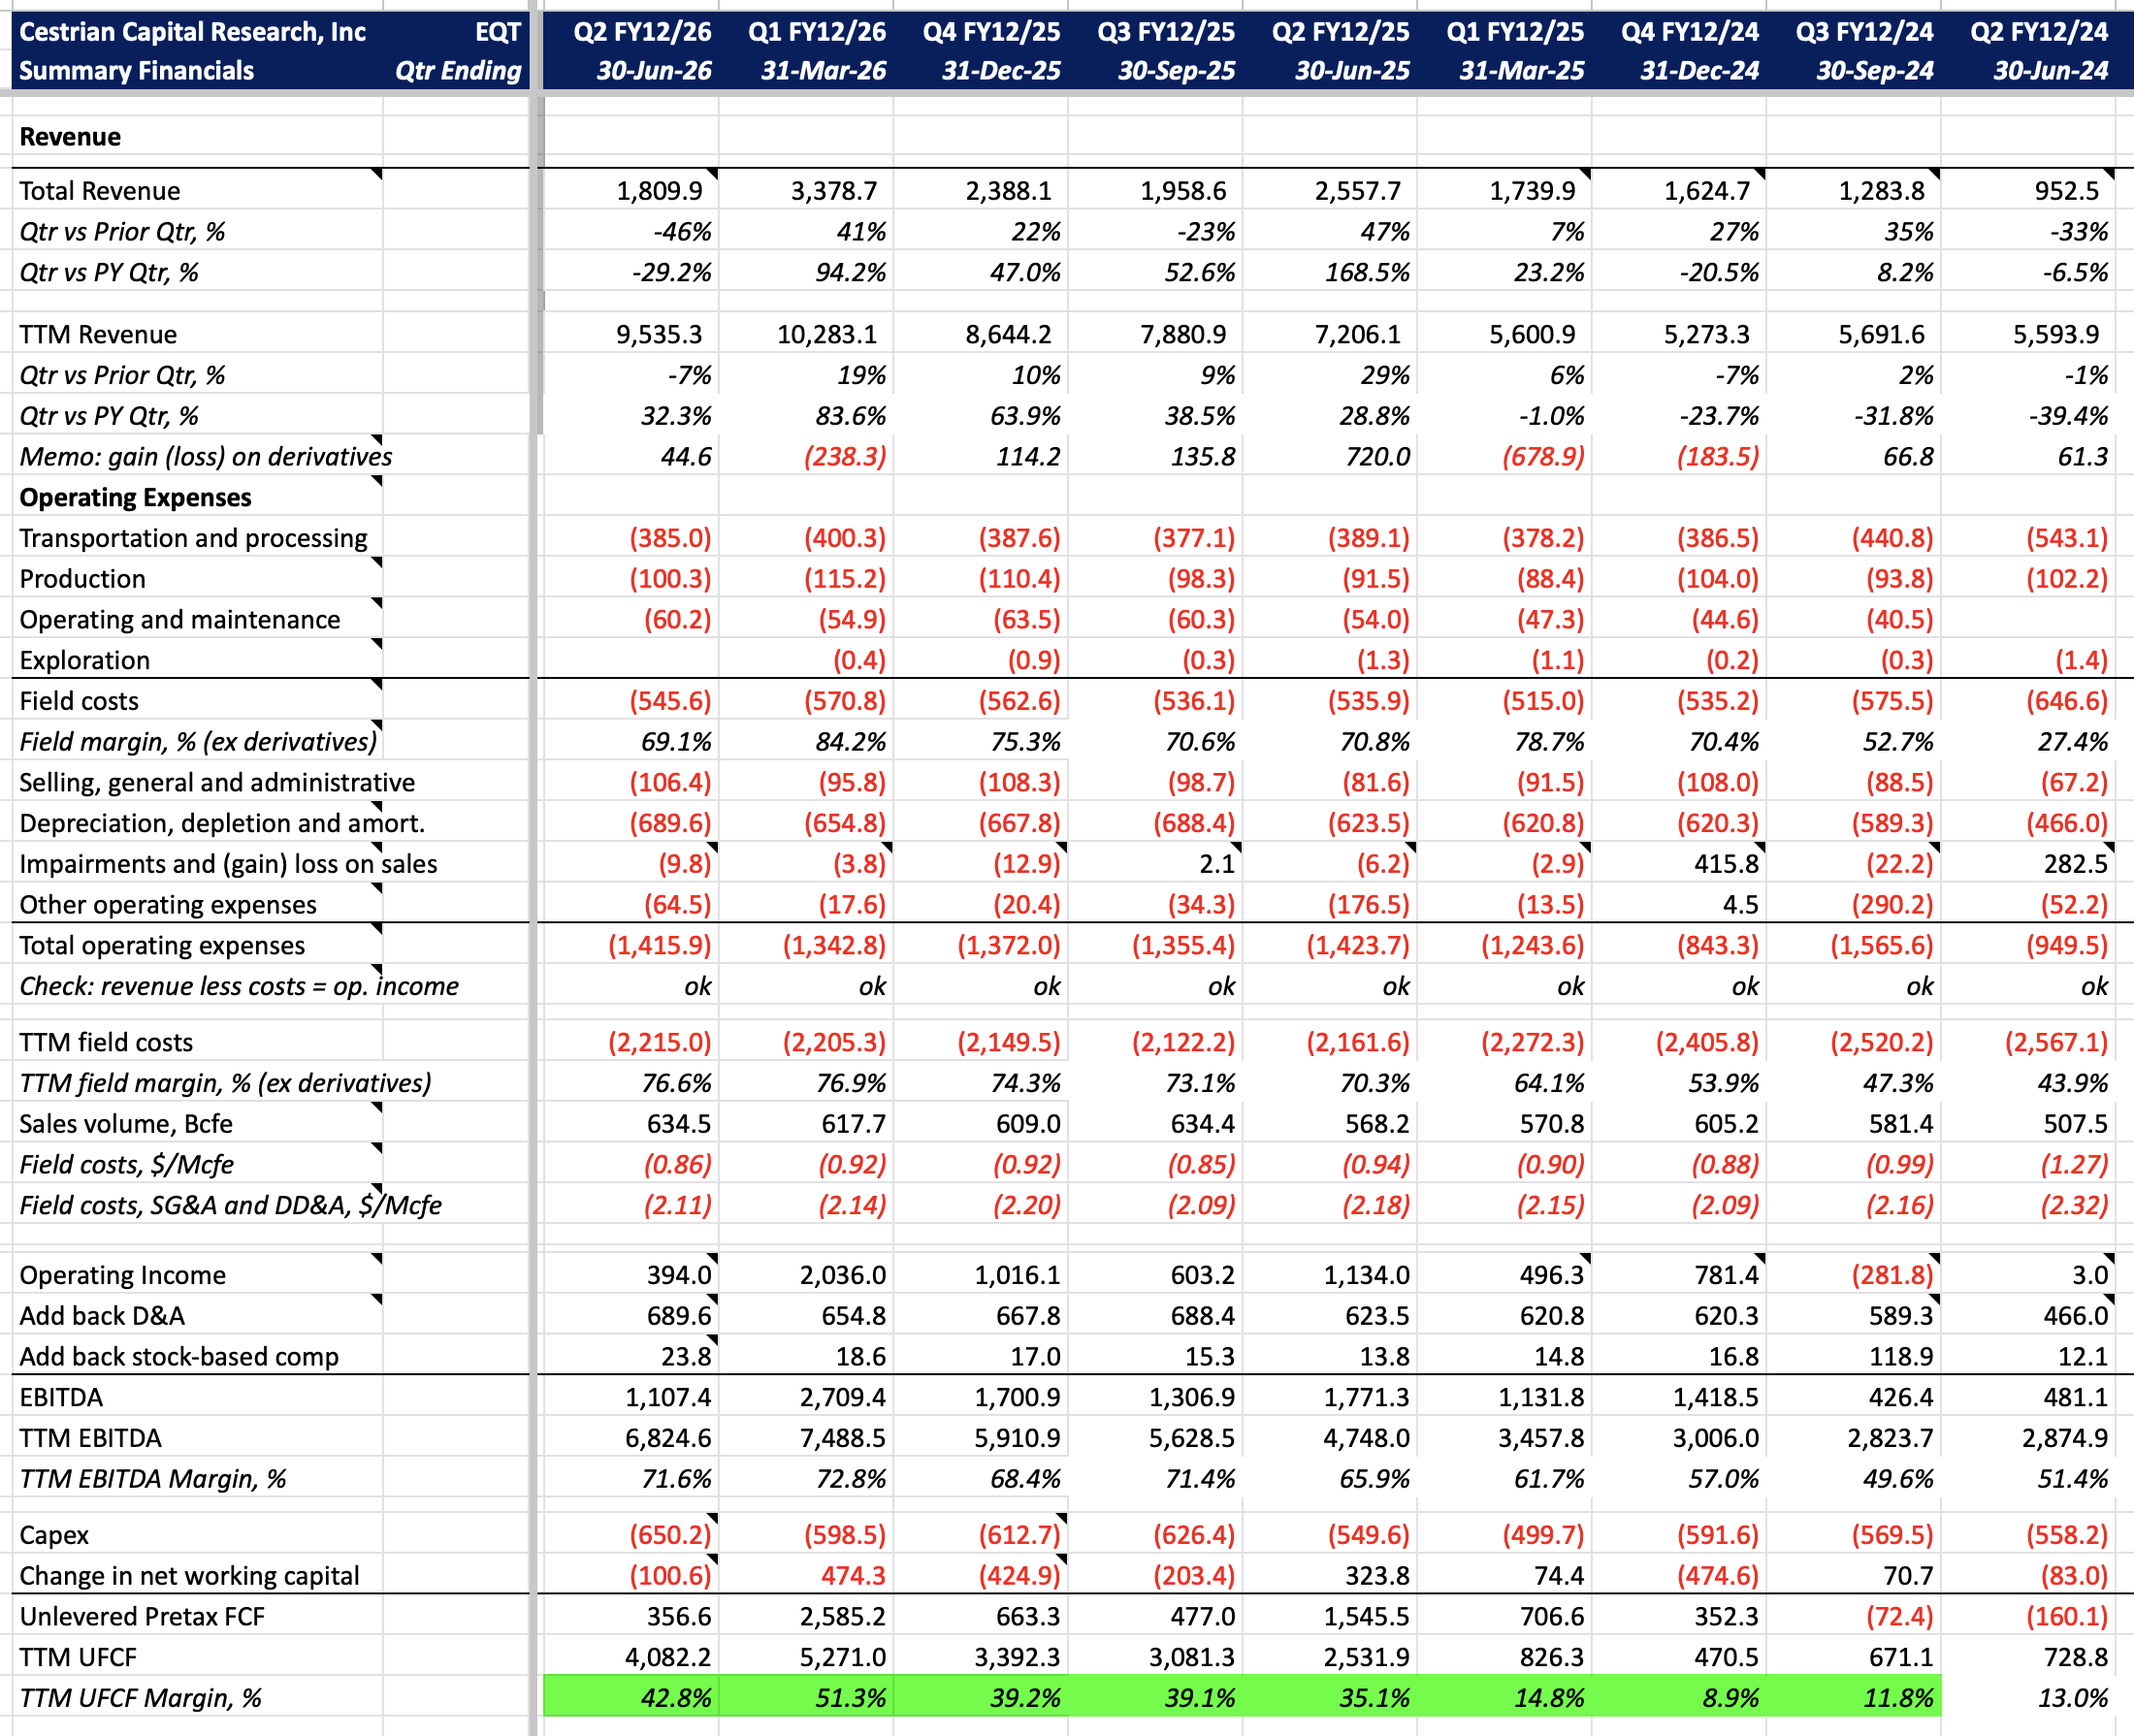
EQT remains tied to roughly $3 Henry Hub gas despite European prices near $23 per MMBtu, with US LNG export capacity limiting overseas…
Microsoft plans to rebuild Xbox after FY2026 through studio cuts, higher hardware prices, Game Pass growth, exclusive releases and the 2028…
 Khaveen Investments 2 clicks
Stratus Properties liquidates Austin real estate below projected distributions, while Atlantic Lithium and Intermex await approvals for…
Beyond Meat’s Q2 2026 revenue fell 8.2% as U.S. retail and foodservice volumes declined, while a flatter, not inverted, Treasury curve…
Research Roundup covers AAON's data-center cooling ramp, Knife River's margin recovery, ChronoScale's Microsoft-backed neocloud buildout…
Annaly Capital Management’s rate swaps and MBS expansion lifted earnings available for distribution 28% year over year, supporting its…
 Andres Veurink
Asia's elevator boom favors maintenance and modernization providers, with Otis deriving nearly 90% of operating profit from after-sales…
 SEER · long
SEER Inc became a founder-offer special situation just before publication.
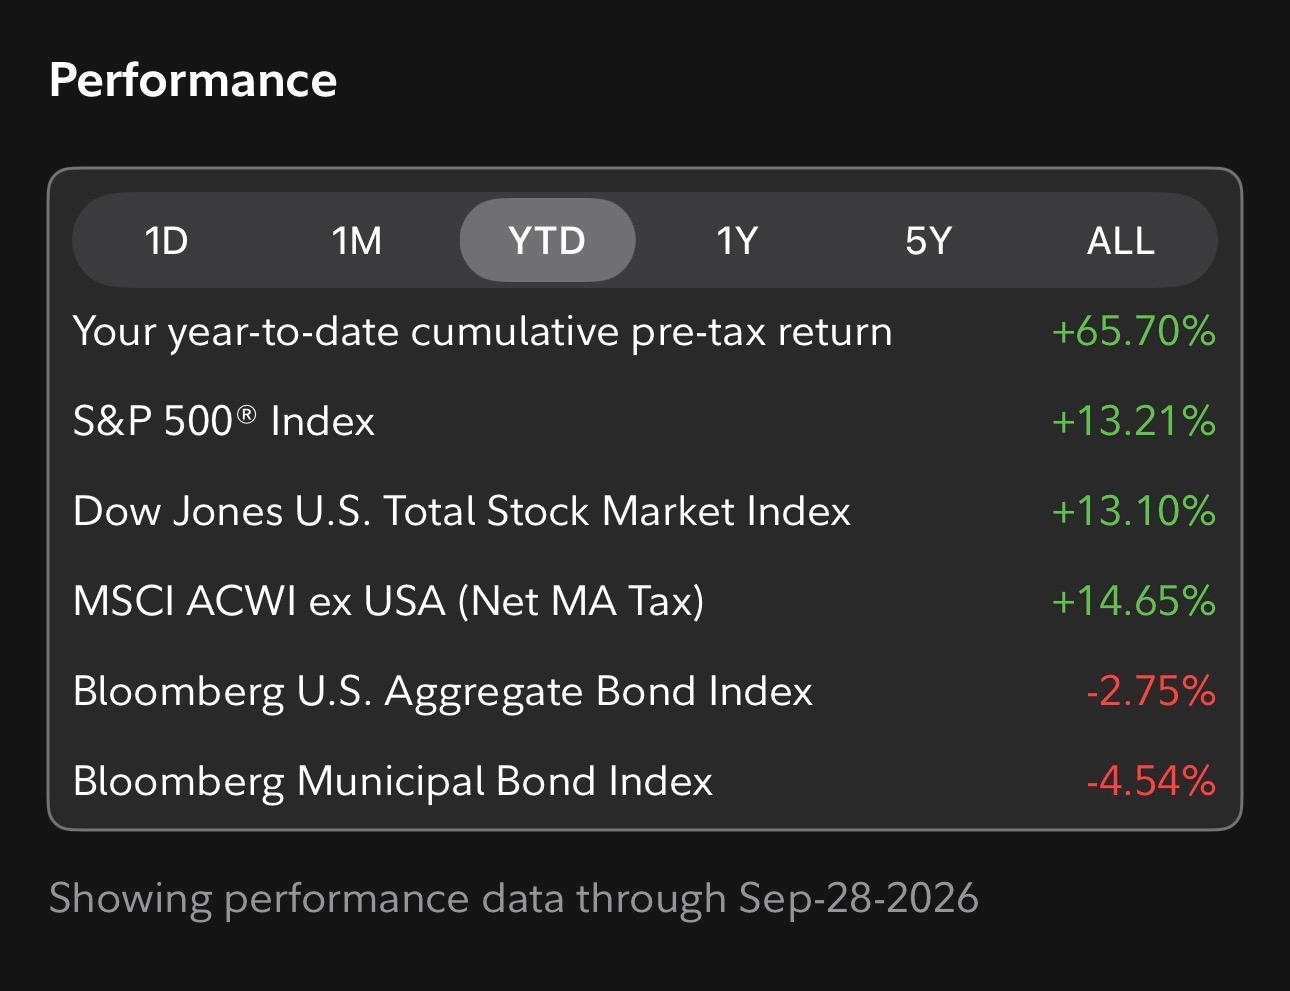
Portfolio returned 65.7% through September 28 versus the S&P 500’s 13.2%, while backing Tourmaline, EQT, Athabasca and SLB on gas demand…
FTAI Aviation’s engine-exchange model swaps CFM56 engines in days rather than 200-day overhauls, driving Aerospace Products adjusted EBITDA…

Meta’s Enterprise Platform creates a third-party compute outlet, reducing the cost of overbuilding AI infrastructure while adding…
Archer Aviation's Insitu, Wisk and SkyGrid acquisitions add military and drone revenue, cutting FAA-certification dependence and leaving…
 The Alpha Analyst 2 clicks
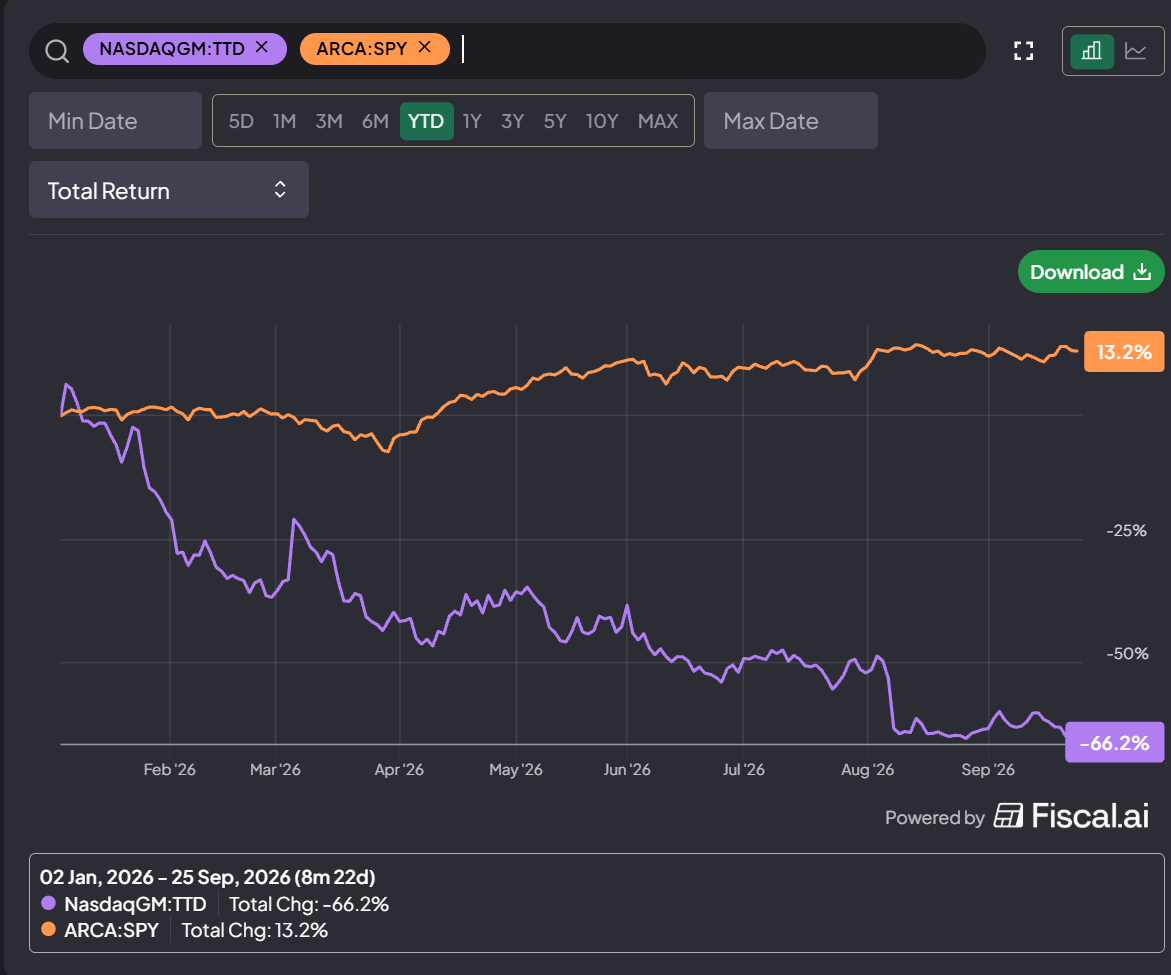
The Trade Desk’s CEO received a new 10-year option package targeting $105 per share as the company seeks shareholder approval to reprice…
Cullinan Therapeutics plans December 2026 autoimmune updates for CLN-978, while zipalertinib awaits an FDA decision in previously treated…
 Myriam Alvarez 2 clicks
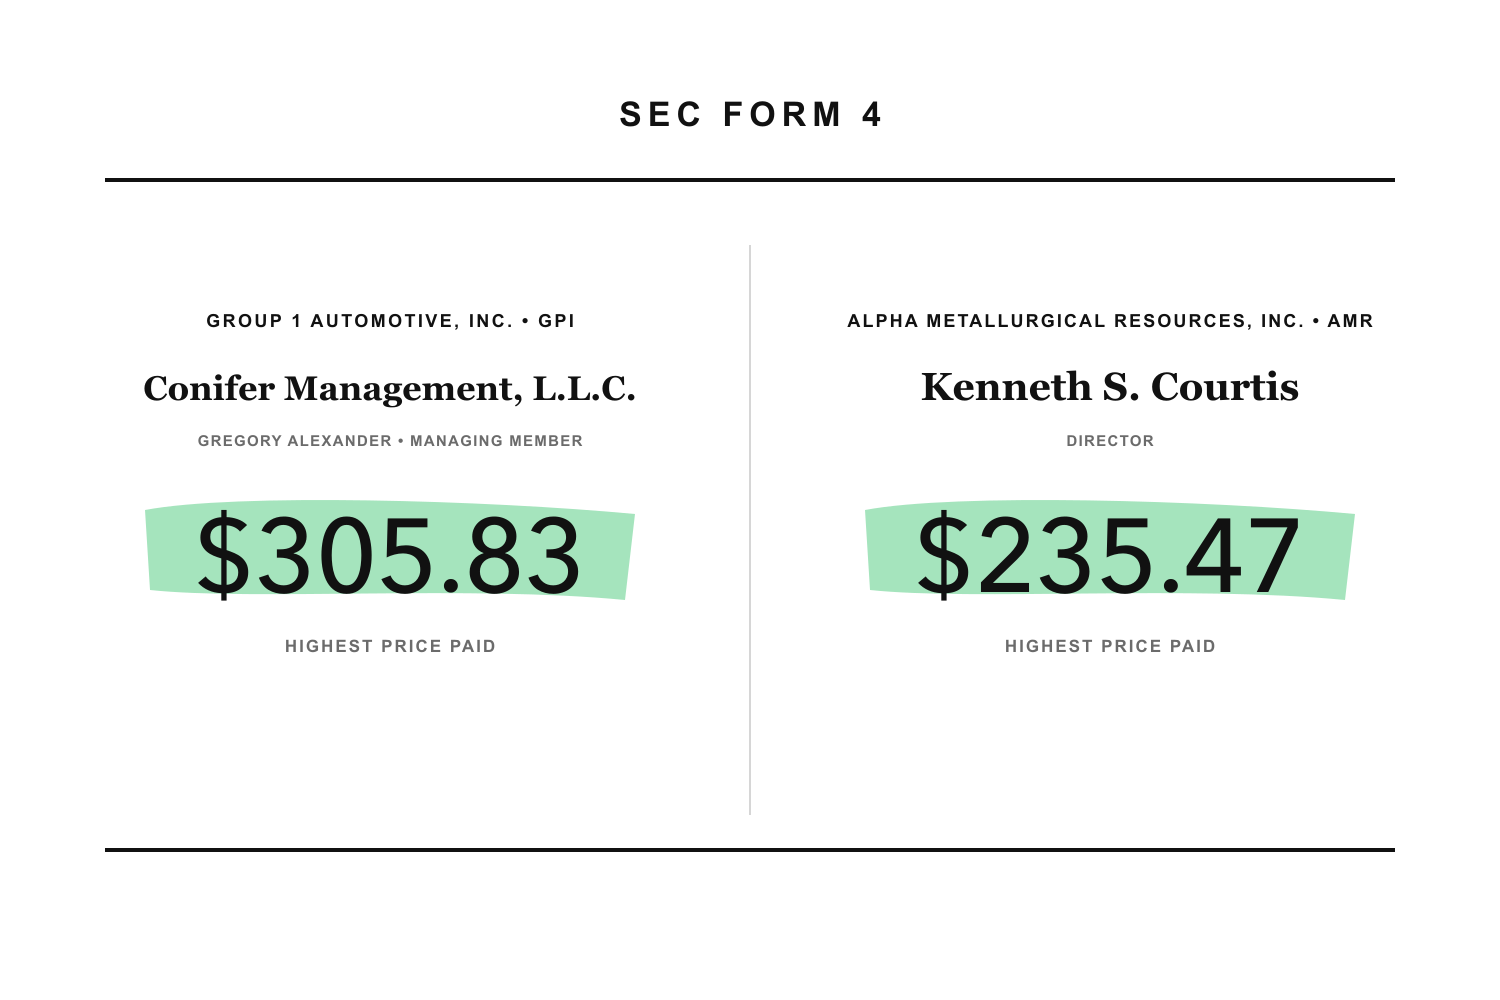
Alpha Metallurgical Resources director Ken Courtis bought $10.5 million above $190 after a blackout lifted, while Conifer’s 12.7% Group 1…
Monte Investments upgrades Karman Holdings to Buy with a $133 target after a 65% drawdown, citing 28.83x EV/aEBITDA and governance changes.
Robinhood’s long-term value rests on retaining customer assets and becoming a primary financial platform beyond trading.
 Thomas Veth 1 click
Every publication on this site, hand-picked.
 Albert Anthony Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.