Toll roads in the sky
Asia's elevator boom favors maintenance and modernization providers, with Otis deriving nearly 90% of operating profit from after-sales services rather than new installations.
Asia's elevator boom favors maintenance and modernization providers, with Otis deriving nearly 90% of operating profit from after-sales services rather than new installations.
Meanwhile disintermediation by OEMs going direct is accelerating. See recent commentary from partners $CSCO, $PANW $DELL, etc. $PLUS has zero discernable benefit from $NVDA and AI.
Answer: aggressive revenue booking, financing sales, selling products at/ below cost to boost revenue and hoping to “then try to build it back up over time” per CEO. Contrast $PLUS performance w competitor and industry leader $CDW.
$PLUS Numbers don’t add up. 50% sales $CSCO product (sales -13% MRQ, guided -11%). MRQ $PLUS sales +13% (reported yesterday). Earnings call question: “OEM Cisco have talked about bottlenecks, weak orders. You’ve been unscathed…how are you outperforming the market significantly?”
$EXLS Highly innovative founder-CEO rapidly taking share w AI-based services. High-teens topline growth w expanding margins, higher value-add mix to attractive end-markets. 17x P/E yet to reflect business transformation. 100% FCF to buybacks. Winning customers from $ACN $DXC $WIT
8/ There is a lot more to talk about (24% sequential increase in new home sales, ward village condo sales etc.) but I am hungry. So to wrap up, if you're selling $HHH on this quarterly report you do not understand what you own and I will be buying your shares at tomorrow's open.
1/ So first things first, $HHH missed on top and bottom line. Am I concerned? Absolutely not. Value was created for shareholders and I'll briefly explain why...
$OII Niche leader in subsea robotics at 12x P/E. Offshore rig count accelerating (70% share), A&D growing DD, new autonomous tech a major growth driver in other end markets (lifts, etc). Investor day next week will showcase products and new LT targets. >50% NTM upside, IMO.
@TheMuffinMan28 SRS is a PE rollout, bit of a hodgepodge of assets. Concentration in landscaping, pool and roofing. No exclusive relationships (GMS is for $AWI, regional duopoly across most categories). End customers are small homebuilders (more competitive, less scale benefit for distributors).
Archer Aviation's Insitu, Wisk and SkyGrid acquisitions add military and drone revenue, cutting FAA-certification dependence and leaving…
 The Alpha Analyst 2 clicks
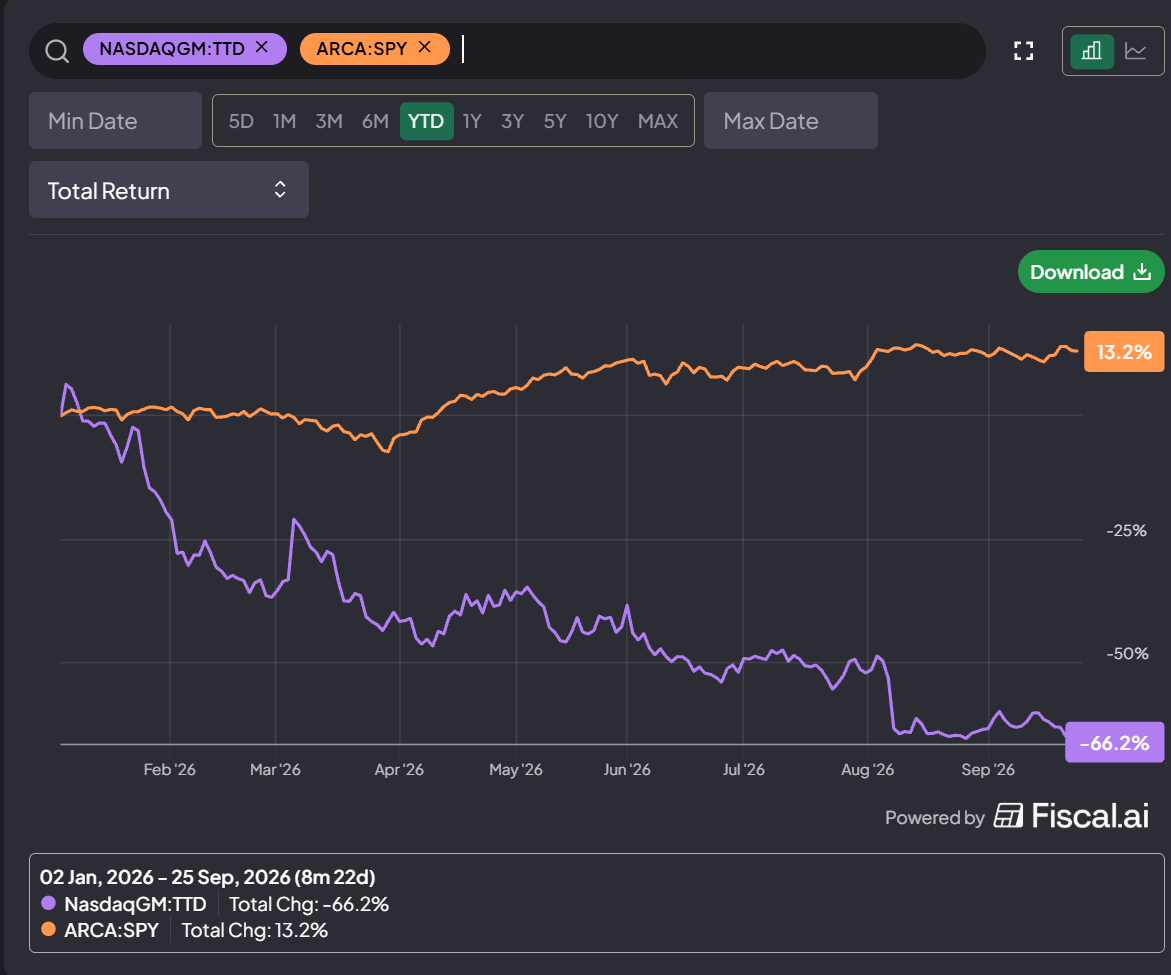
The Trade Desk’s CEO received a new 10-year option package targeting $105 per share as the company seeks shareholder approval to reprice…
Cullinan Therapeutics plans December 2026 autoimmune updates for CLN-978, while zipalertinib awaits an FDA decision in previously treated…
 Myriam Alvarez 2 clicks
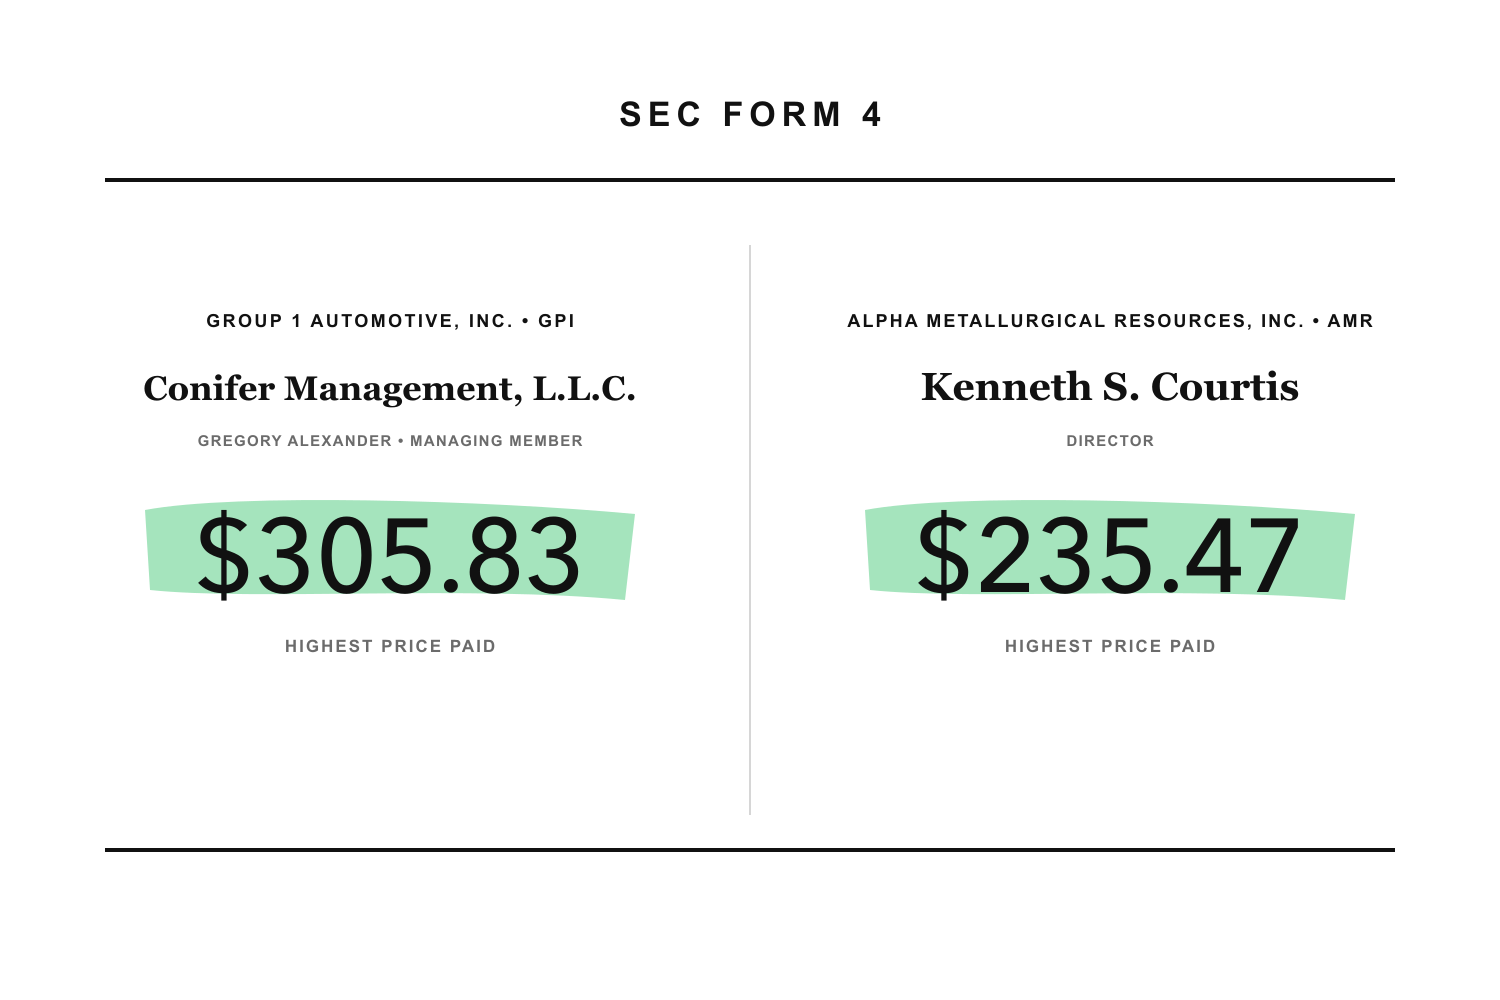
Alpha Metallurgical Resources director Ken Courtis bought $10.5 million above $190 after a blackout lifted, while Conifer’s 12.7% Group 1…
Monte Investments upgrades Karman Holdings to Buy with a $133 target after a 65% drawdown, citing 28.83x EV/aEBITDA and governance changes.
Robinhood’s long-term value rests on retaining customer assets and becoming a primary financial platform beyond trading.
 Thomas Veth 1 click
Cisco’s Sam Badri says roughly 90% of AI users remain at basic prompting, with few advancing to skills files or AI agents.

Zscaler posted 25% Q4 revenue growth to $898.2 million and a 24.3% operating margin, but guided FY27 growth down to 16.6%-17.5% as free…
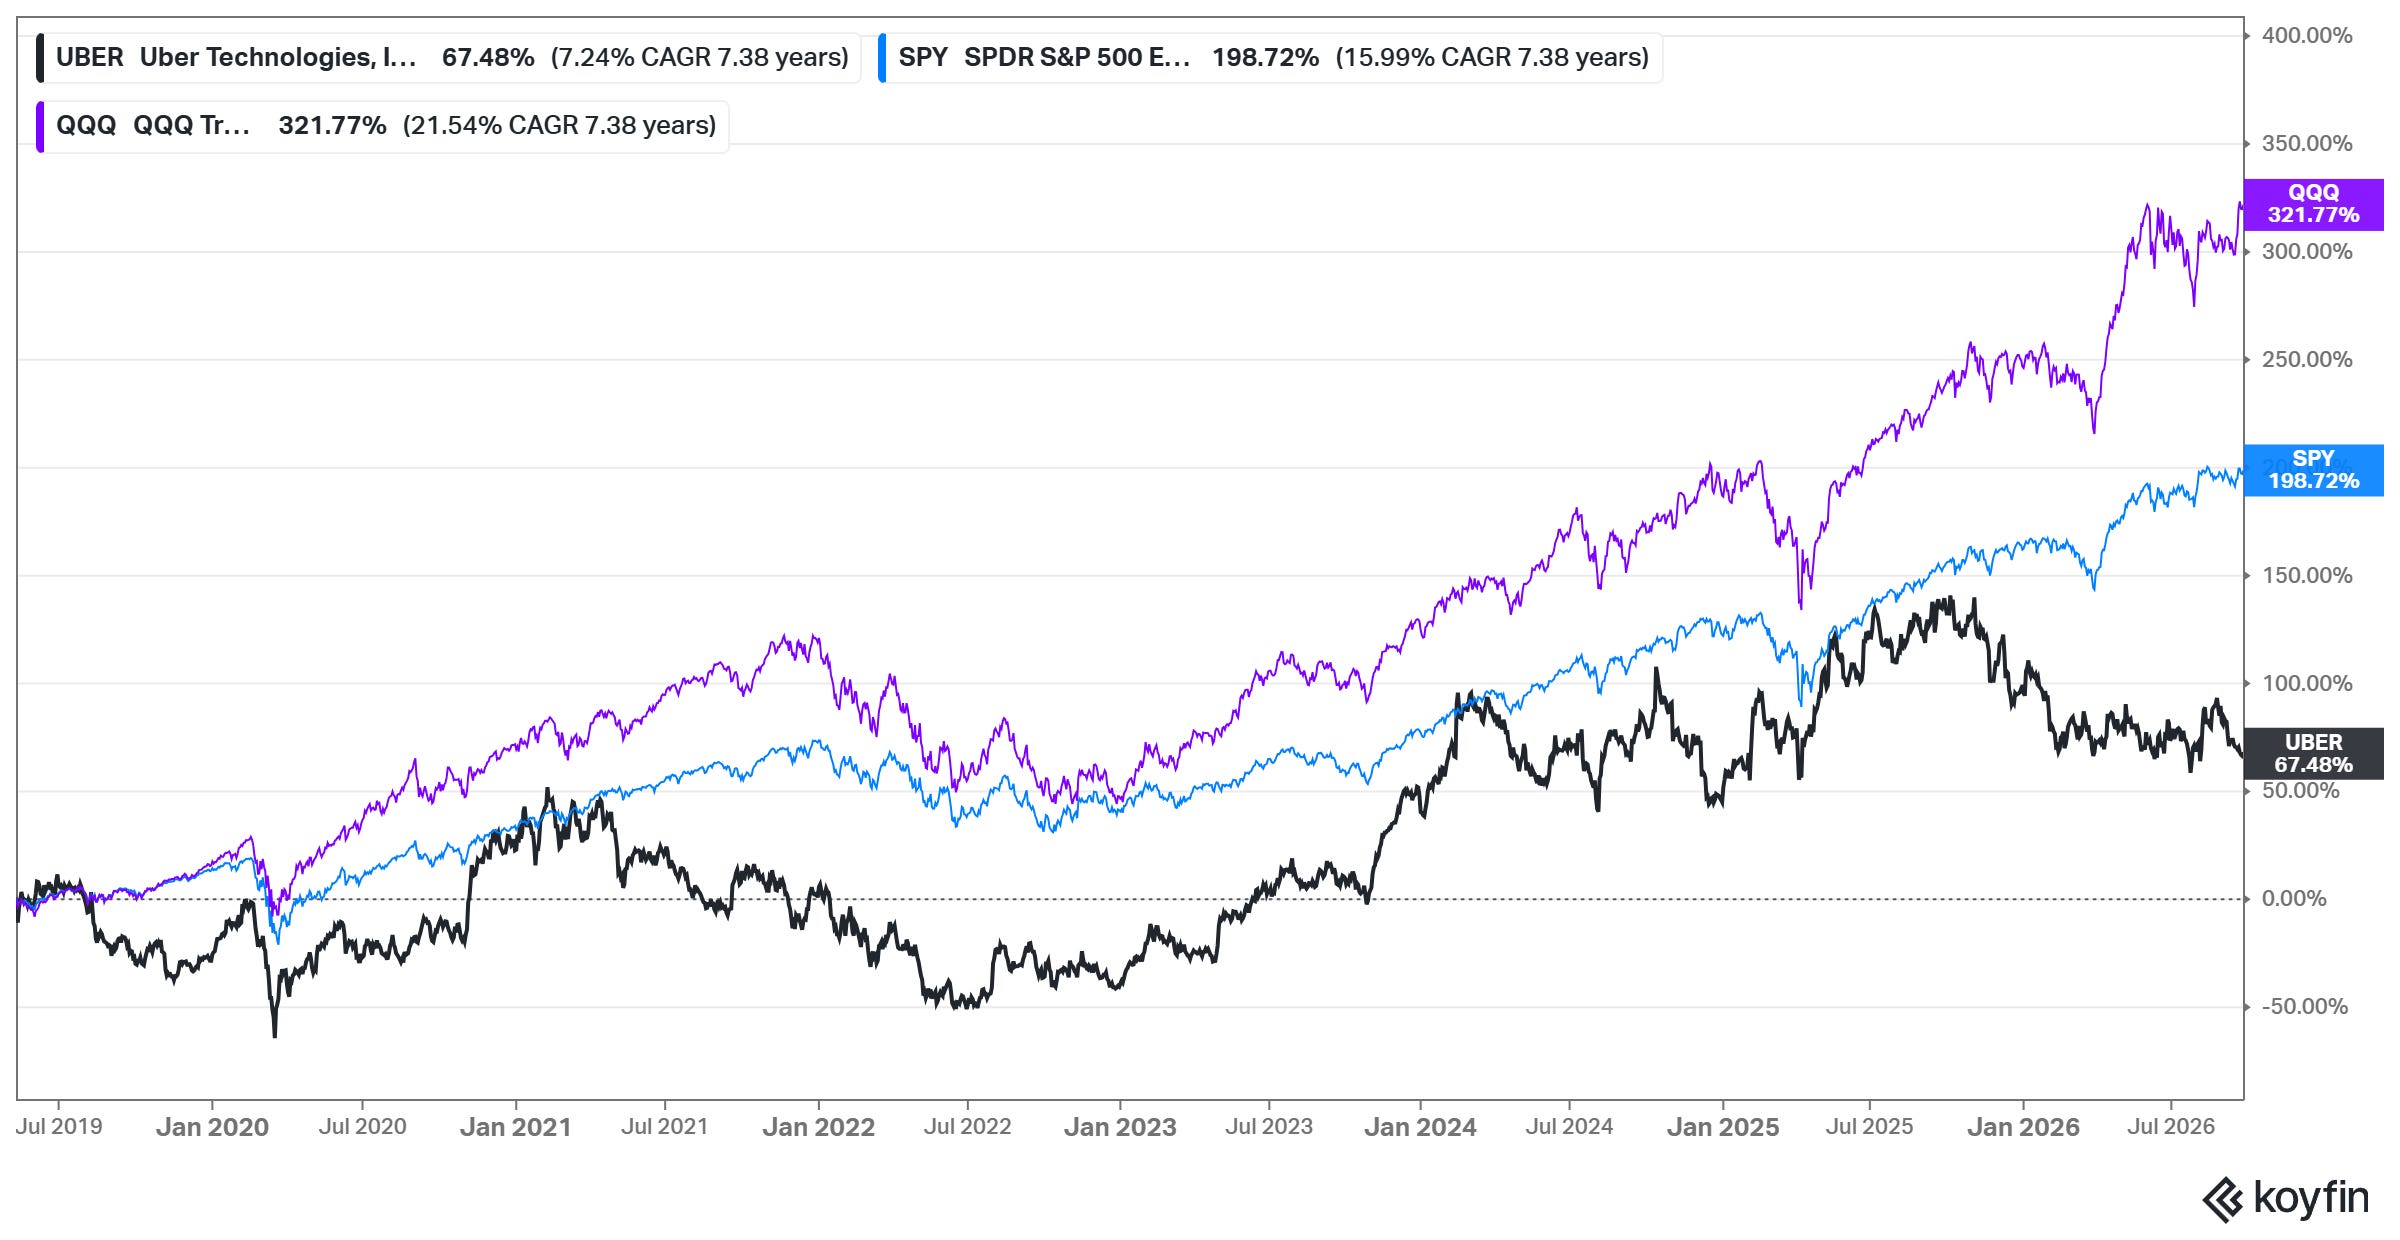
Uber's $193 billion in gross bookings and $10 billion in free cash flow contrast with modest stock gains as autonomous vehicles and…

Veeva Systems moved VEEV to Distribute at $277 after a 41% gain in less than two months, despite Q2 revenue growth of 18% and 45% EBITDA…
Gentherm’s Oct. 1 Reverse Morris Trust with Modine adds commercial and off-highway operations, leaving THRM at 7.4x pro forma EBITDA with…
QuantumScape faces a 2029 PowerCo plant delay, reduced partner commitments and no revenue, with a scenario-weighted $2.12 per-share…
 Bears of Wall Street
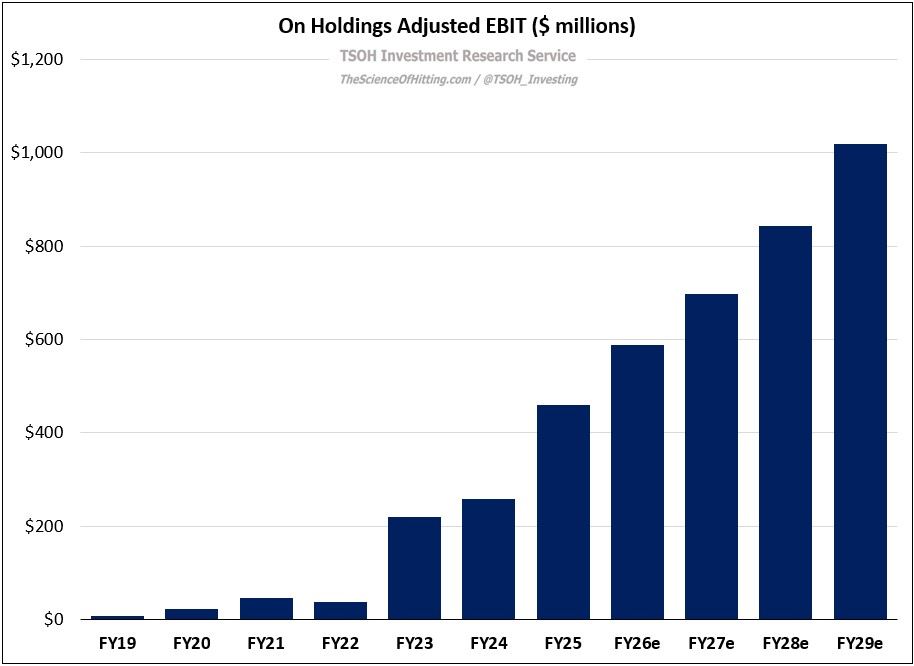
On Holdings targets premium growth through 2029, using LightSpray soccer cleats and higher pricing, with ASPs rising from $145 to $170…
Oracle faces rising credit and spending risks as OpenAI-linked backlog, Project Jupiter delays and higher component costs threaten FY27…
 Tech Stock Pros 2 clicks
Micron and Nike earnings headline a weekly briefing featuring Exor’s NAV discount, Meta’s Muse agent and Bellway’s UK housing valuation.
 SFIX · long
Stitch Fix’s 2017 IPO rested on overly ambitious long-term growth expectations and an unrealistic definition of its addressable market.
NAIC oversight missed Delaware Life’s $13.34 billion affiliated-bond exposure and permits capital treatment that props up Brighthouse’s…
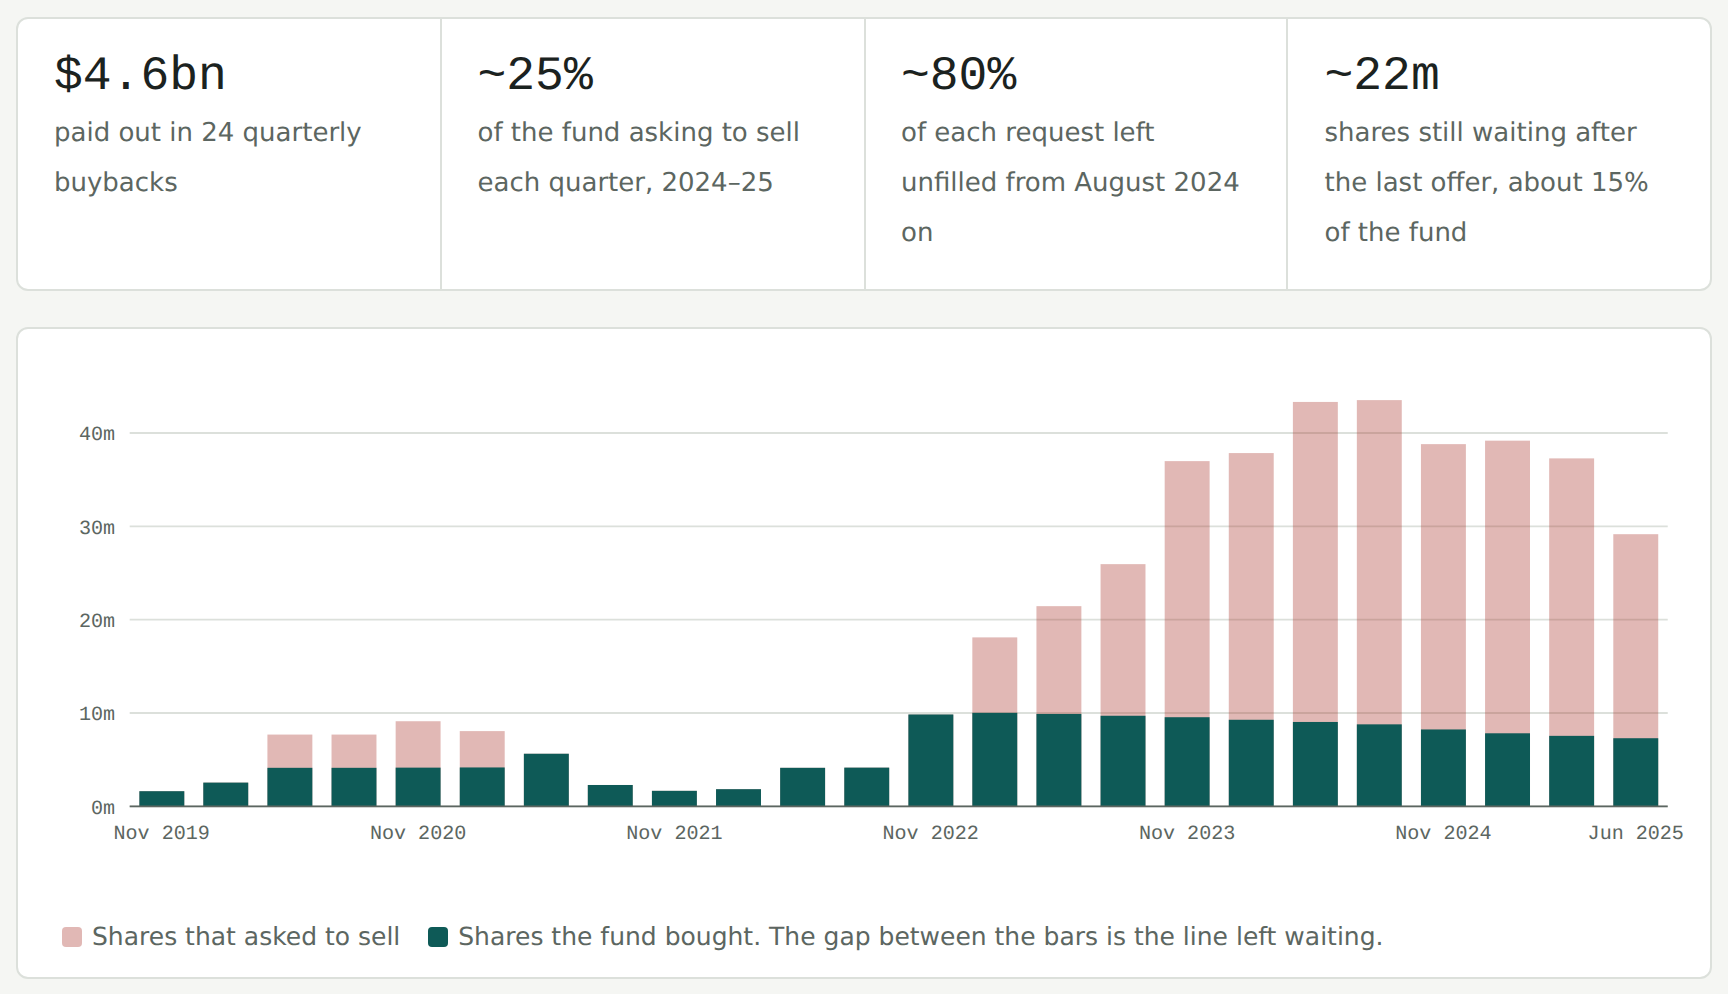
BPRE trades 45% below NAV as Saba and Bulldog press for buybacks or a manager change, challenging Bluerock’s incentive to preserve…
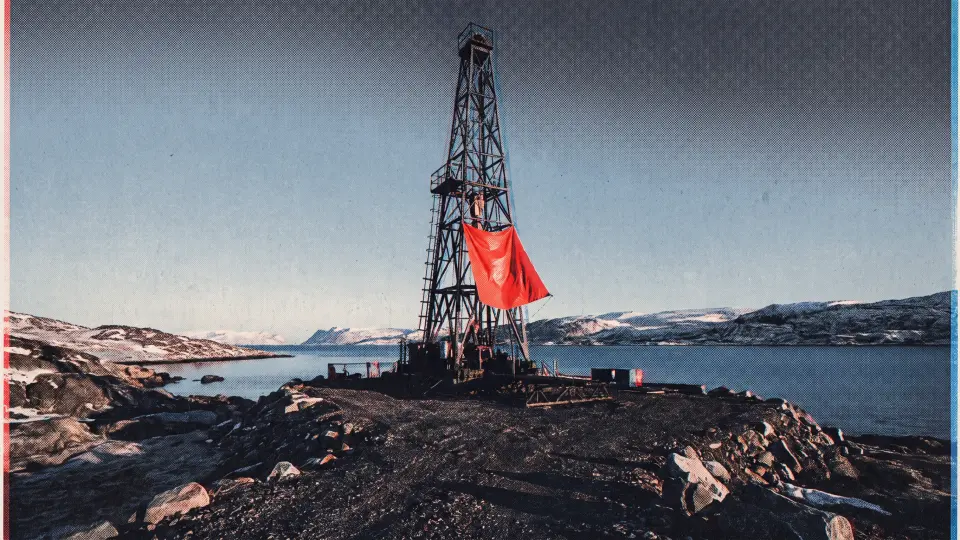
Greenland Energy Company holds 2.1 million acres in the Jameson Land Basin, but drilling permits, political risk and warrant dilution cloud…
 Ron Ferrie
Hindsight Capital tests crisis-era investment decisions using anonymized company financials, including TransDigm, Halma and Texas Pacific…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.