No Cap? Currently Capped by Three Hundredths of a Percent: Medtronic’s MiniMed Split-Off Odd Lot
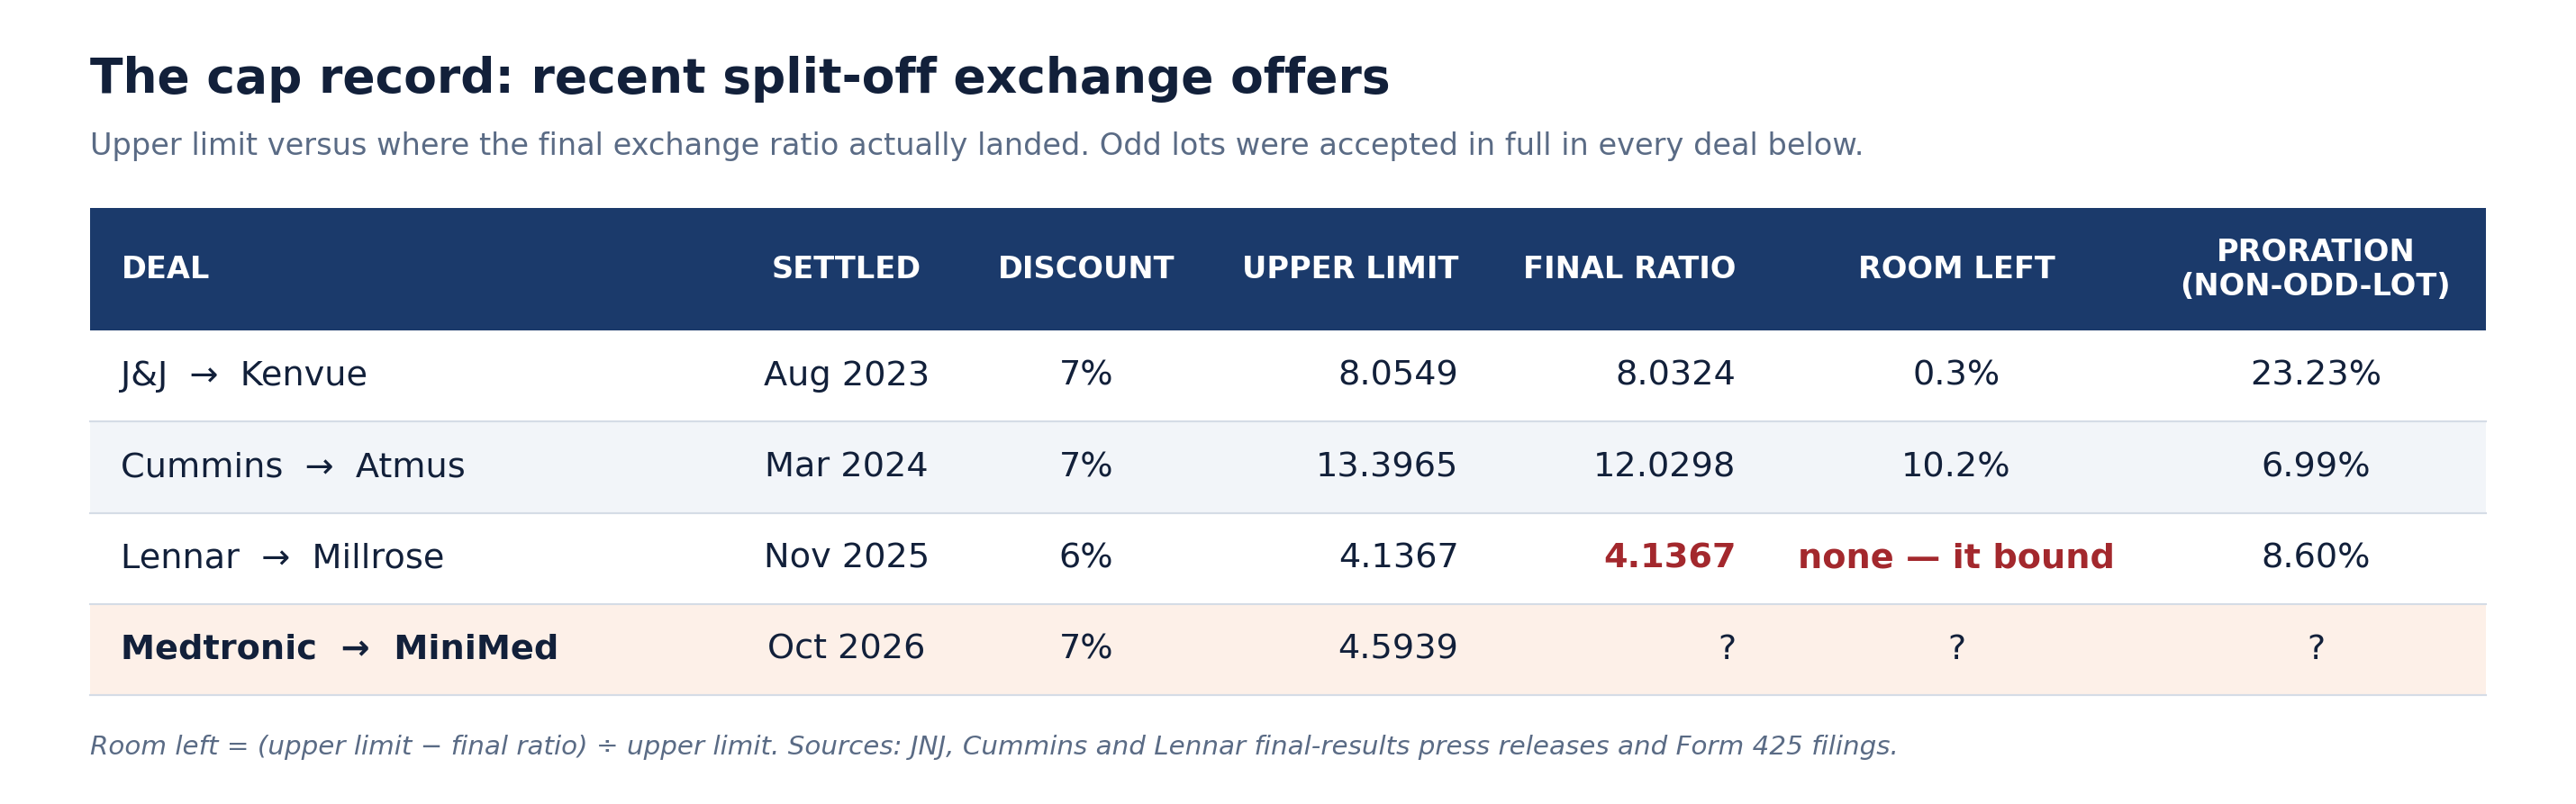
Medtronic’s MiniMed split-off gives odd-lot MDT holders priority on a 7% discounted exchange, but a 4.5939-share cap has begun reducing the payoff.
Medtronic’s MiniMed split-off gives odd-lot MDT holders priority on a 7% discounted exchange, but a 4.5939-share cap has begun reducing the payoff.
what's the future of lead gen comparison websites for insurance like $qnst which owns among other websites, https://t.co/DJYACtuB4d! i could not resist the question https://t.co/DhTidY6YkT
David Orr @orrdavid of Militia Capital will be a featured guest speaker at our upcoming Ideas & Networking conference in NYC on October 1st… come hear me interview David live! $ORR More info here (less than 30 spots remain): https://t.co/IEMtdrPvyf https://t.co/rd2DLEmJwy
@LepoulpePoulpo $TLN has always had an issue about which bucket it falls in: (I) the IPP bucket ($VST, $CEG, etc.) or the (II) ShitCo Nuclear Bucket ($OKLO, $SMR, etc.) Traders can’t make up their mind…
Another 10,000 share buy from the $ALTO Chairman 👀 https://t.co/pPgkaIYFgG
@ethanrkho @taobanker @orrdavid Bought a little more $ORR today. I'd own a lot more if I didn't already correlate very strongly with it.
@dstressedcos I think it’s a question of what multiple to apply to $APTV post-spin…
Cestrian initiated Joby Aviation at Accumulate and upgraded Applied Materials and Broadcom to Accumulate for the week ended 11 September…

Adobe’s fiscal 3Q26 revenue grew 13%, while ARR growth was about 9.3% excluding Semrush.
Enel Chile uses battery storage and grid management to turn renewable oversupply into flexibility, lifting H1 2026 EBITDA 3.9% and net…
 Ryan Canady 4 clicks
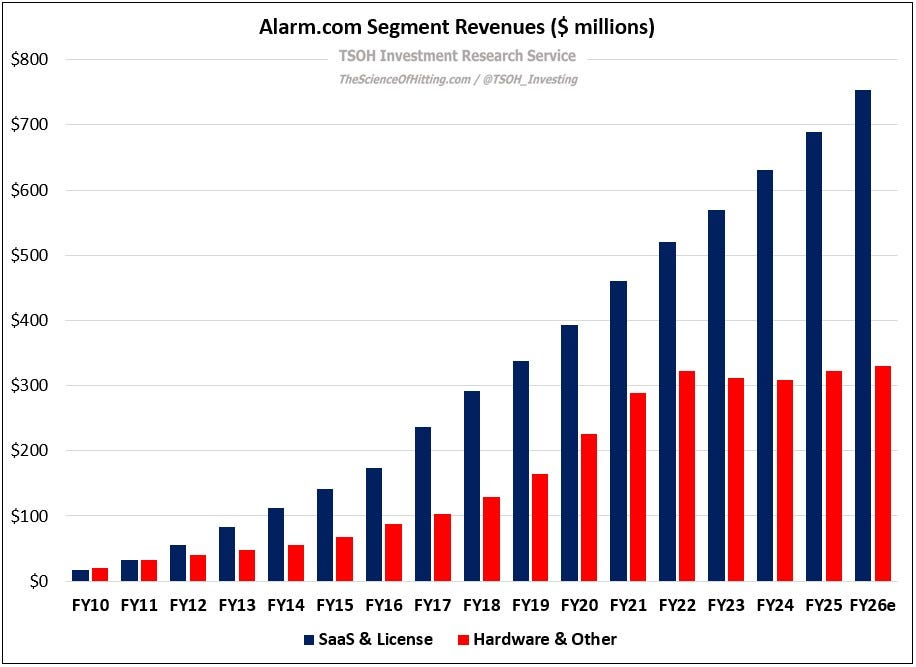
Alarm.com, founded after CEO Steve Trundle’s bad home-security experience, has fallen from $105 in 2020 to about $55, testing whether…
CHPY pairs a roughly 40% distribution rate with capped weekly upside for investors retaining semiconductor exposure amid Anthropic's AI…
 Geneva Investor 1 click
Zentek initiation report.
CVD Equipment is winding down manufacturing, cutting half its staff and weighing liquidation, with $23.5 million of cash and a…
Genius Sports aims to turn official sports data into AI-driven, real-time advertising, with media and ads already about 40% of revenue.
Oak Bloke’s 2026 picks have returned 37% in GBP, with AltynGold, Geiger Counter, Silvercorp and China-focused trusts still rated buys…
Nintendo expects software, digital sales and character licensing to drive growth, with FY2027 revenue forecast at ¥2.05 trillion and…
 LL Insights
 ANAB · long
AnaptysBio is pitched for a 50% to 80% return over four to six weeks after its April 2026 taxable spin-off of R&D-heavy operations.
CME perpetual-futures activity is tested against more than 240,000 CFTC data points on open interest and dealer positioning.
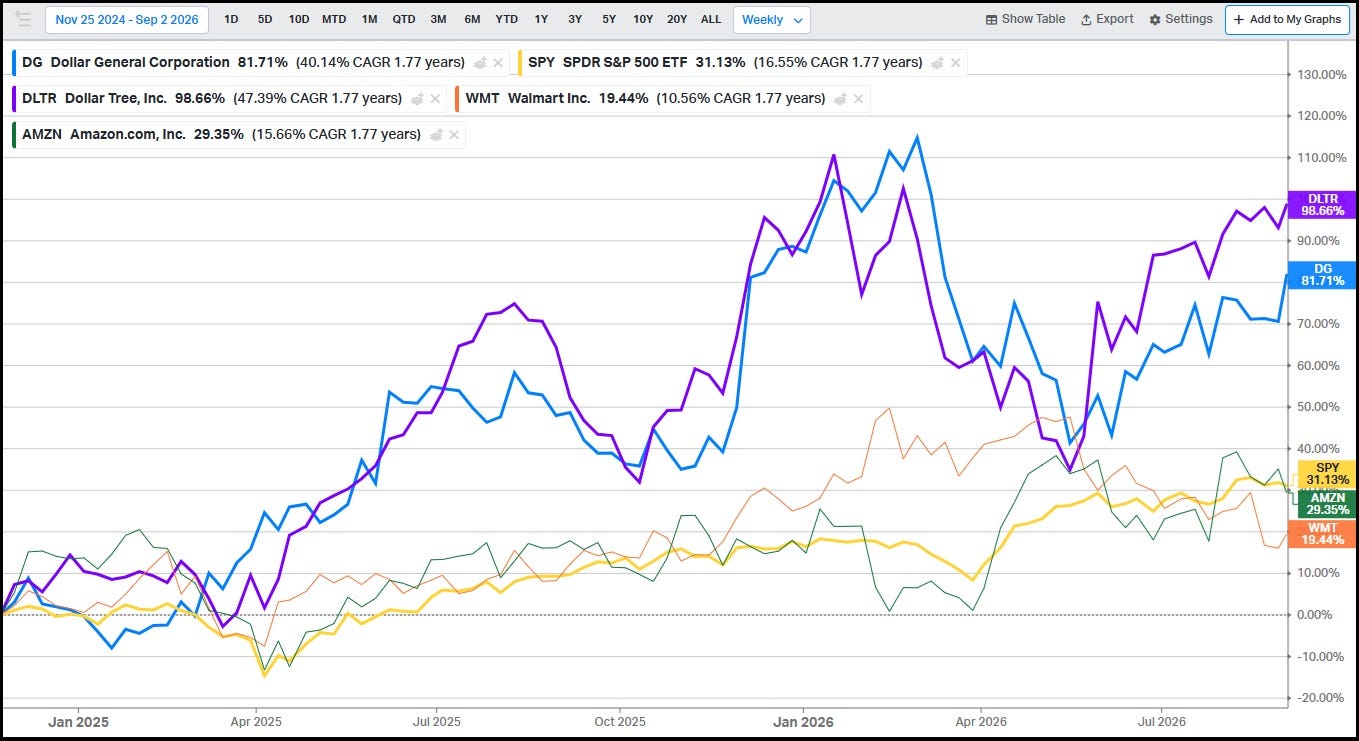
Dollar General’s Q2 FY26 comparable sales rose 3.5%, beating Walmart U.S.
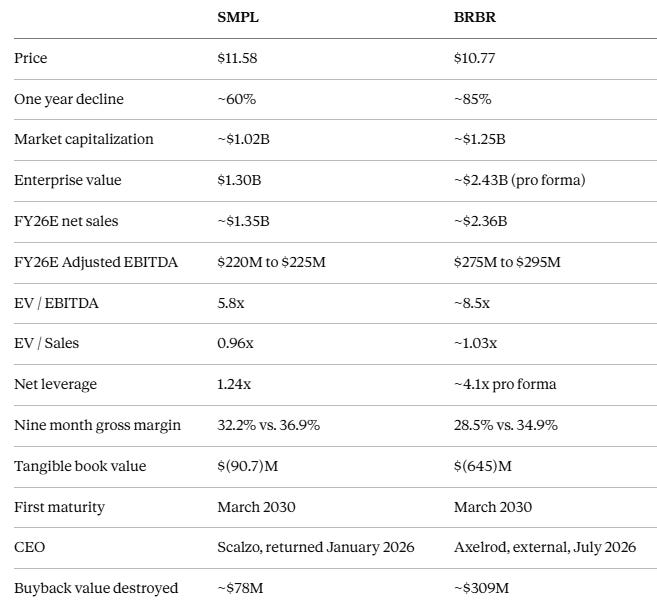
Two U.S. protein-snacking companies lost $6 billion in market value as impairments, inventory growth and margin pressure test whether the…
DoorDash’s delivery economics rely on customer tips and flexible labor, while rising courier costs make autonomous delivery central to…
IREN’s AI contracts now include customer prepayments covering 45% to 55% of GPU CapEx, while three-year pricing has risen 125% since…
 Quantryon Capital 5 clicks
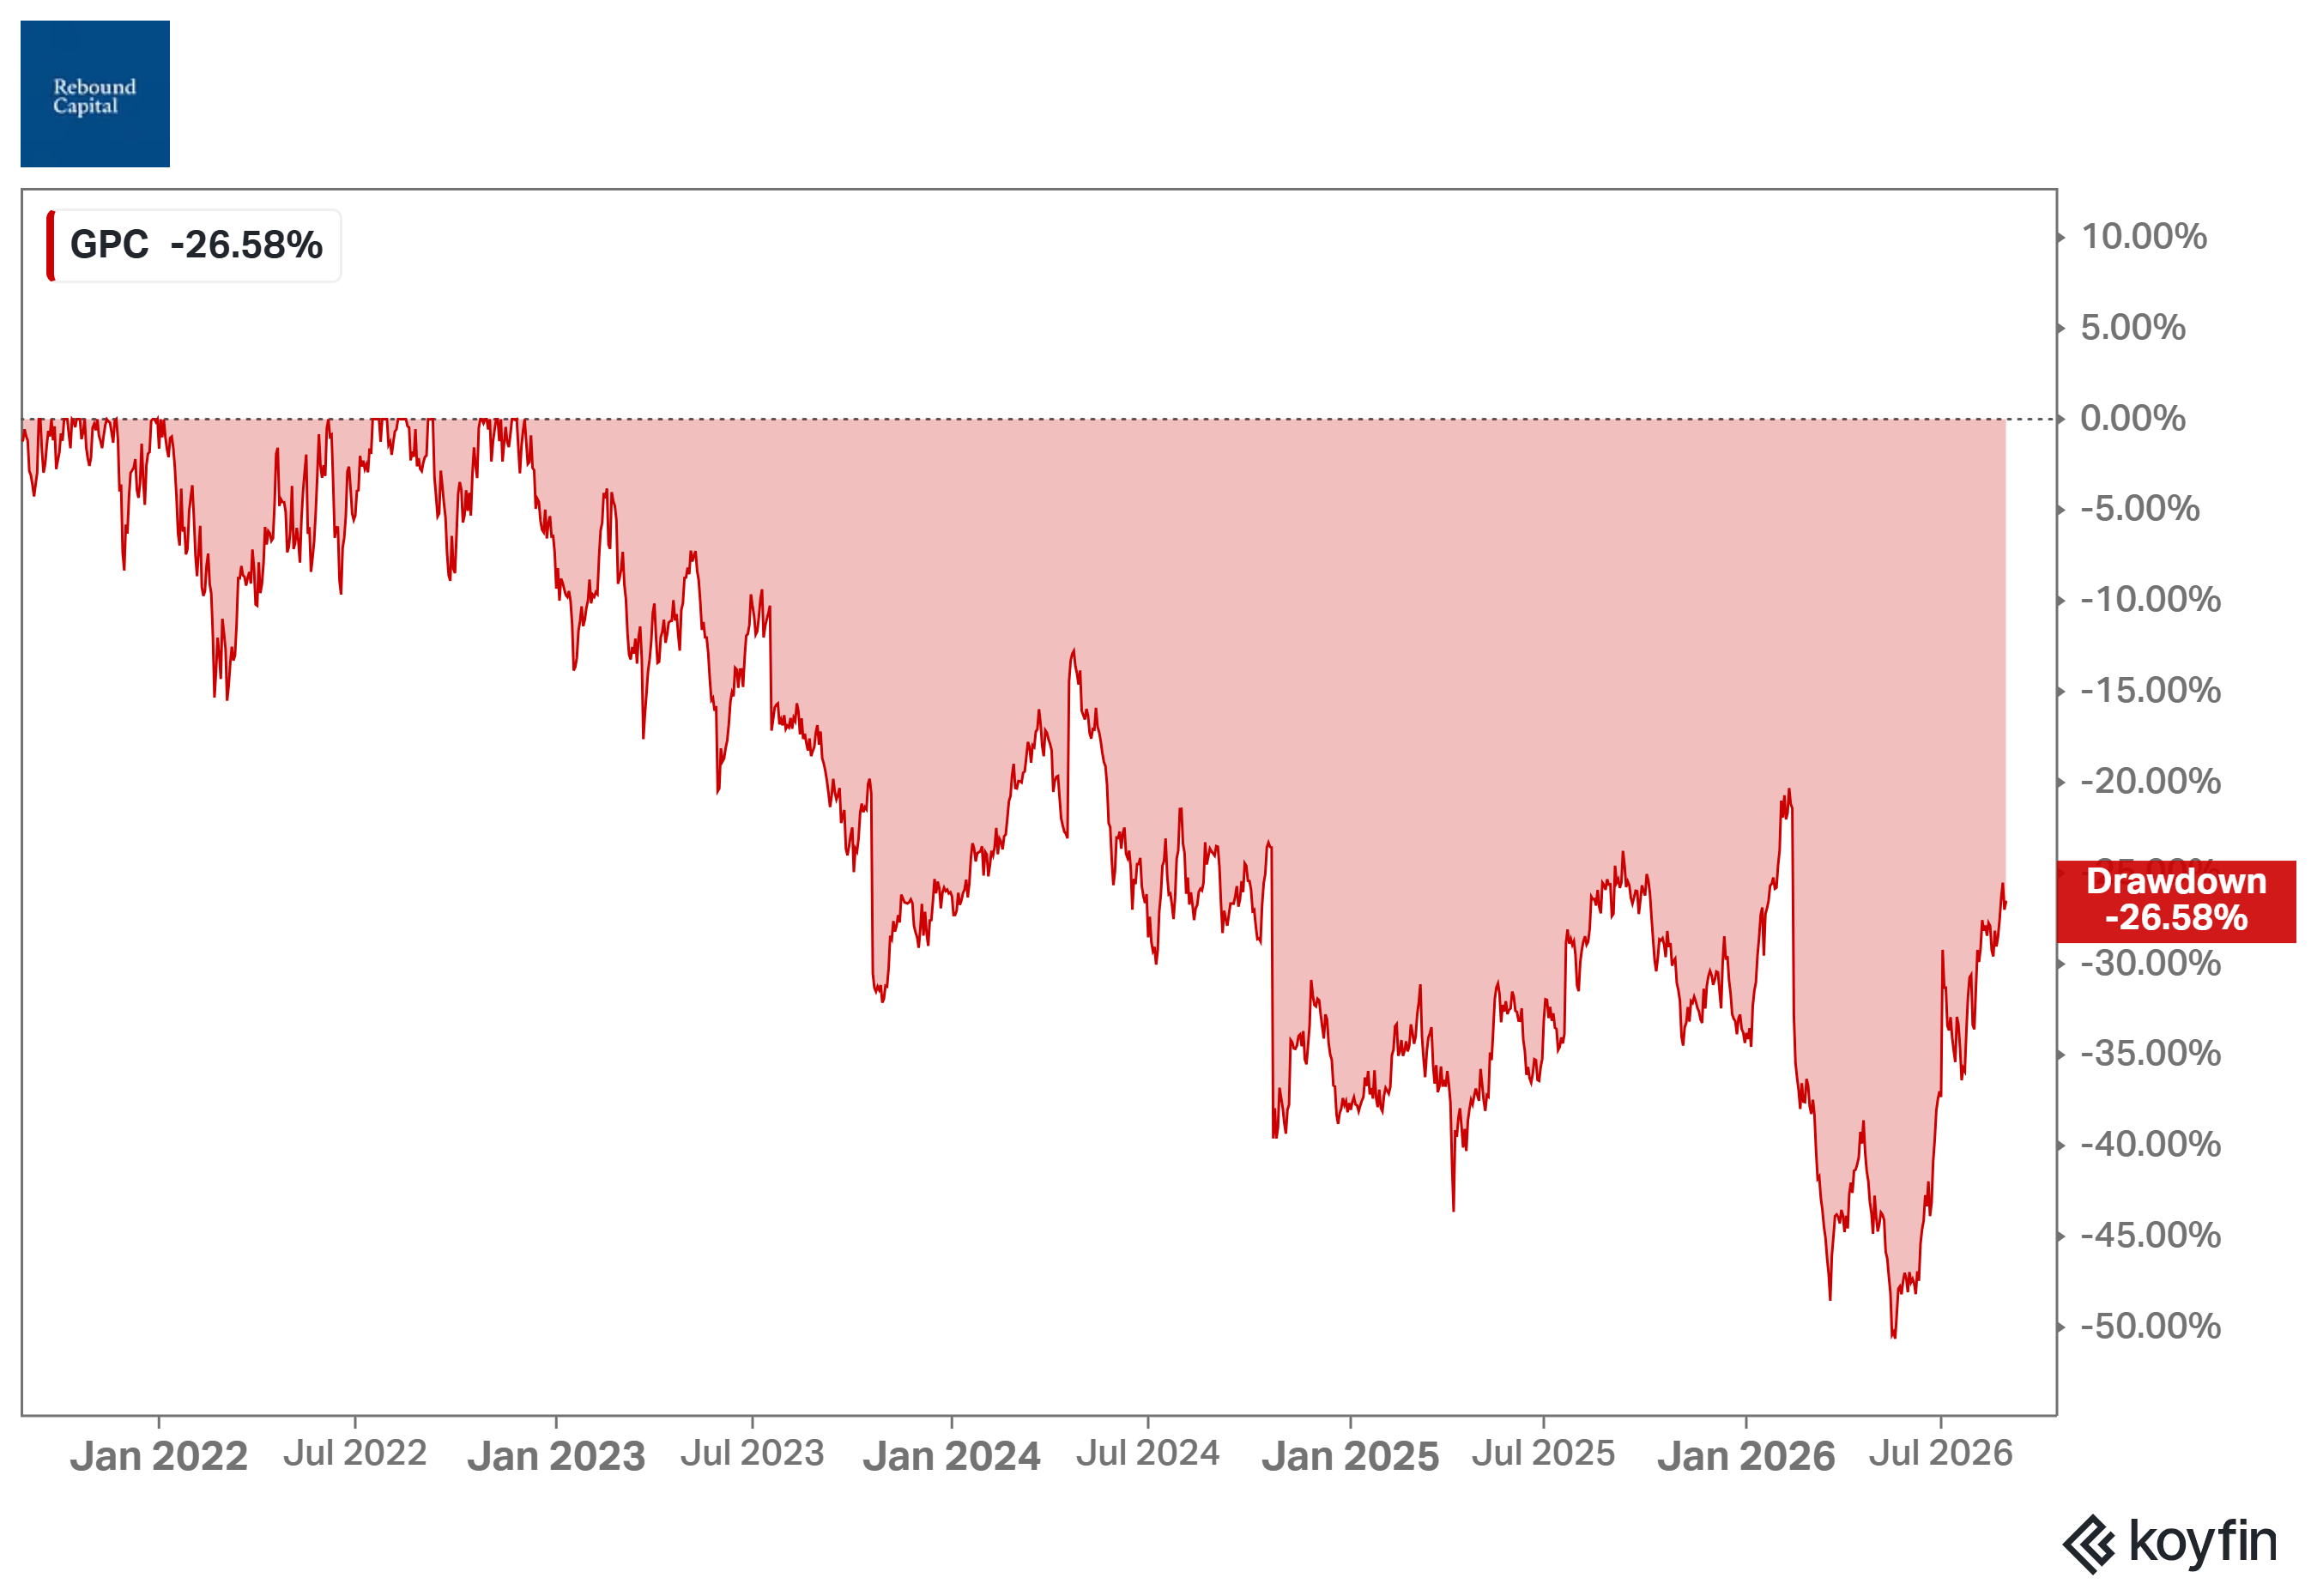
Genuine Parts Company is one of eight potential rebound stocks on RC’s September 2026 watchlist.
Sangamo Therapeutics’ Chapter 11 asset sales leave common equity tied to $100 million in PTC Fabry therapy approval milestones and a…
Andrada Mining’s Uis ore sorter targets higher tin grades and lower unit costs after FY26 operating cash flow reached £4.7 million, but…
Tectonic Therapeutic's TX45 CpcPH-HFpEF program gains support from Merck's CADENCE data; Phase 1b hemodynamics and cash through Q1 2029 set…
 Equity Eagle 2 clicks
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.