Unpolished Thoughts on Stocks #1
Genius Sports aims to turn official sports data into AI-driven, real-time advertising, with media and ads already about 40% of revenue.
Genius Sports aims to turn official sports data into AI-driven, real-time advertising, with media and ads already about 40% of revenue.
Another $PBI debt upgrade... "Pitney Bowes Inc. Upgraded To 'BB-' From 'B+' On Strong Credit Metrics; Outlook Revised To Stable From Positive" https://t.co/dl97639K74
@DreamPositiveCp @grok what is the binary event for $NN?
@FishtownCap Could $UNFI and $CHEF merge or too much overlap already
@everyonehatesp1 Idk but the lack of insight on coal names yesterday cost me this trade. Do better. $METC
@SurfShopCapital Thoughts on $PURR here?

Independence Realty Trust is buying Centerspace in stock to create an $8.1 billion apartment REIT, targeting 5% 2027 Core FFO per-share…
NET Power’s $1.80 shares are paired with January $2 covered calls for 40 cents as the company pivots from carbon capture to Permian…

Joby Aviation is initiated at Accumulate after booking $116m of trailing revenue, forming a Toyota manufacturing venture and agreeing to…

Sofwave Medical grew Q2 revenue 43% as recurring usage fees reached 46% of sales for its non-invasive ultrasound skin-tightening devices.
Priority Technology’s chairman offered $6.00 to $6.15 a share to take PRTH private, while Zack Buckley argues Treasury Solutions and…

Imperial Petroleum's record Q2 cash generation, major share repurchases and a $32 million Suezmax sale gain set up another record quarter.
 Henrik Alex 3 clicks

Amplitude reported Q2 revenue of $100.9 million, up 21%, as agentic AI and LLM vendors challenge the moat of its product analytics software.
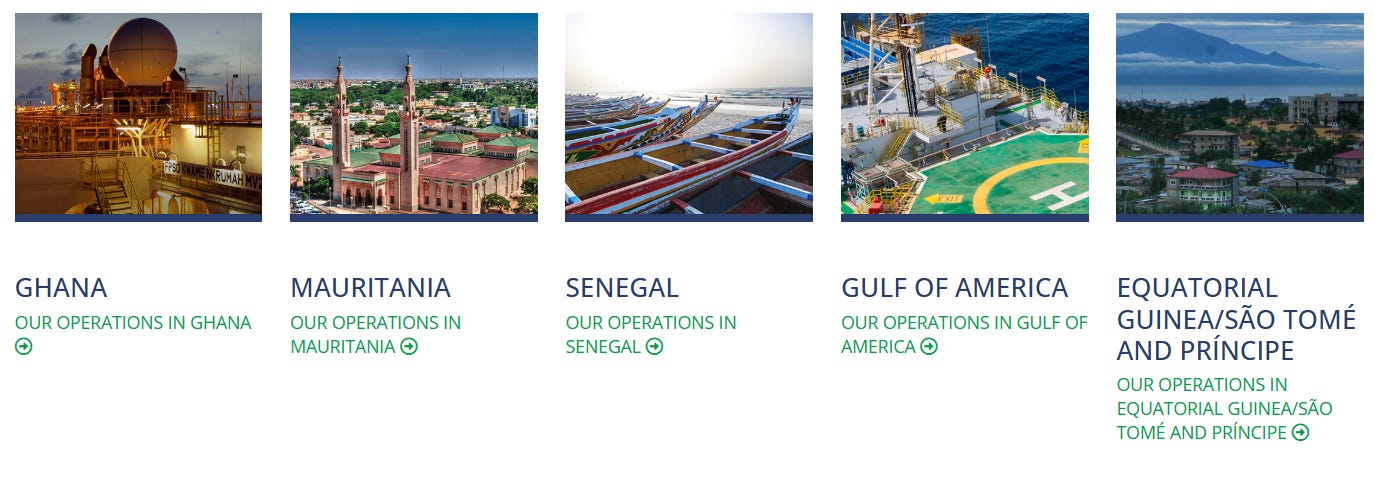
Kosmos Energy (KOS) is pitched as an oil stock poised to outperform if oil stays above $70-$80, supported by a claimed 2 billion-barrel…
ContextLogic will acquire specialty-solvent maker gChem for $850 million, funded by a $650 million rights offering and $250 million of…
Kodiak AI’s stock collapse coincides with a planned year-end long-haul driverless launch, while cash burn, customer concentration and…
 High Alpha Professor
 HNRG · long
Hallador Energy, a coal producer, is pitched as a long based on five value components and potential 2026 catalysts.
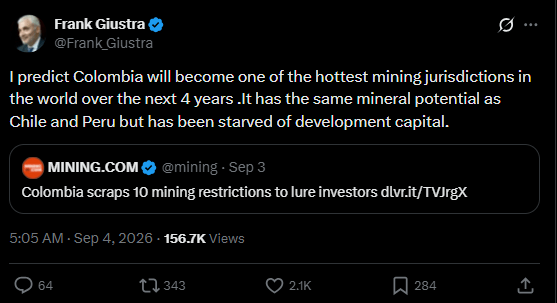
Tecnoglass could recover tariff- and FX-hit margins as U.S. blanket tariffs on Colombian goods lift.
Scholar Rock’s apitegromab could become the first muscle-targeted SMA therapy by September 2026, but manufacturing setbacks and a…
 Equity Eagle
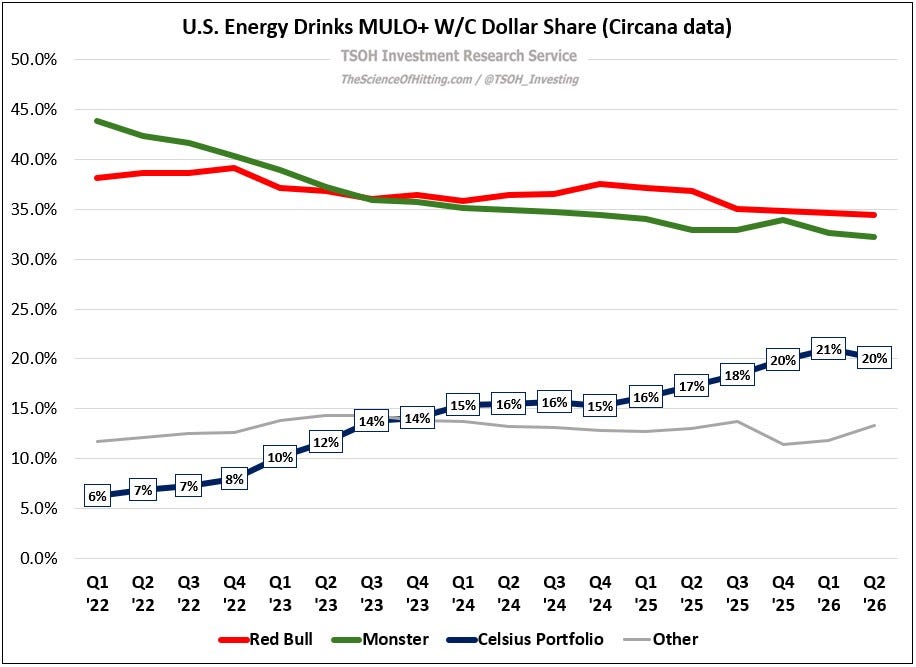
Celsius holds 20% of the U.S. energy-drink market and 40% of sugar-free sales, but its $1.65 billion Alani acquisition complicates…
On Holding $ONON combines a high-margin direct-to-consumer footwear model with replacement-driven demand, after Q2 2026 sales rose 21.6%…
National Vision Holdings' 2.2% same-store sales growth masked a 4.9% transaction decline, while inventory rose 37% and deferred marketing…
 Number Cruncher 1 click
Titan Mining reported Q2 revenue of $25.7 million and adjusted EBITDA of $9.6 million as zinc output rose, while advancing its Kilbourne…
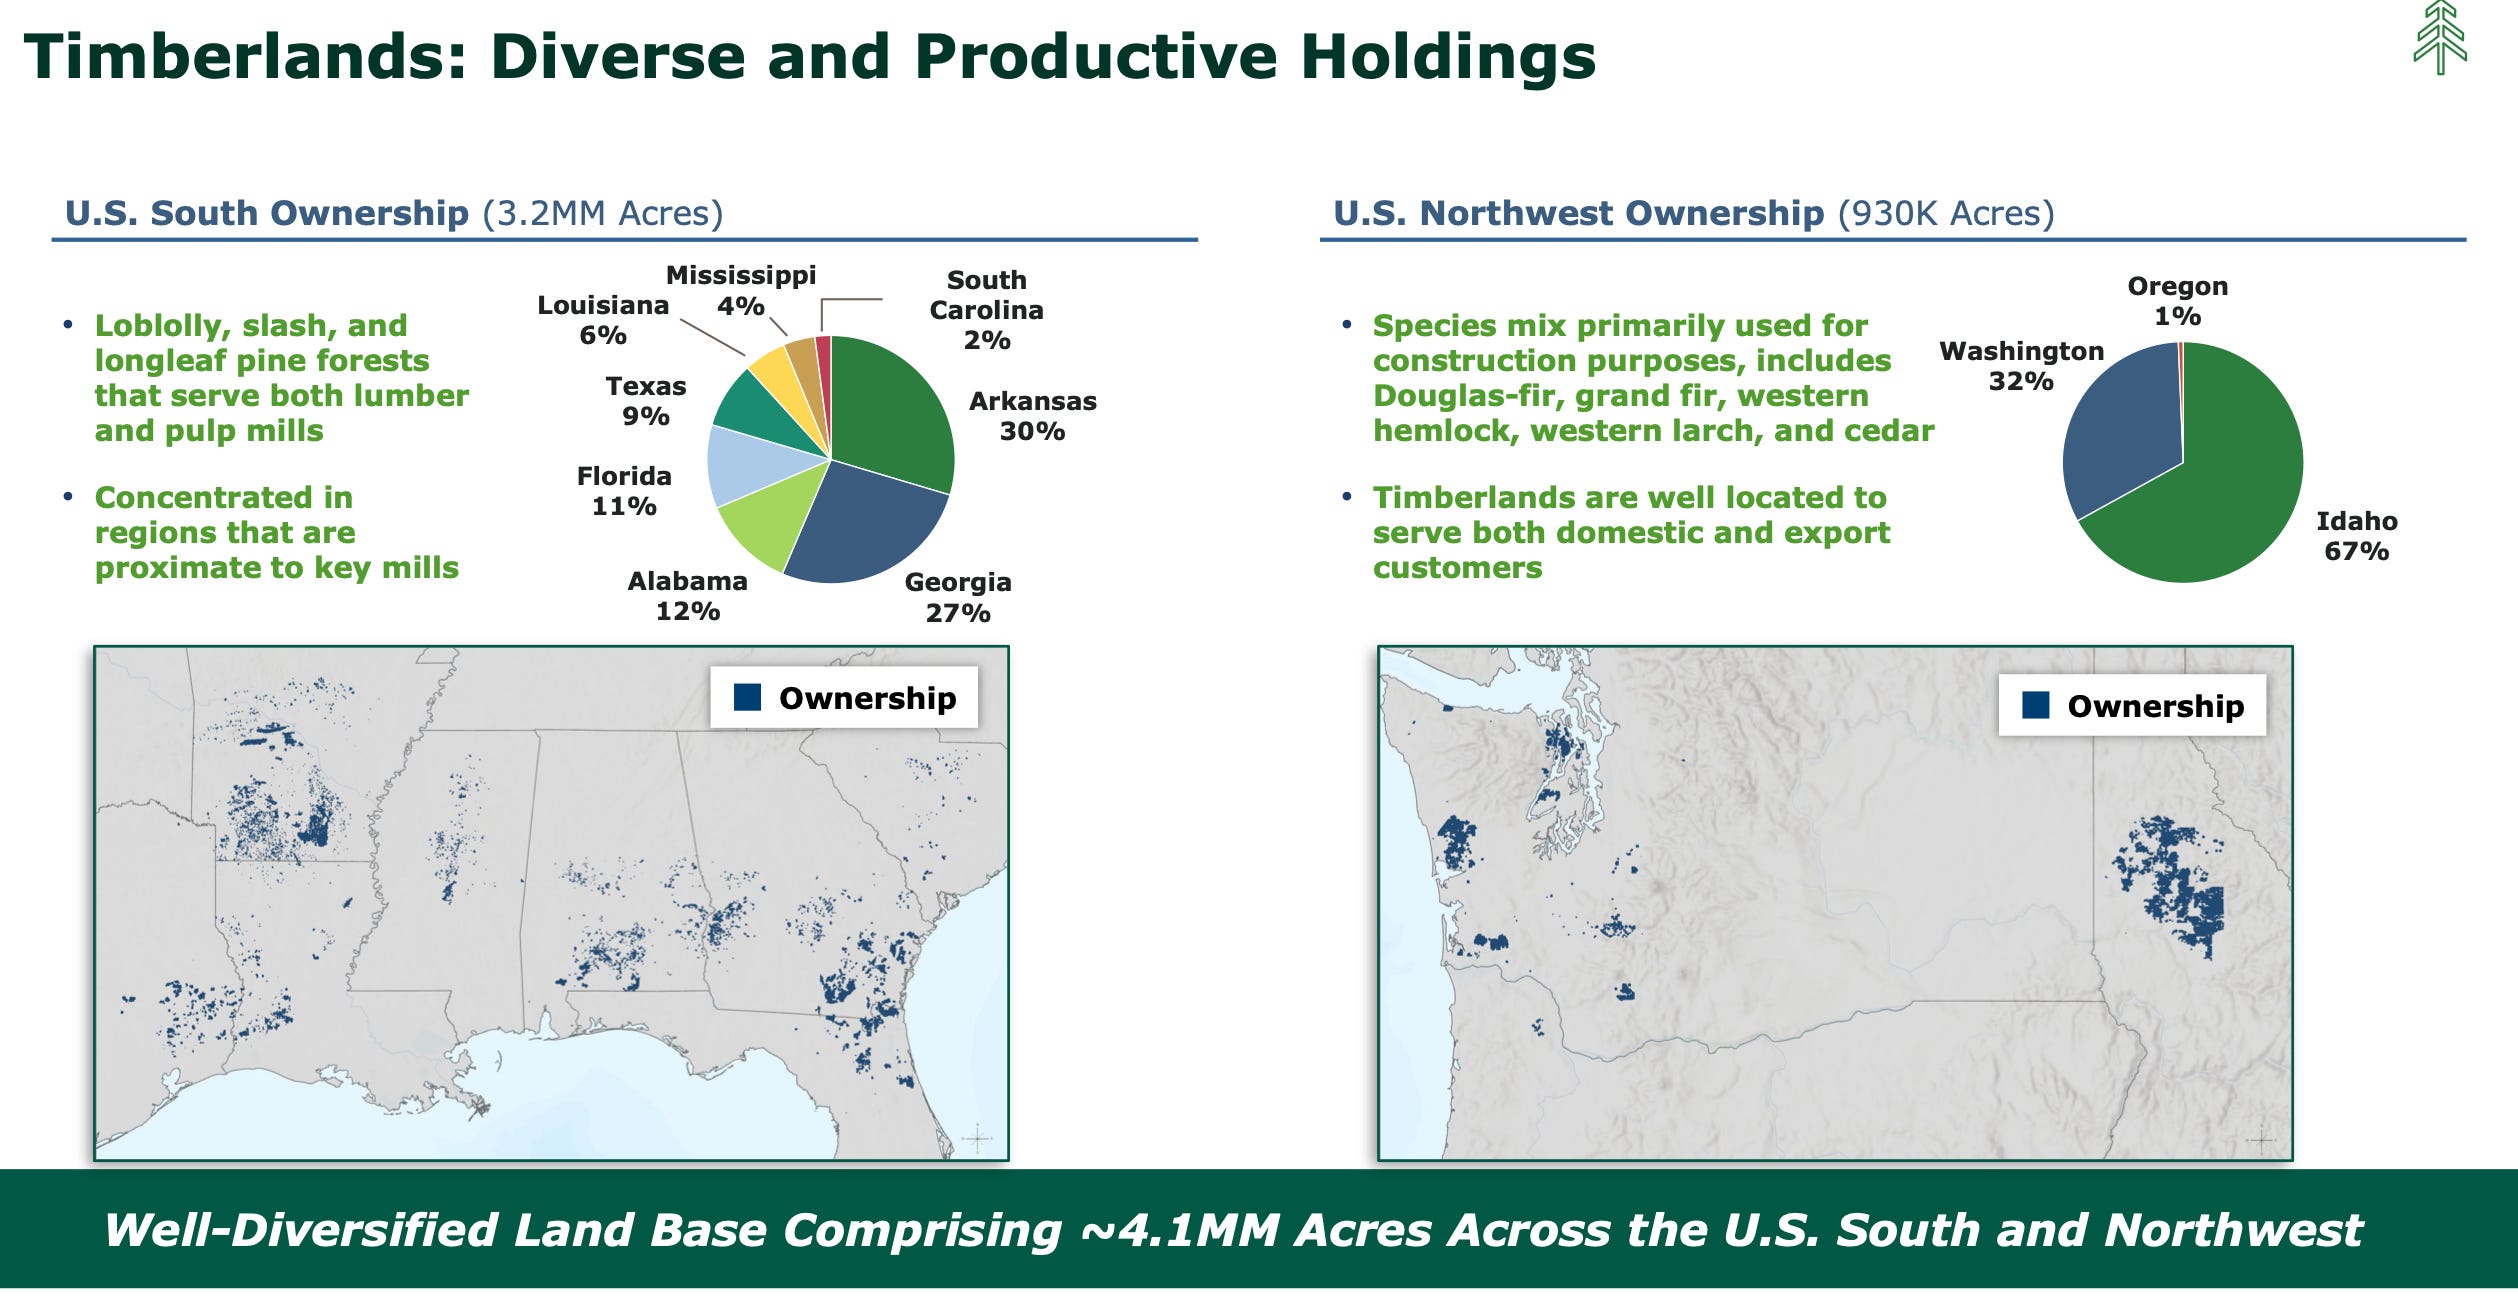
Rayonier’s 4.0 million acres are valued at $393 an acre after other assets, versus $1,200 to $1,800 cutover-land sales, framing the timber…
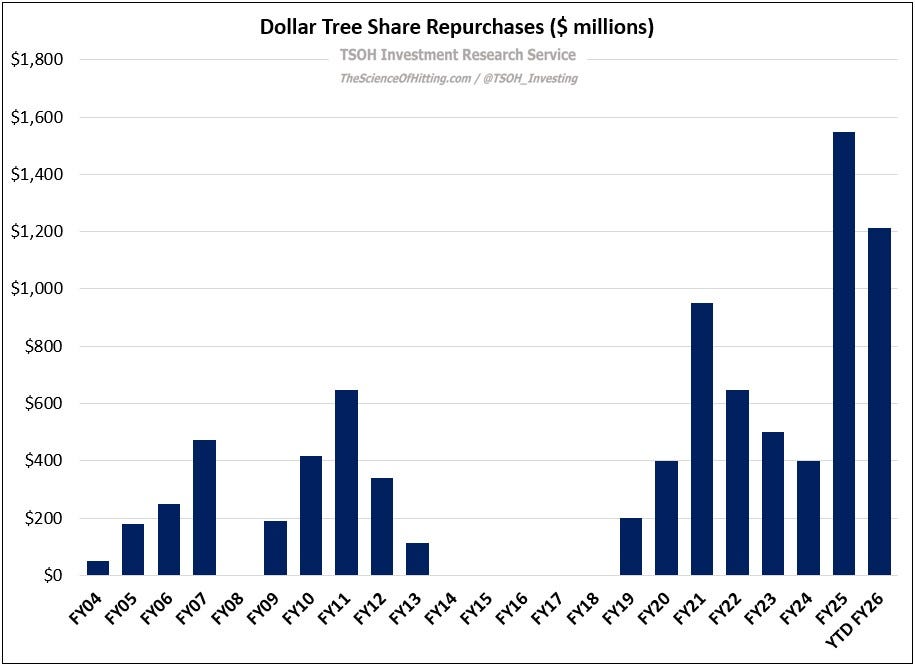
TSOH Weekly Roundup covers Costco’s $4.99 chicken supply chain, Celsius’s 20% energy-drink share, and California utilities’ wildfire…
Oklo’s Q2 progress includes Groves’ first criticality and Aurora agreements, while equity dilution cut its price target to $88 despite a $3…
 The Curious Analyst 1 click
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai Equity Eagle
 Eudaemon Research High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.