
Oak Bloke Bonkers Conkers 13th September 2026
Oak Bloke’s 2026 picks have returned 37% in GBP, with AltynGold, Geiger Counter, Silvercorp and China-focused trusts still rated buys despite higher prices and unresolved project risks.
Oak Bloke’s 2026 picks have returned 37% in GBP, with AltynGold, Geiger Counter, Silvercorp and China-focused trusts still rated buys despite higher prices and unresolved project risks.
@SurfShopCapital Thoughts on $PURR here?
That's a pretty big sale in $VAL. I still own/like. https://t.co/DoHOmmsAtD
Interesting follow up on this today: The SEC settled an enforcement action against $TBBK's now-retired CFO, fining him $30,000 for directing the company's 10-K to be filed when he knew the auditors hadn't yet signed off. https://t.co/9N28UhEMlw https://t.co/8yBRR6MC7Q https://t.co/1lPgtgKyWD
$ASAN down 12% on weak guidance. This earnings season has sucked so gotta enjoy my wins. https://t.co/wHULS7a1xW
@LatamData Medellín will keep taking relative share from Bogota. Underappreciated driver for $asr
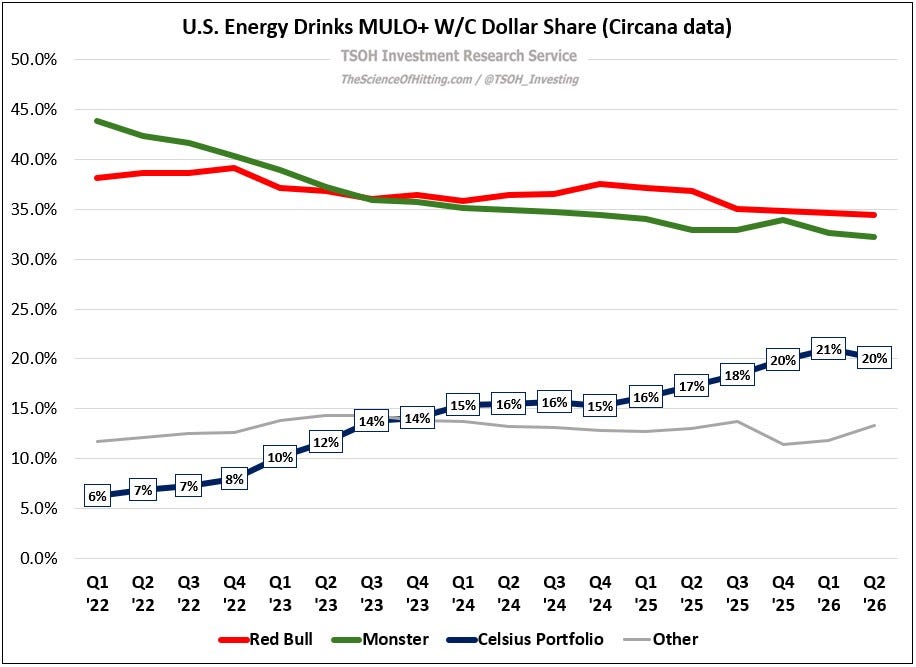
Celsius holds 20% of the U.S. energy-drink market and 40% of sugar-free sales, but its $1.65 billion Alani acquisition complicates…
On Holding $ONON combines a high-margin direct-to-consumer footwear model with replacement-driven demand, after Q2 2026 sales rose 21.6%…
X-energy targets $1.8 billion in annual revenue and more than 42% gross margins by 2032 through reactor IP, project services and…
 Simple Investment Ideas 2 clicks
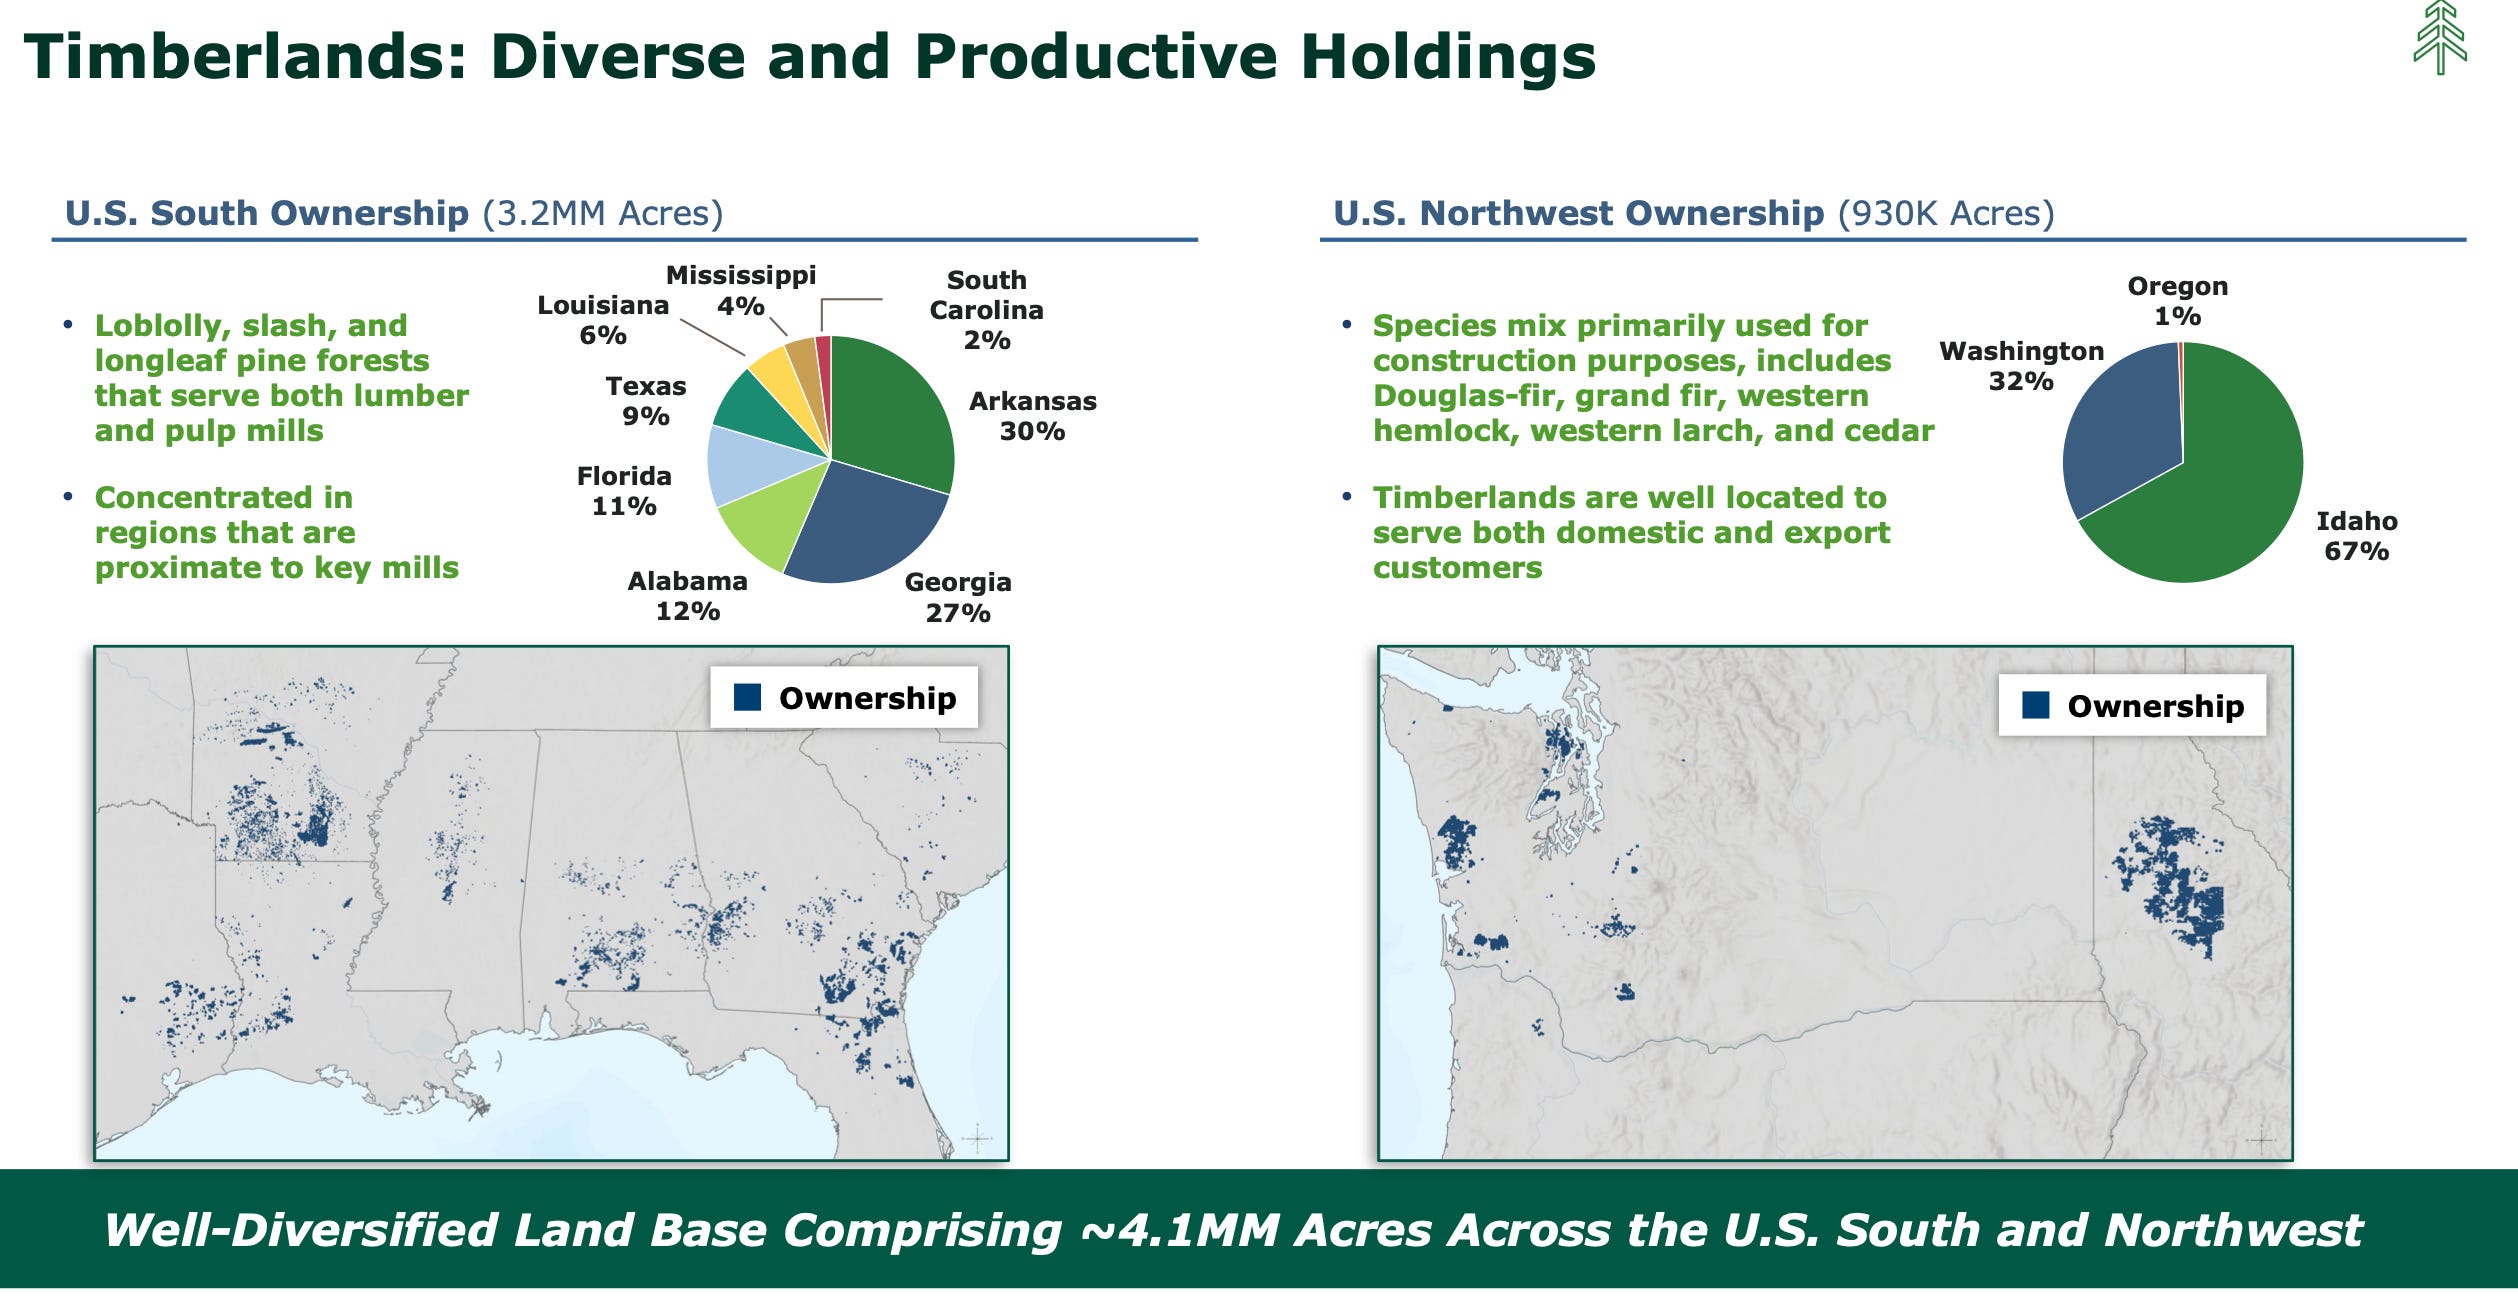
Rayonier’s 4.0 million acres are valued at $393 an acre after other assets, versus $1,200 to $1,800 cutover-land sales, framing the timber…
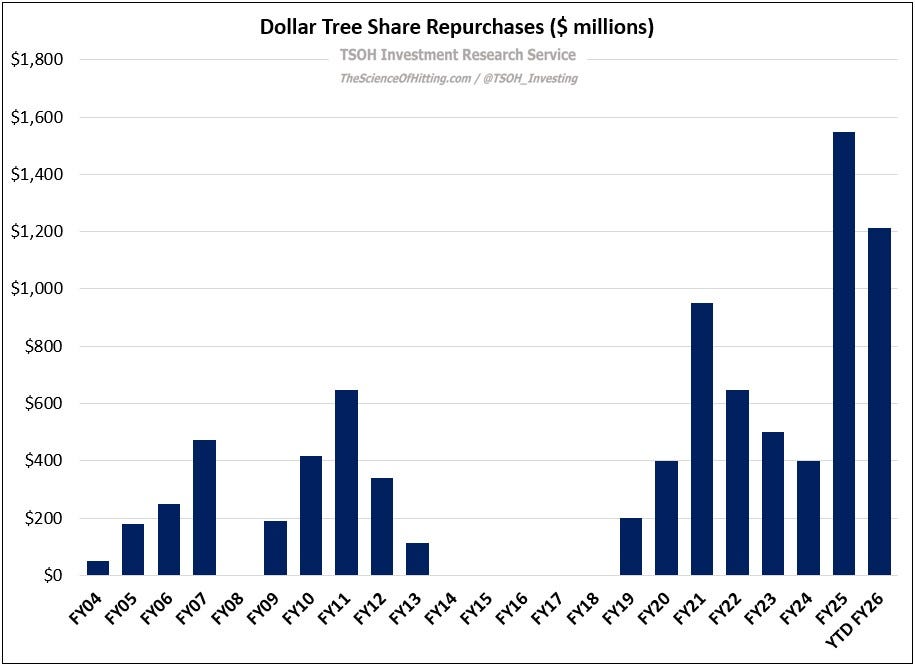
TSOH Weekly Roundup covers Costco’s $4.99 chicken supply chain, Celsius’s 20% energy-drink share, and California utilities’ wildfire…
Oklo’s Q2 progress includes Groves’ first criticality and Aurora agreements, while equity dilution cut its price target to $88 despite a $3…
 The Curious Analyst 1 click

Lumen is shedding consumer lines for data-center services; $9.2 billion of deferred revenue, up 72%, supports its enterprise order book…
MDA Space is added to the Aurelion Index after hiring engineers, signing large contracts and expanding facilities; the thesis cites…
Cleveland-Cliffs' 2027 upside depends on contract resets and Stelco earnings, while management directs free cash flow to deleveraging…
 The Bullionaire 1 click
Waystar sells revenue-cycle software for a US claims process where roughly 18% of submitted claims are initially denied and healthcare…
 MGRC · long
McGrath RentCorp's conservatively financed hard assets, pricing growth and a struggling competitor, WSC, underpin the long thesis.
Scholar Rock’s apitegromab could become the first muscle-targeted SMA therapy by September 2026, but manufacturing setbacks and a…
 Equity Eagle

Higher rates could compress equity multiples and raise AI data center lease costs, while UWMC and Cogent raise questions about CEO-driven…
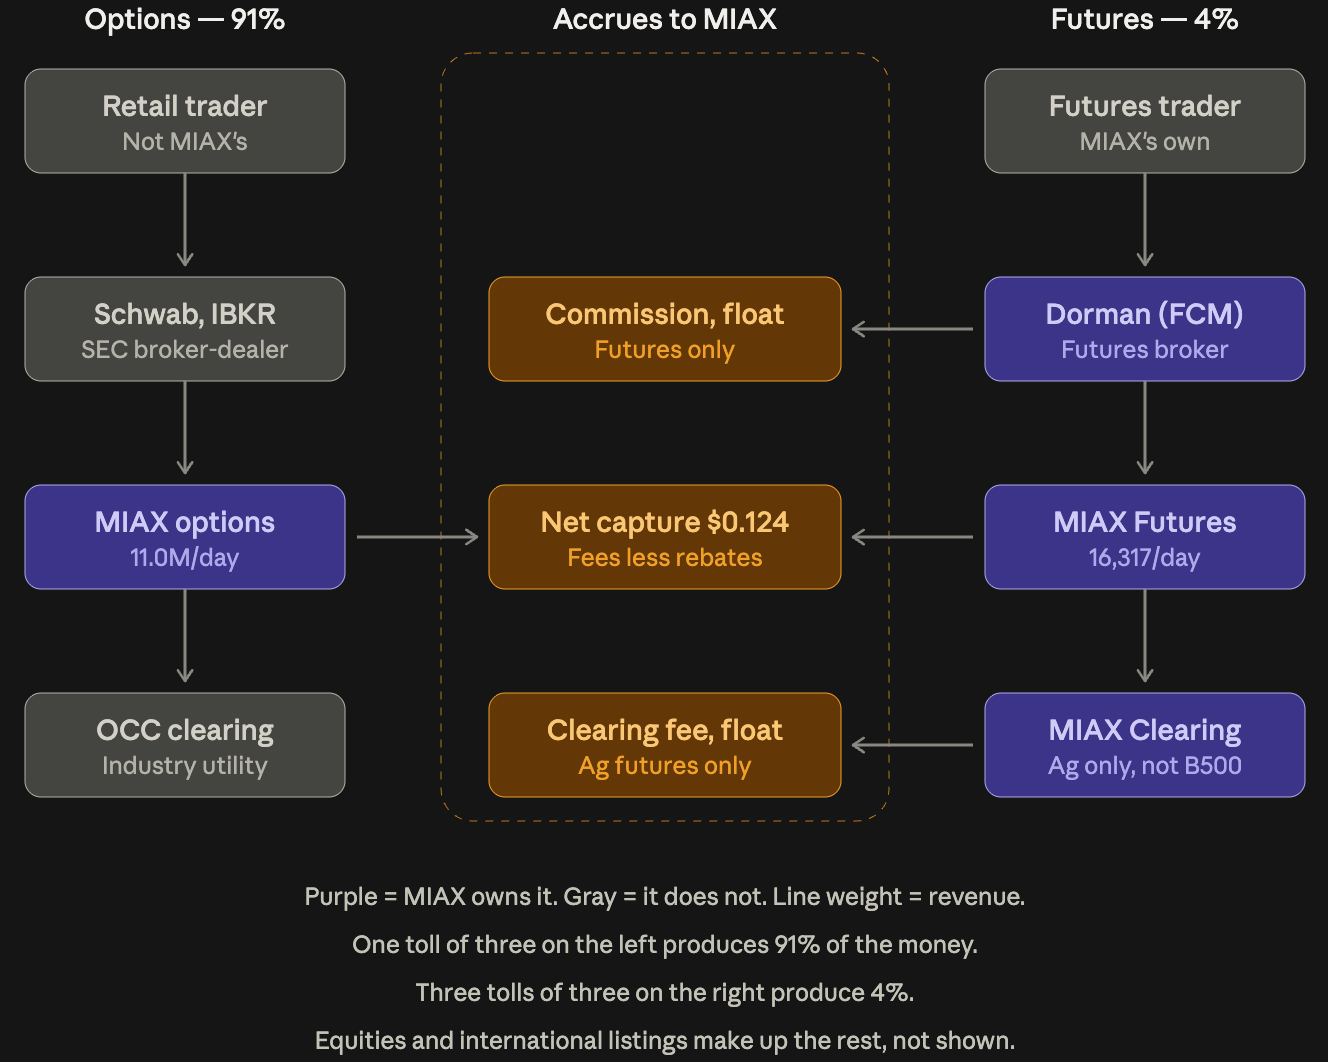
Miami International Holdings, the No. 4 options exchange with 17% share, trades at 12x forward EBITDA despite 35% revenue growth, 54%…
 TPC 2026-08-27
Tutor Perini’s Q2 revenue rose 19% to $1.64 billion as higher-margin megaprojects lifted construction income 54%, prompting higher 2026 EPS…
The Curious Analyst 
Cal-Maine, the largest U.S. egg producer, trades at 1.6x book versus a 2.1x 20-year median, with net cash and investments equal to 23% of…
Planet Fitness runs 2,930 clubs and 21.5 million memberships through an asset-light franchise model funded by $15 monthly dues, royalties…
Modine's leaked database identifies Google behind a $4 billion agreement and $4.5 billion of additional demand, with nearly $15 billion of…
IRTC 2026-08-21 IRhythm’s ZEUS clearance cuts clinician review time 50%, targeting $100 million in five-year savings as cardiac monitoring margins expand…
Equity Eagle 
El Al trades near 2x EBITDA after wartime near-monopoly profits, with $1.3 billion of net cash and owned aircraft weighed against…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights Simple Investment Ideas
 Steven Fiorillo The Bullionaire The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.


