Lululemon: Deep Dive Analysis
Lululemon’s Q2 revenue fell 4% and Americas comparable sales 12%, as markdowns, tariffs and activewear rivals pressure its premium apparel model.
Lululemon’s Q2 revenue fell 4% and Americas comparable sales 12%, as markdowns, tariffs and activewear rivals pressure its premium apparel model.
Answer: aggressive revenue booking, financing sales, selling products at/ below cost to boost revenue and hoping to “then try to build it back up over time” per CEO. Contrast $PLUS performance w competitor and industry leader $CDW.
$PLUS Numbers don’t add up. 50% sales $CSCO product (sales -13% MRQ, guided -11%). MRQ $PLUS sales +13% (reported yesterday). Earnings call question: “OEM Cisco have talked about bottlenecks, weak orders. You’ve been unscathed…how are you outperforming the market significantly?”
$EXLS Highly innovative founder-CEO rapidly taking share w AI-based services. High-teens topline growth w expanding margins, higher value-add mix to attractive end-markets. 17x P/E yet to reflect business transformation. 100% FCF to buybacks. Winning customers from $ACN $DXC $WIT
8/ There is a lot more to talk about (24% sequential increase in new home sales, ward village condo sales etc.) but I am hungry. So to wrap up, if you're selling $HHH on this quarterly report you do not understand what you own and I will be buying your shares at tomorrow's open.
1/ So first things first, $HHH missed on top and bottom line. Am I concerned? Absolutely not. Value was created for shareholders and I'll briefly explain why...
$OII Niche leader in subsea robotics at 12x P/E. Offshore rig count accelerating (70% share), A&D growing DD, new autonomous tech a major growth driver in other end markets (lifts, etc). Investor day next week will showcase products and new LT targets. >50% NTM upside, IMO.
@TheMuffinMan28 SRS is a PE rollout, bit of a hodgepodge of assets. Concentration in landscaping, pool and roofing. No exclusive relationships (GMS is for $AWI, regional duopoly across most categories). End customers are small homebuilders (more competitive, less scale benefit for distributors).
$GMS Underfollowed building products distributor, HSD growth, favorable mix shift/ margin, tracking to beat estimates, trading at 10x EPS, 7x EBITDA. Peers at >50% higher multiples. $HD just acquired lower quality peer SRS for 17x EBITDA. GMS = $240 or +150% at that multiple.
Lululemon’s Americas revenue fell 8% and comps dropped 12%, while a $134.5 million tariff refund masked weakening underlying margins after…
 On the Pulse 1 click
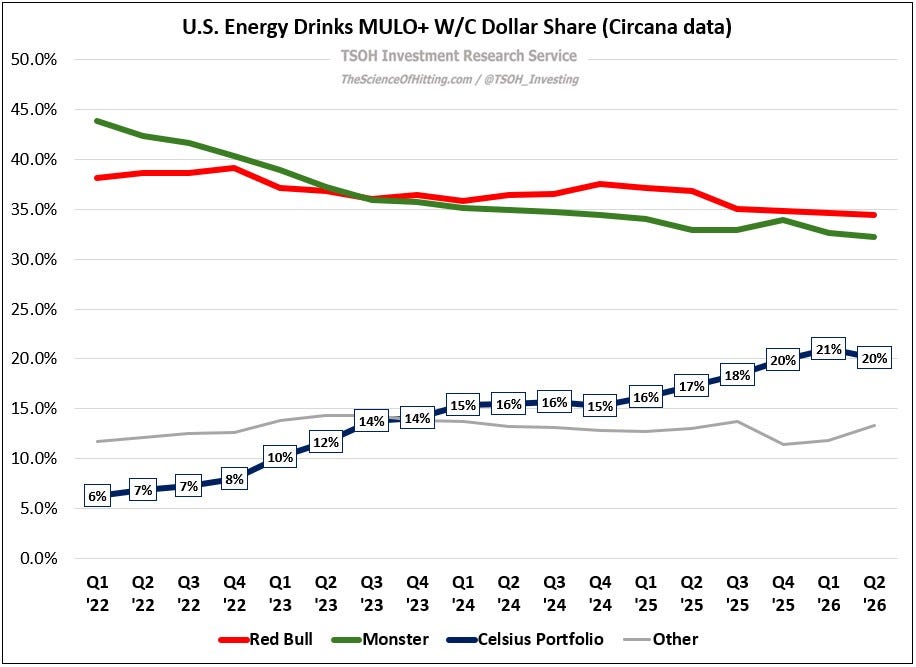
Celsius holds 20% of the U.S. energy-drink market and 40% of sugar-free sales, but its $1.65 billion Alani acquisition complicates…
On Holding $ONON combines a high-margin direct-to-consumer footwear model with replacement-driven demand, after Q2 2026 sales rose 21.6%…
Check Point Software’s AI-centric cybersecurity platform could lift revenue growth to 10%, supporting a $166 intrinsic value estimate…
 Hong Chew Eu
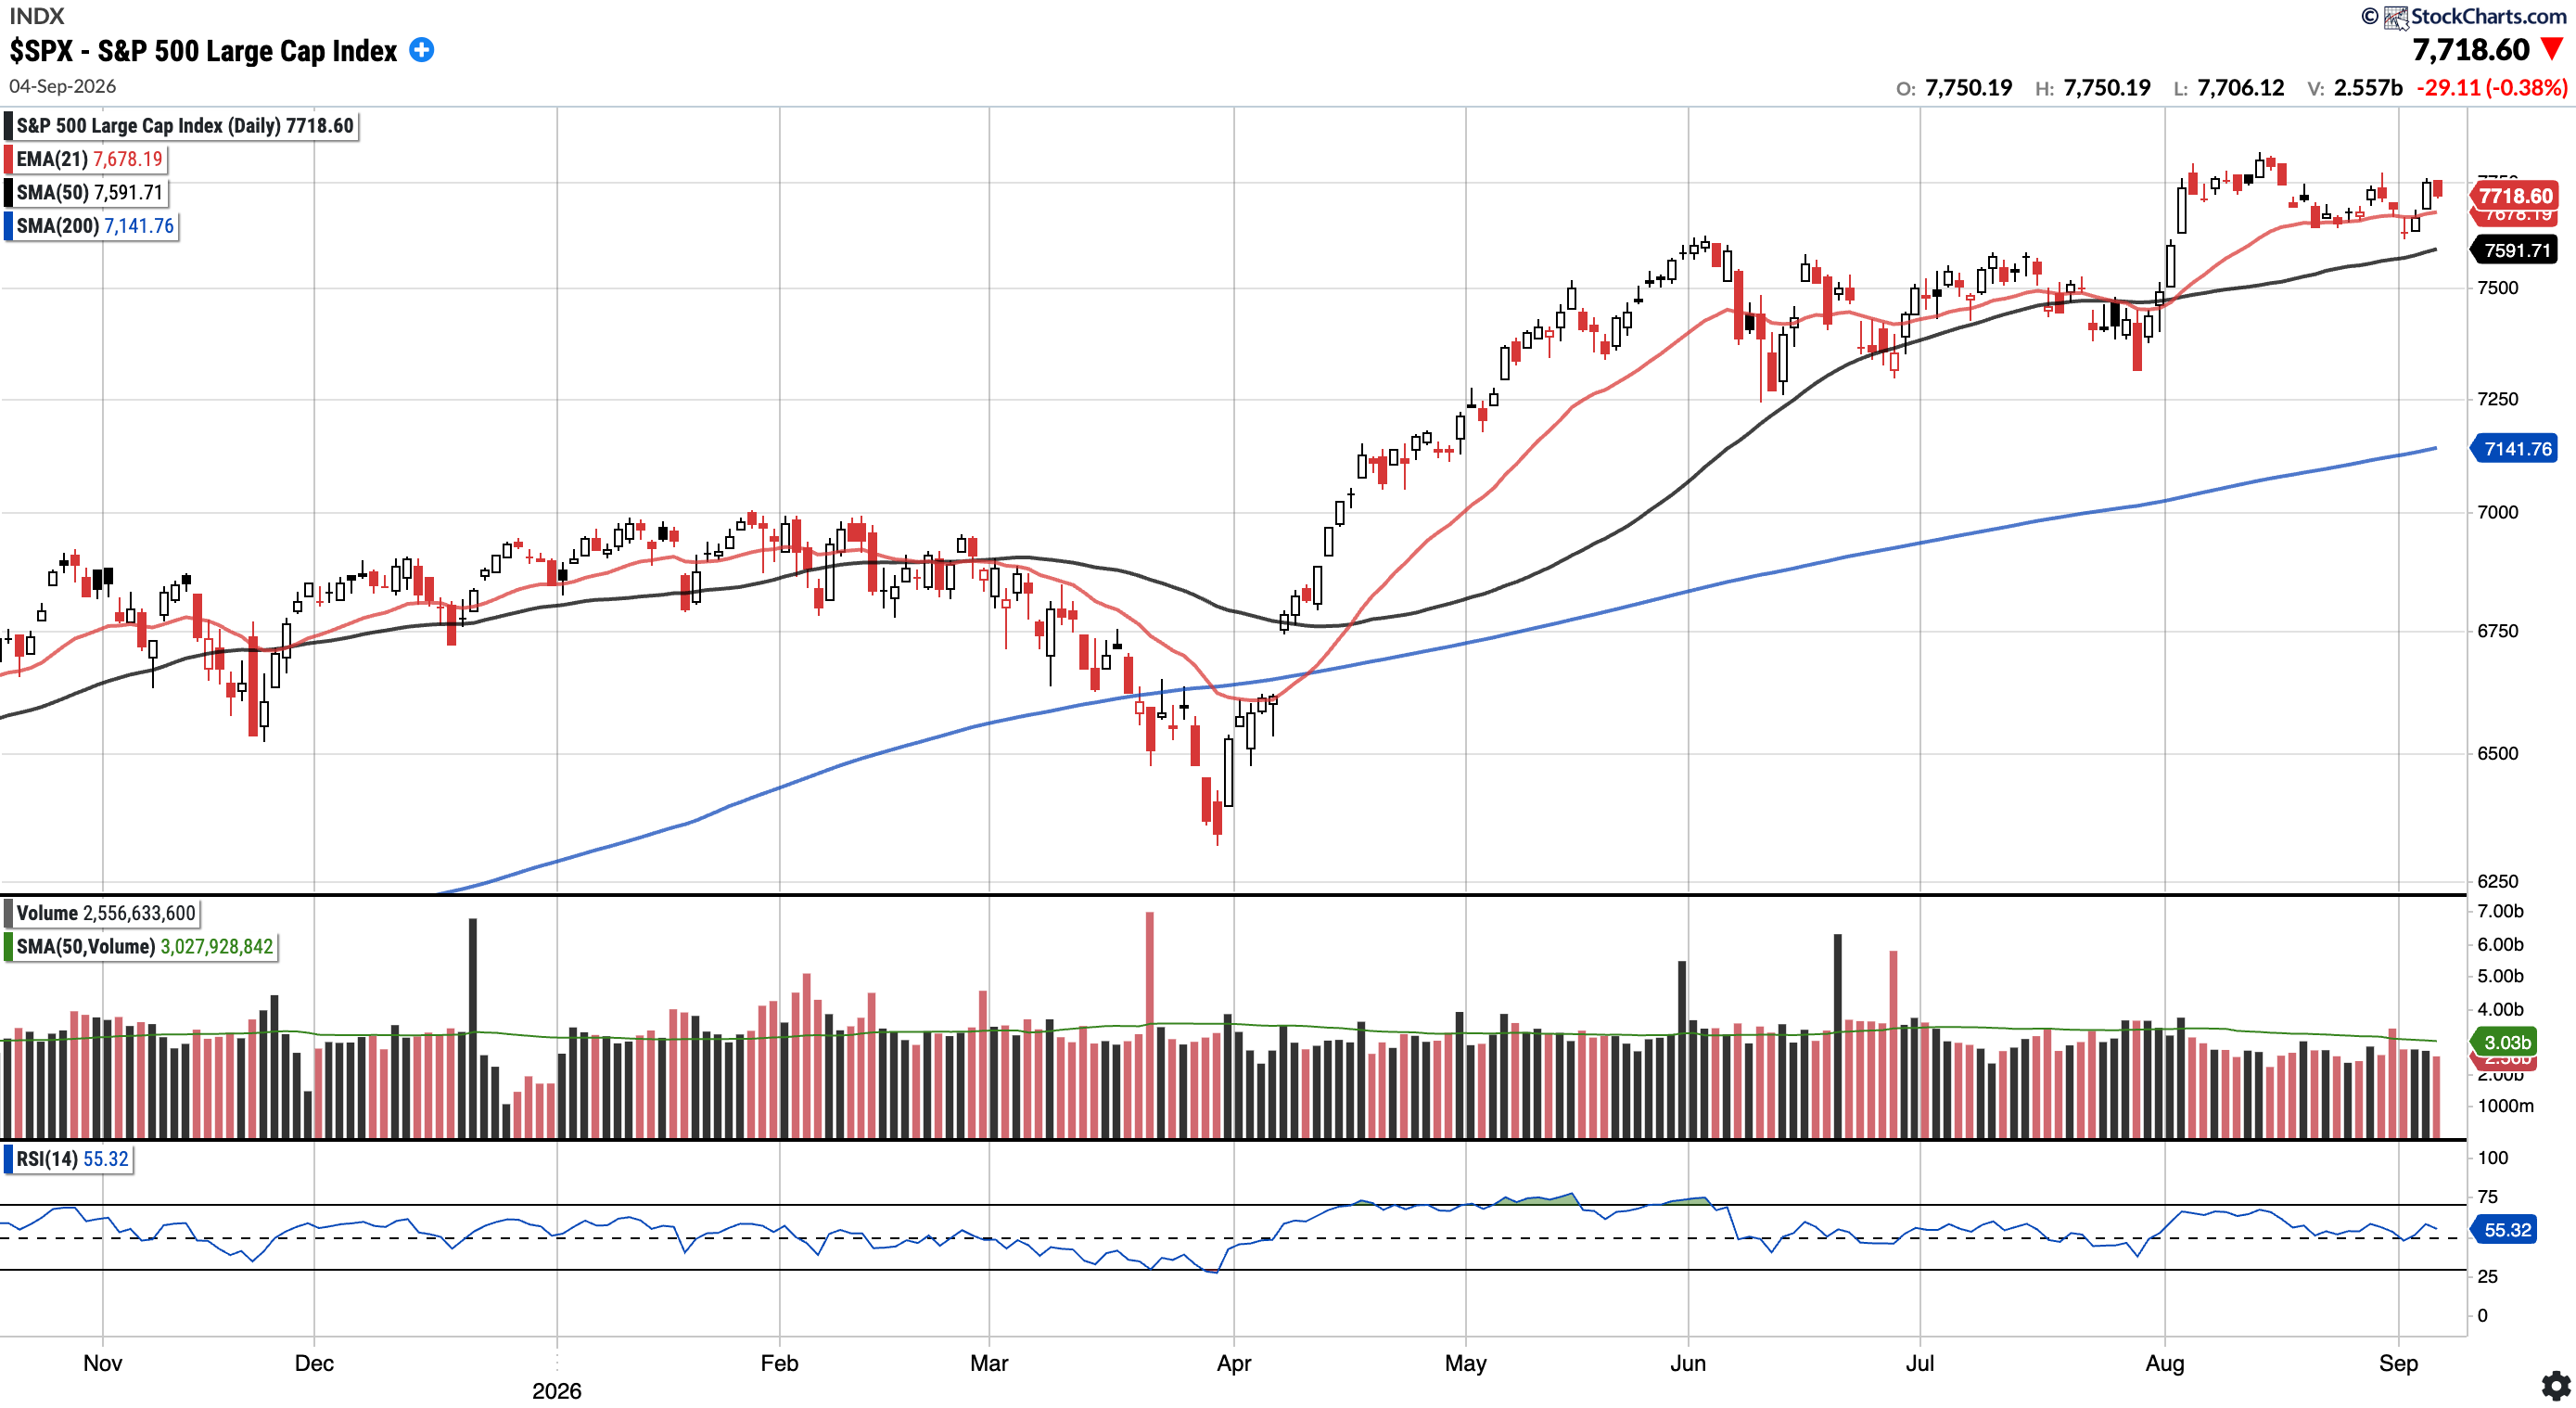
U.S. CPI and PPI headline the September 7 week as the S&P 500 holds key averages, Bitcoin faces $82,000 resistance and gold tests its…
X-energy targets $1.8 billion in annual revenue and more than 42% gross margins by 2032 through reactor IP, project services and…
 Simple Investment Ideas 2 clicks
AppLovin is down 48% YTD after its first guidance miss, with revenue 1% below expectations and EPS 2.5% short, reviving fears of an adtech…
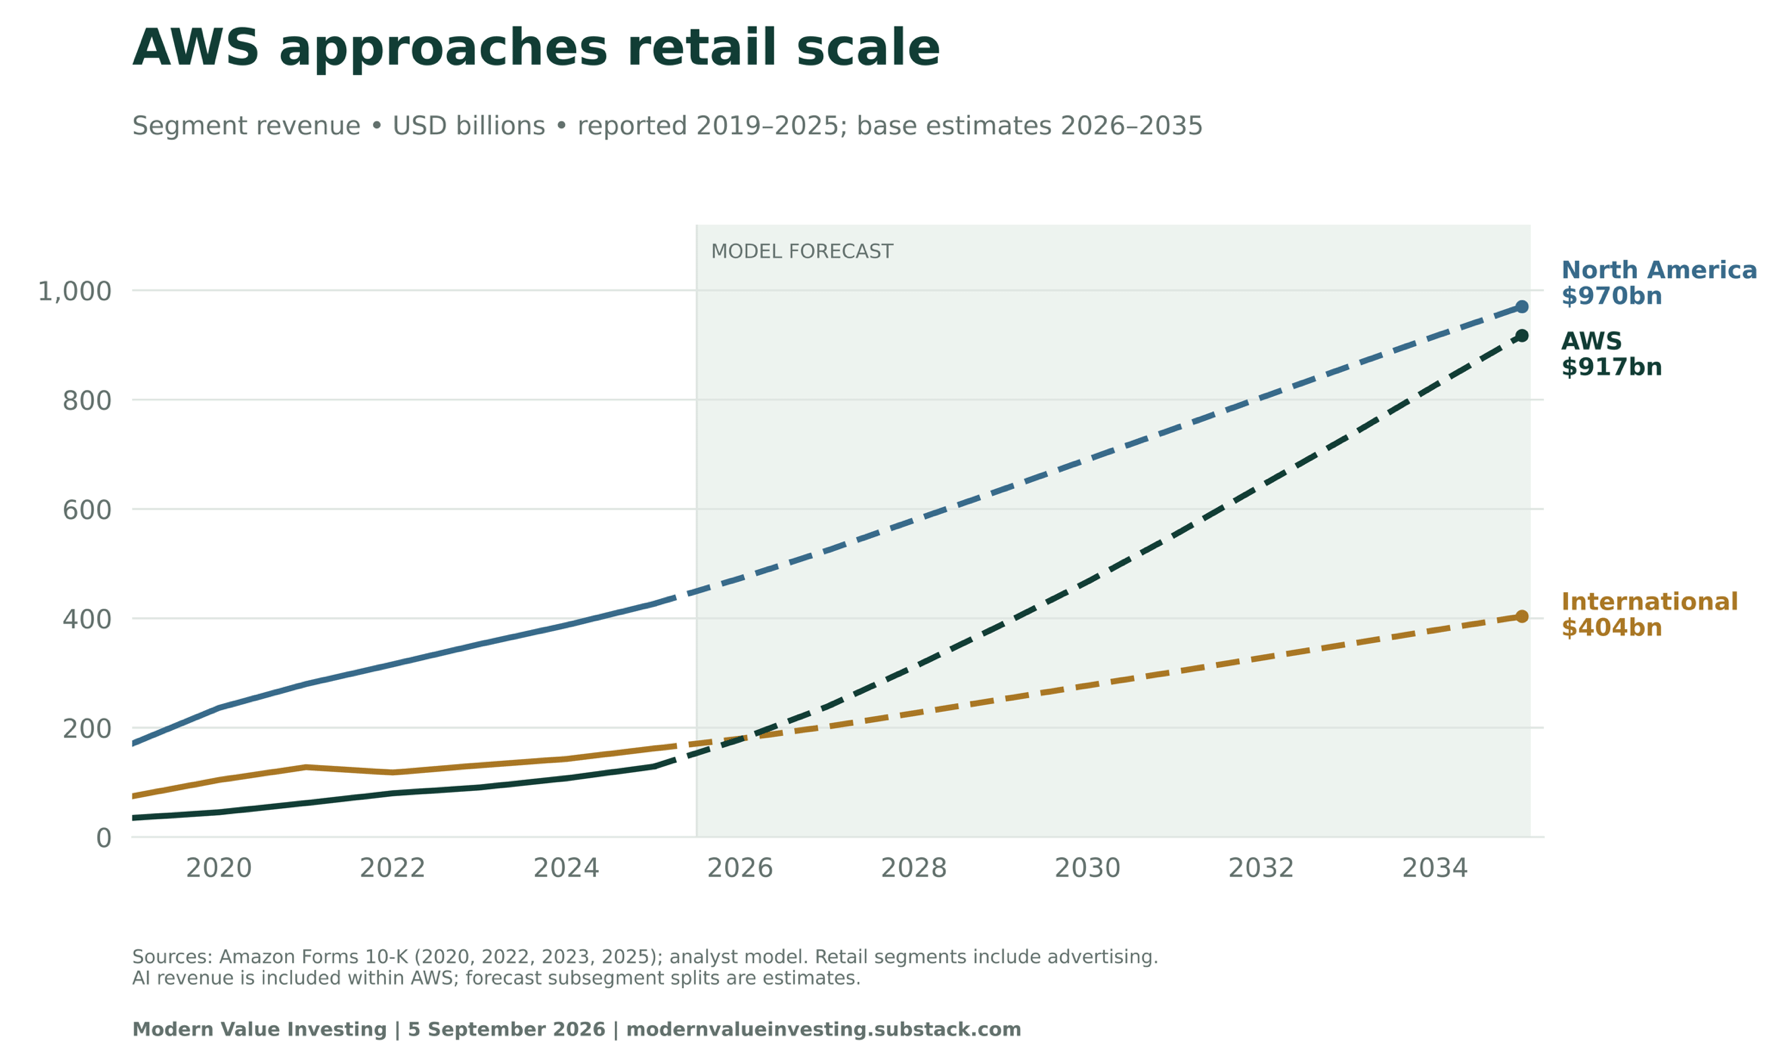
Amazon combines AWS AI infrastructure, model-company stakes and retail automation, with AWS targeting $1 trillion in annual revenue over…
Netflix’s roughly $20 billion content budget can become an editorial advantage as generative AI cuts production costs and floods viewers…
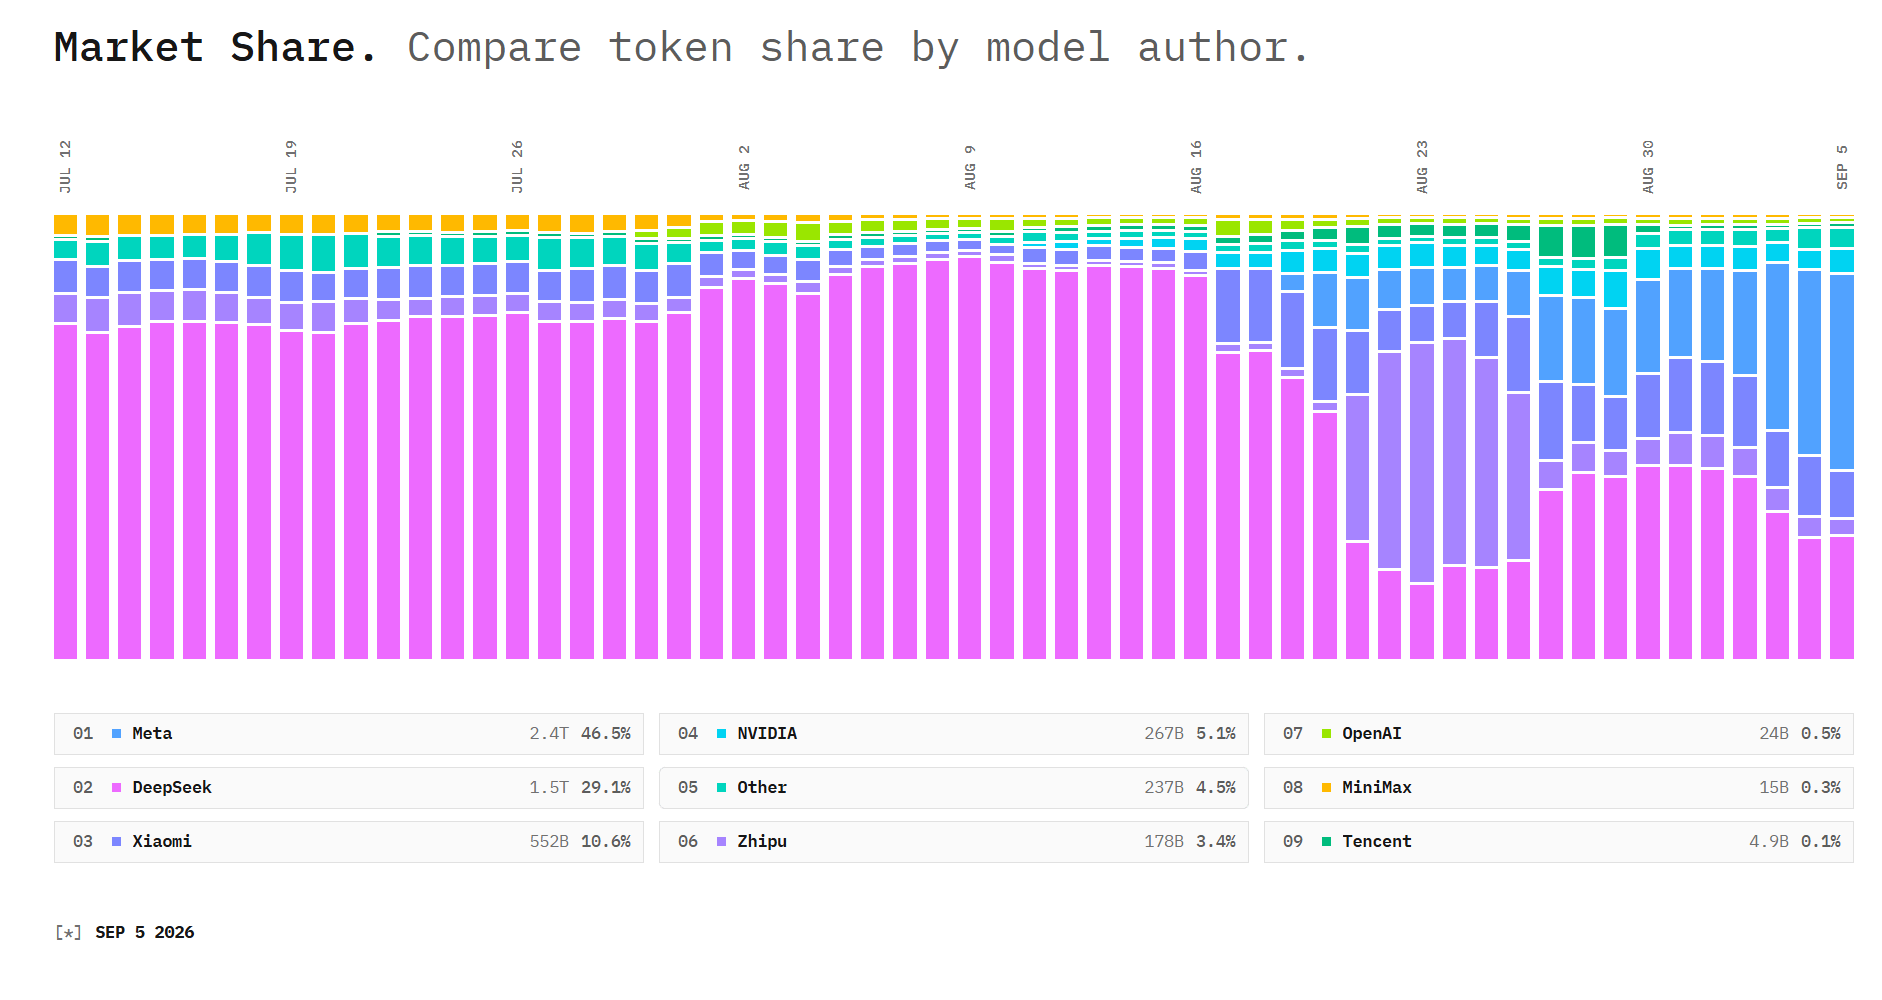
Meta’s free model strategy lifted OpenCode token share from 25% to 40%, building coding-data feedback loops and reducing reliance on…
 MGRC · long
McGrath RentCorp's conservatively financed hard assets, pricing growth and a struggling competitor, WSC, underpin the long thesis.
Pinterest’s Q2 showed reaccelerating North American growth, while weaker international trends, AI-related engagement risks and elevated…
 Richard Durant 2 clicks
OpenAI's potential failure could expose the US economy's growing dependence on AI capital spending, according to Steve Eisman.
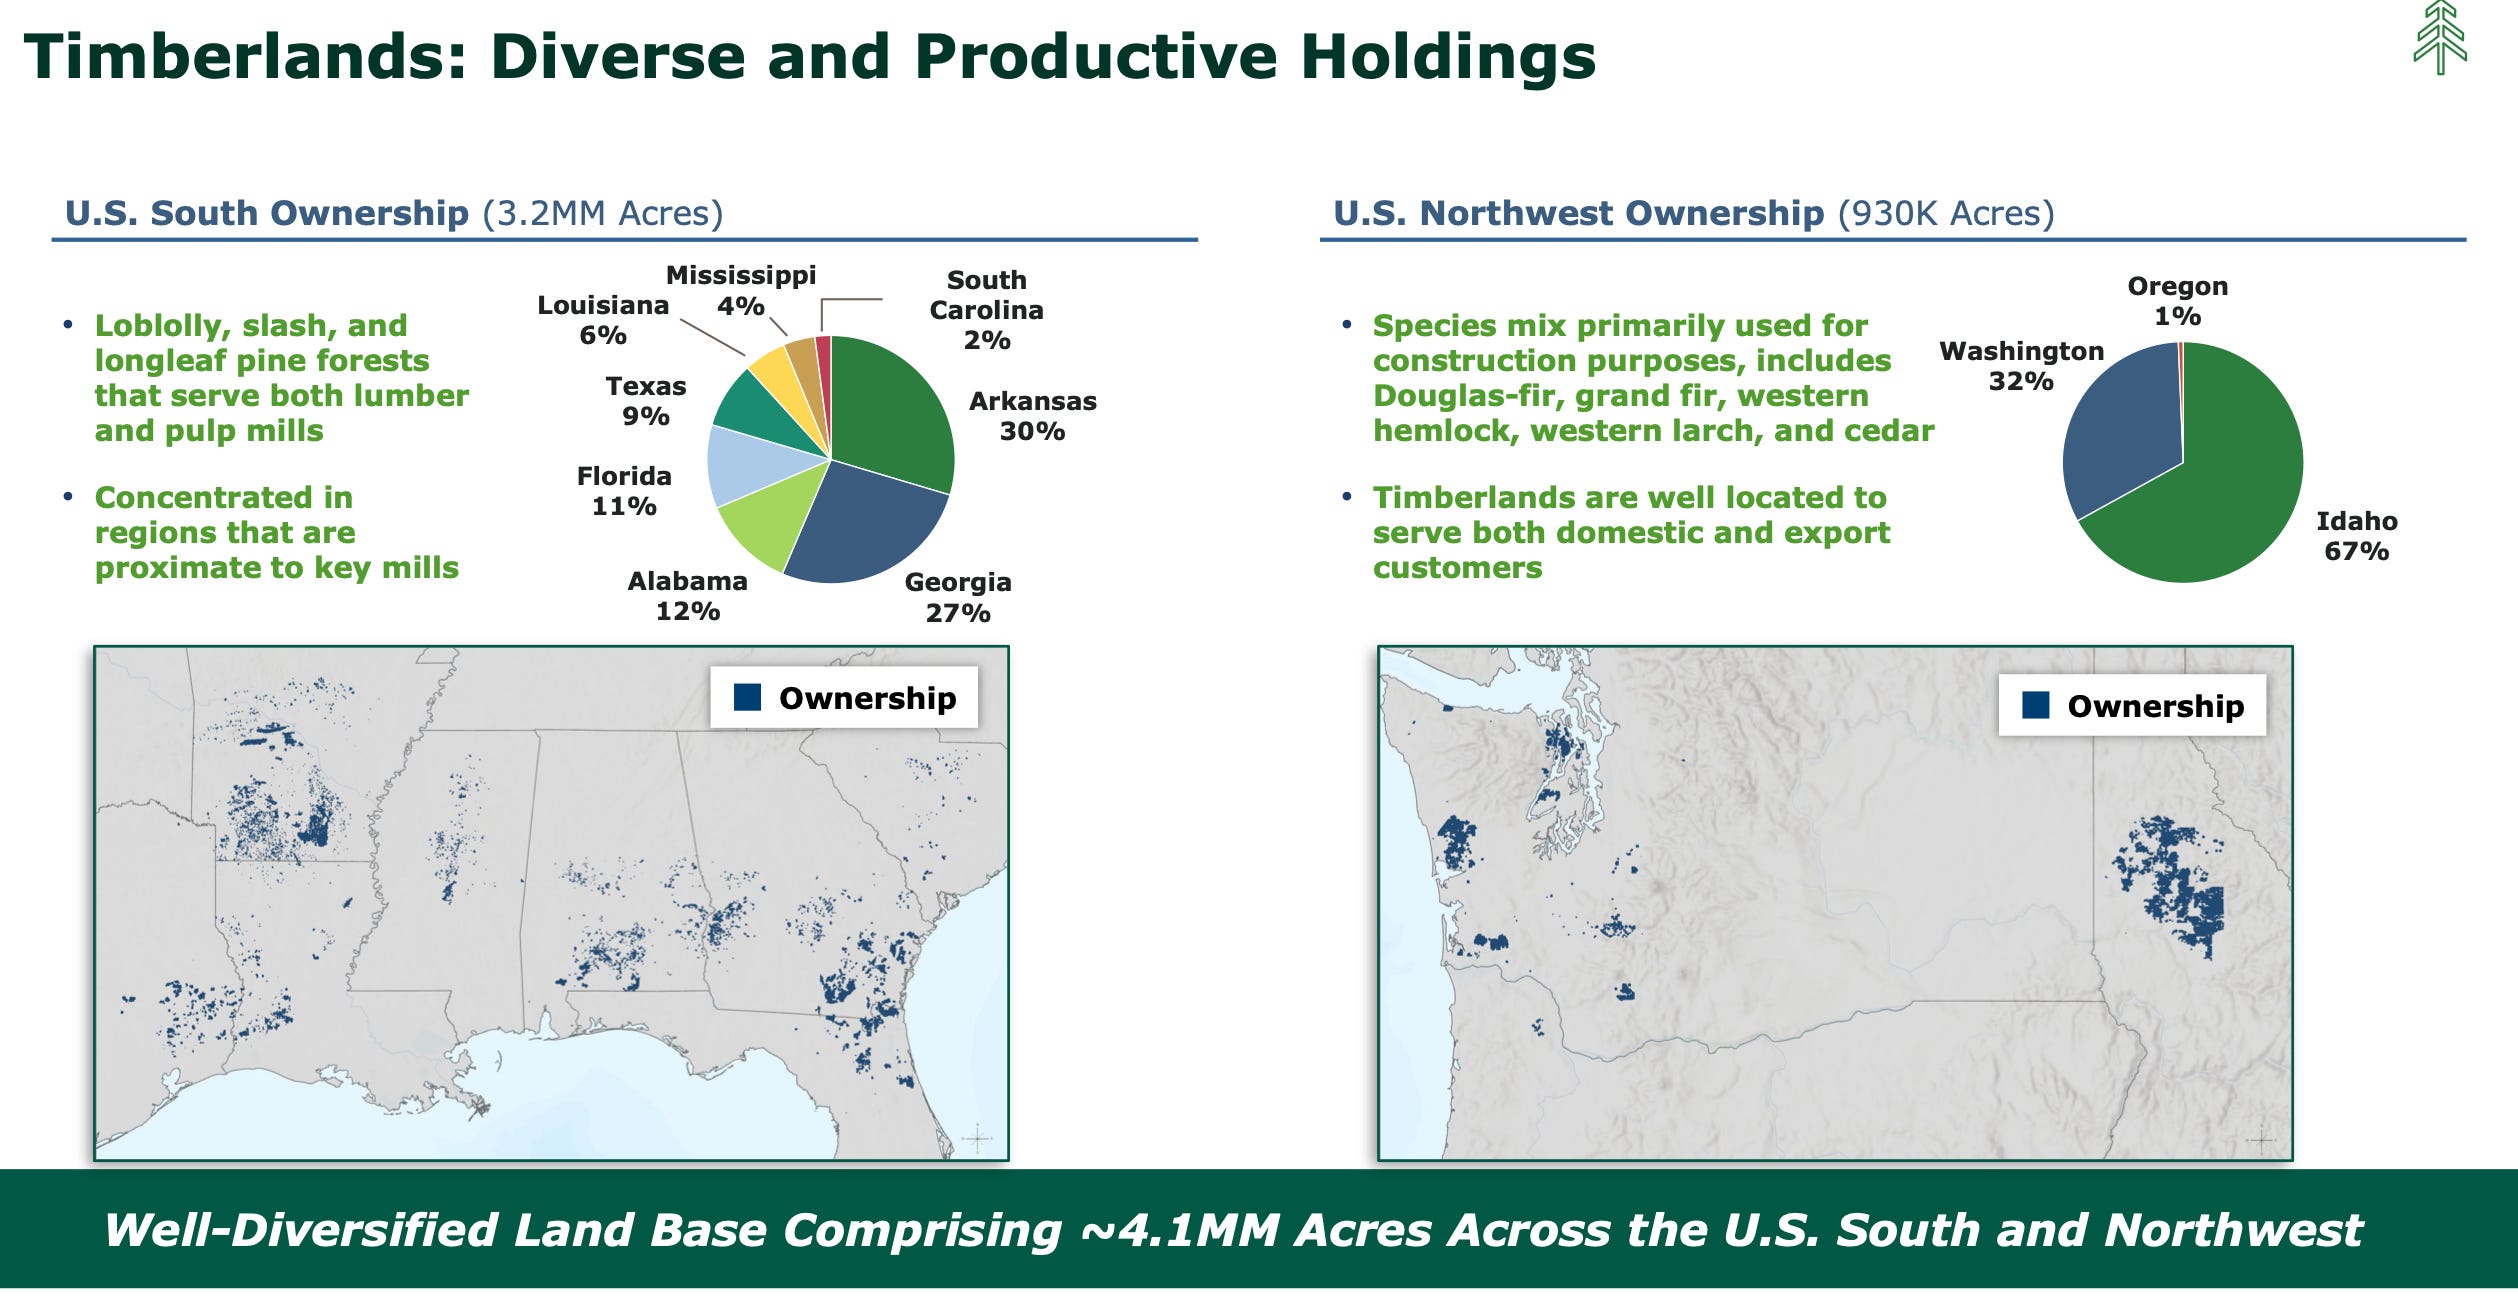
Rayonier’s 4.0 million acres are valued at $393 an acre after other assets, versus $1,200 to $1,800 cutover-land sales, framing the timber…
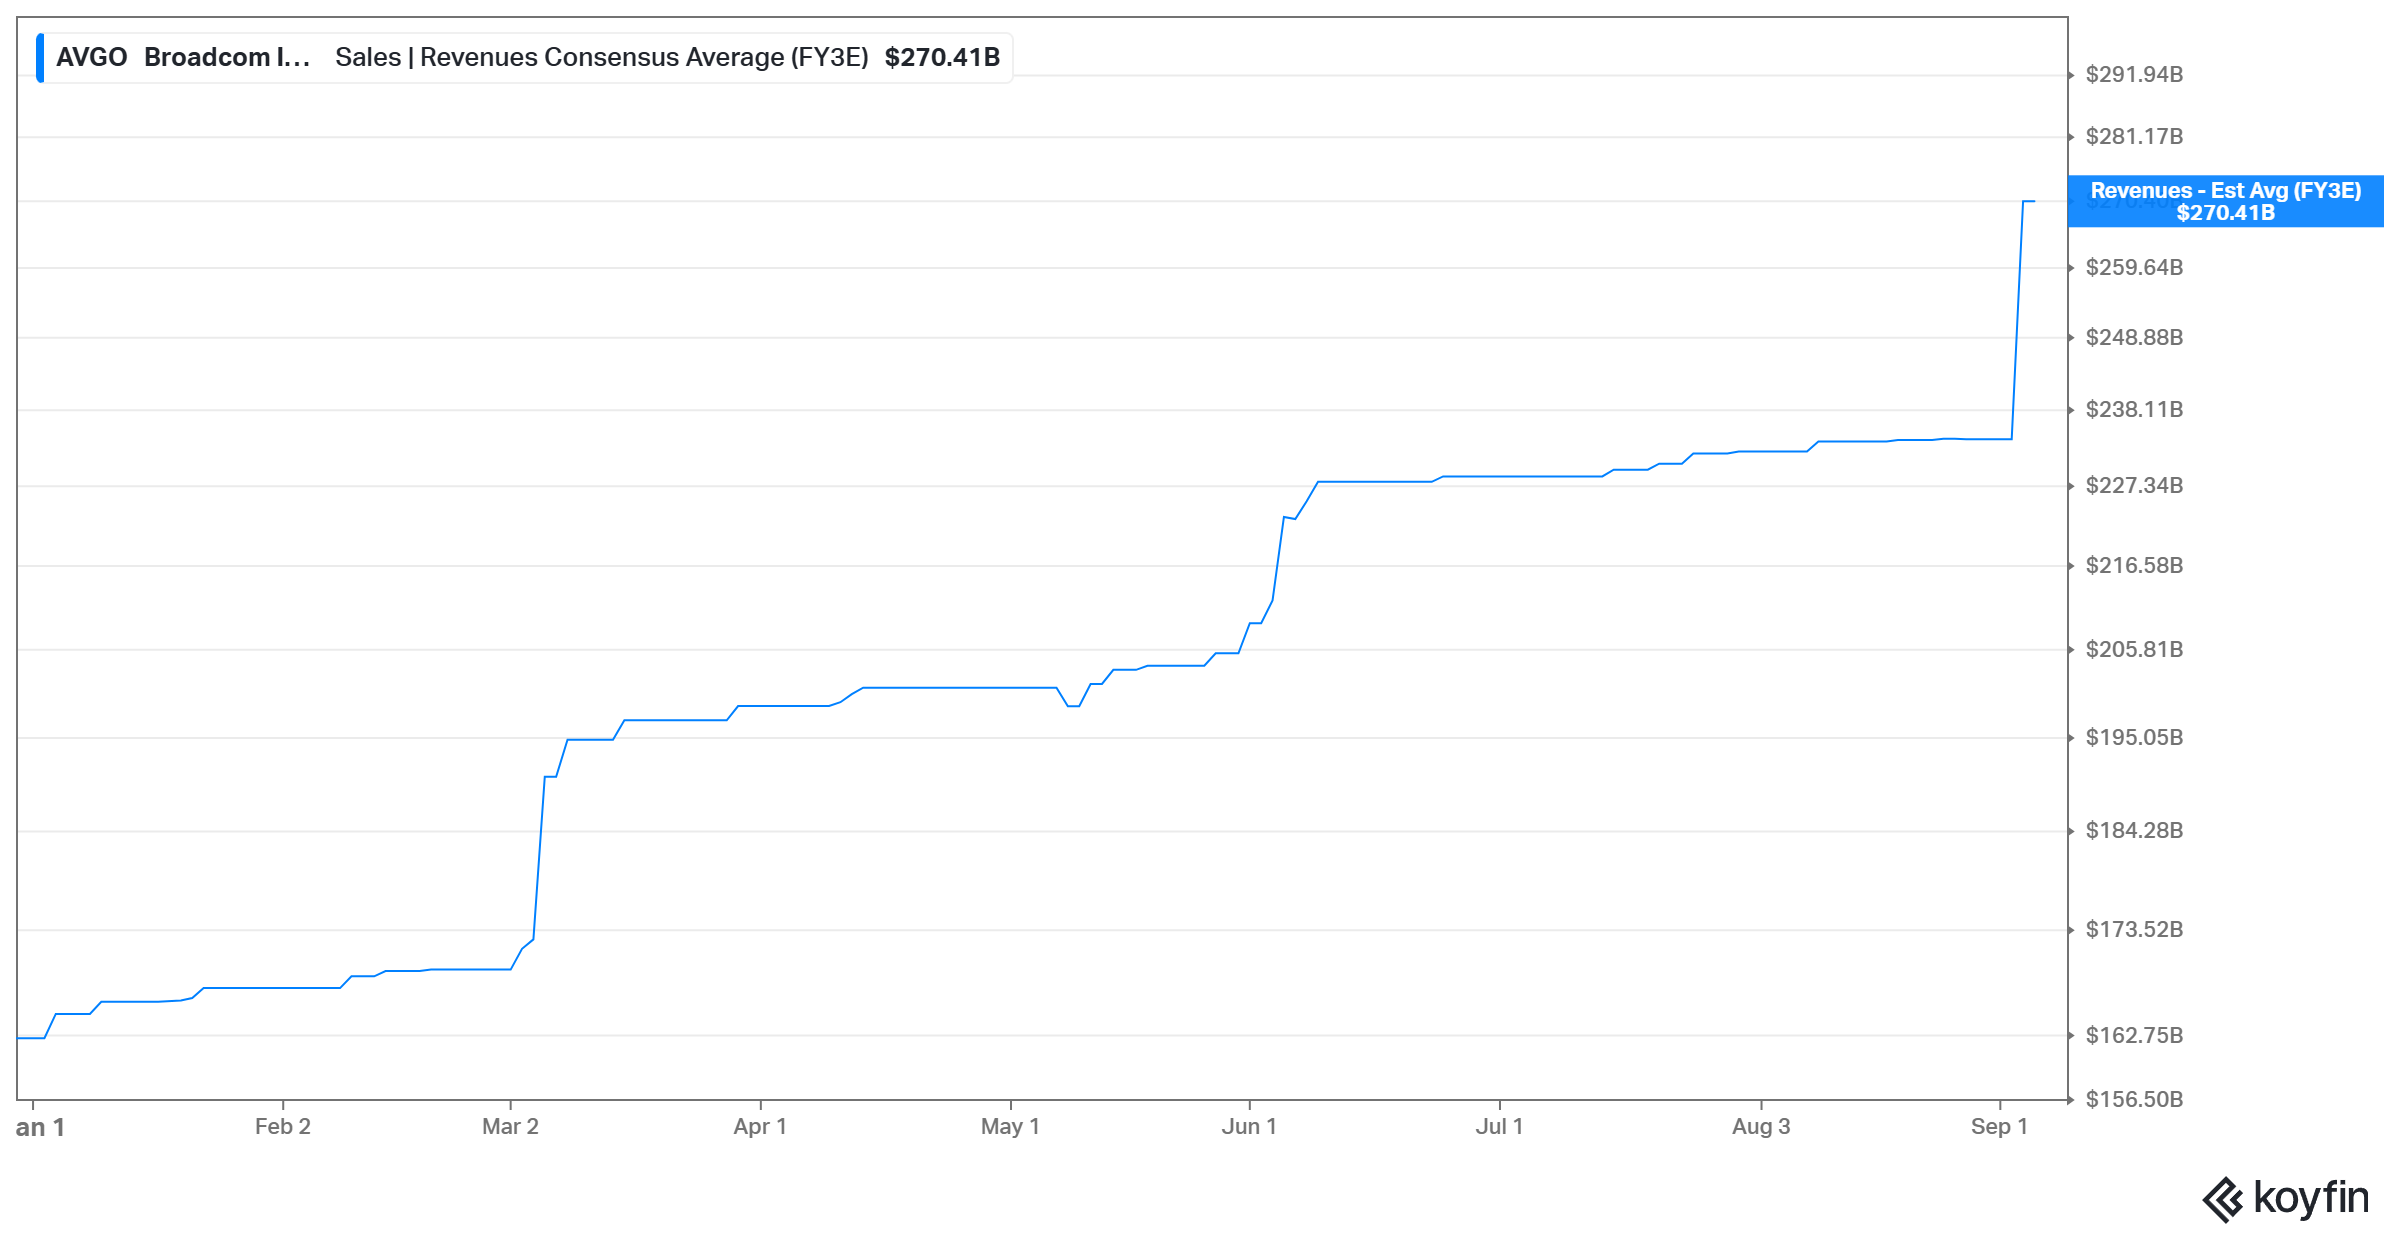
Broadcom’s FY2028 revenue estimate rose from $162 billion to about $270 billion and EPS from $17.60 to $30, while the stock remained flat…
Equinor’s H1 2026 net income doubled to $7.94 billion as European gas prices rose, but EU energy-crisis measures could curb profitability.
 Zoltan Ban 4 clicks
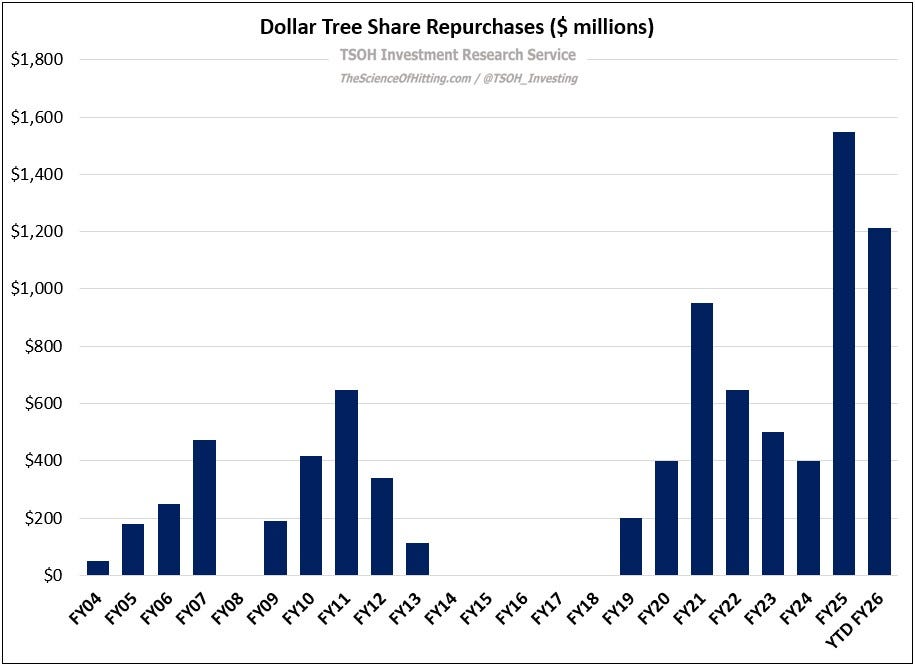
TSOH Weekly Roundup covers Costco’s $4.99 chicken supply chain, Celsius’s 20% energy-drink share, and California utilities’ wildfire…
Broadcom's AI semiconductor revenue rose 221% year over year as custom silicon programs and VMware software cash flows fund further…
Simple Investment Ideas 3 clicks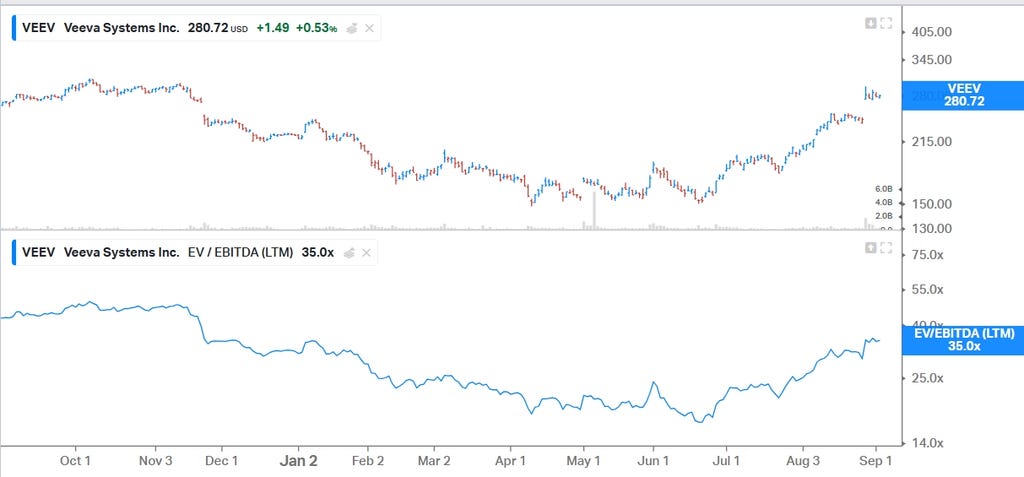
Veeva targets CRM share gains from Salesforce migration delays while Falcon agentic labor expands its reach into life-sciences safety,…
CME perpetual-futures activity is tested against more than 240,000 CFTC data points on open interest and dealer positioning.
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.