ContextLogic Acquires gChem (LOGC): Update and Valuation
ContextLogic will acquire specialty-solvent maker gChem for $850 million, funded by a $650 million rights offering and $250 million of debt, expanding Abrams Capital’s acquisition platform.
ContextLogic will acquire specialty-solvent maker gChem for $850 million, funded by a $650 million rights offering and $250 million of debt, expanding Abrams Capital’s acquisition platform.
@TidefallCapital I think macro beer is still deeply challenged, though I own a little bit of $TAP and $ABEV. I'm much more confident spirits will recover.
“Huawei’s report on its progress gave Ding leeway to be more aggressive. He delivered a blunt warning to China’s largest AI users, according to people familiar with the message: Anyone who resisted employing domestic chips was a traitor.” $ACMR https://t.co/2DDOgMTQEW
$SNAP will generate more FCF this year than $GOOGL and maybe more than the hyperscalers combined in the 2H ex MSFT! Just sayin...
Anybody like $DOMO here? Trading at $3.67 when they will have circa $4.84 in net cash after the sale closes + $900m in NOLs (at a 21% tax rate, that's worth $4.50 to the equity) https://t.co/UwaAd0UkLL
Good, solid quarter from $BWMX https://t.co/rRzlwT85tX
$THC smoked the hospital narrative and HCA, with a beat, raise and $2 Bn additional buyback. Bears might not be ambulatory for long… https://t.co/Jqp3snqr1l
$STIM https://t.co/VyAQNzsKuH
Tecnoglass could recover tariff- and FX-hit margins as U.S. blanket tariffs on Colombian goods lift.
Scholar Rock’s apitegromab could become the first muscle-targeted SMA therapy by September 2026, but manufacturing setbacks and a…
 Equity Eagle
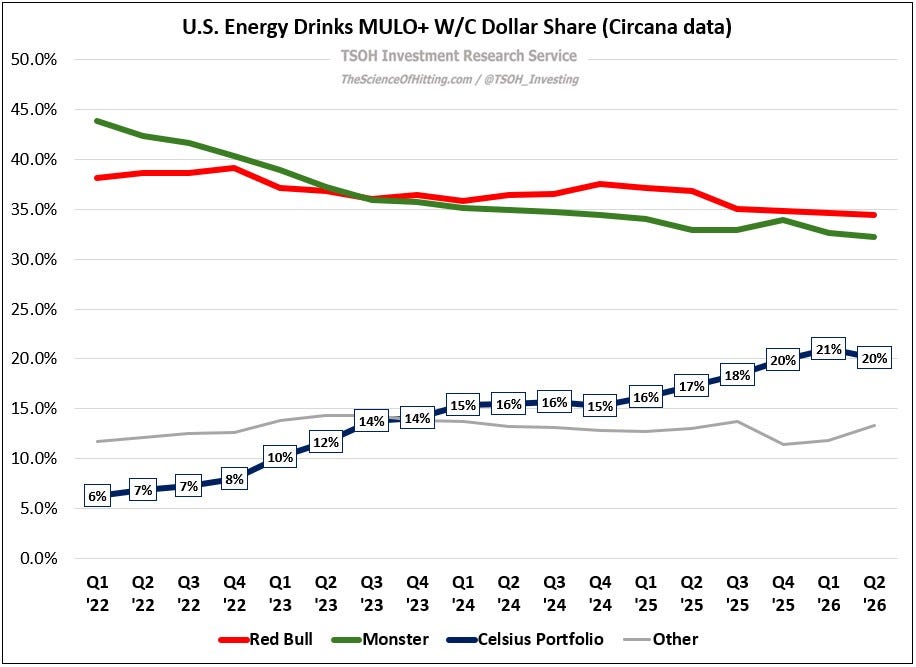
Celsius holds 20% of the U.S. energy-drink market and 40% of sugar-free sales, but its $1.65 billion Alani acquisition complicates…
On Holding $ONON combines a high-margin direct-to-consumer footwear model with replacement-driven demand, after Q2 2026 sales rose 21.6%…
National Vision Holdings' 2.2% same-store sales growth masked a 4.9% transaction decline, while inventory rose 37% and deferred marketing…
 Number Cruncher 1 click
Titan Mining reported Q2 revenue of $25.7 million and adjusted EBITDA of $9.6 million as zinc output rose, while advancing its Kilbourne…
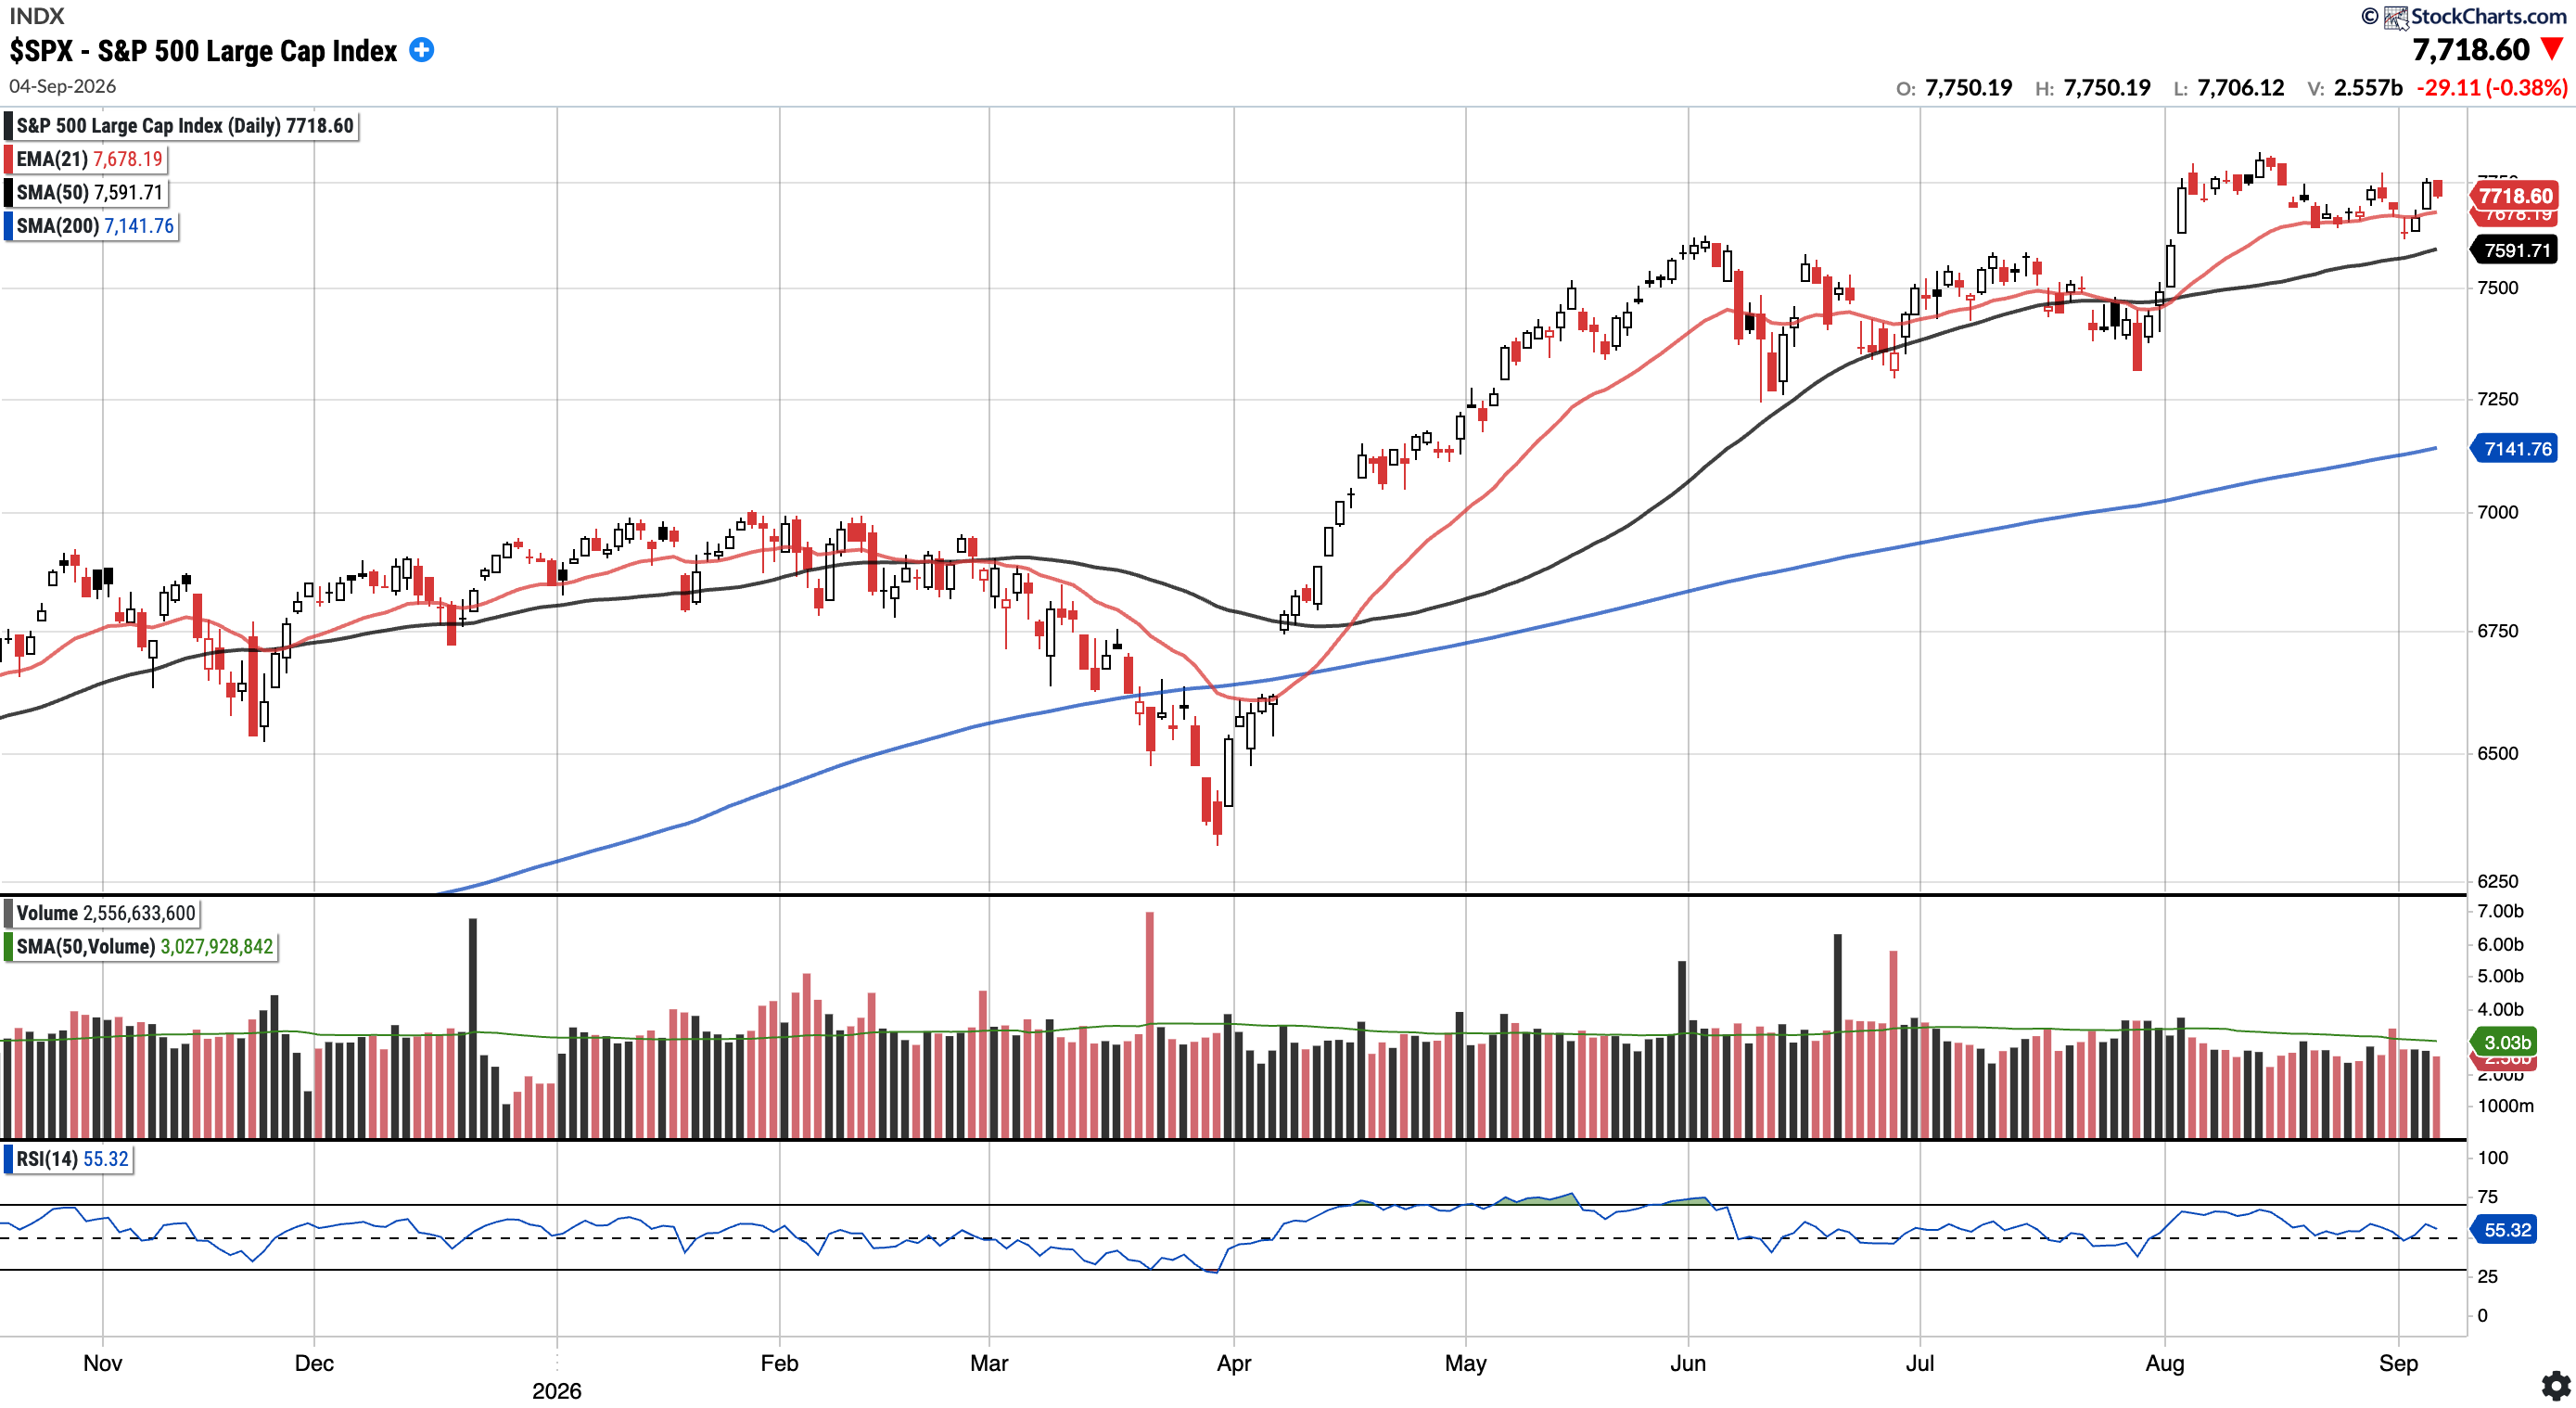
U.S. CPI and PPI headline the September 7 week as the S&P 500 holds key averages, Bitcoin faces $82,000 resistance and gold tests its…
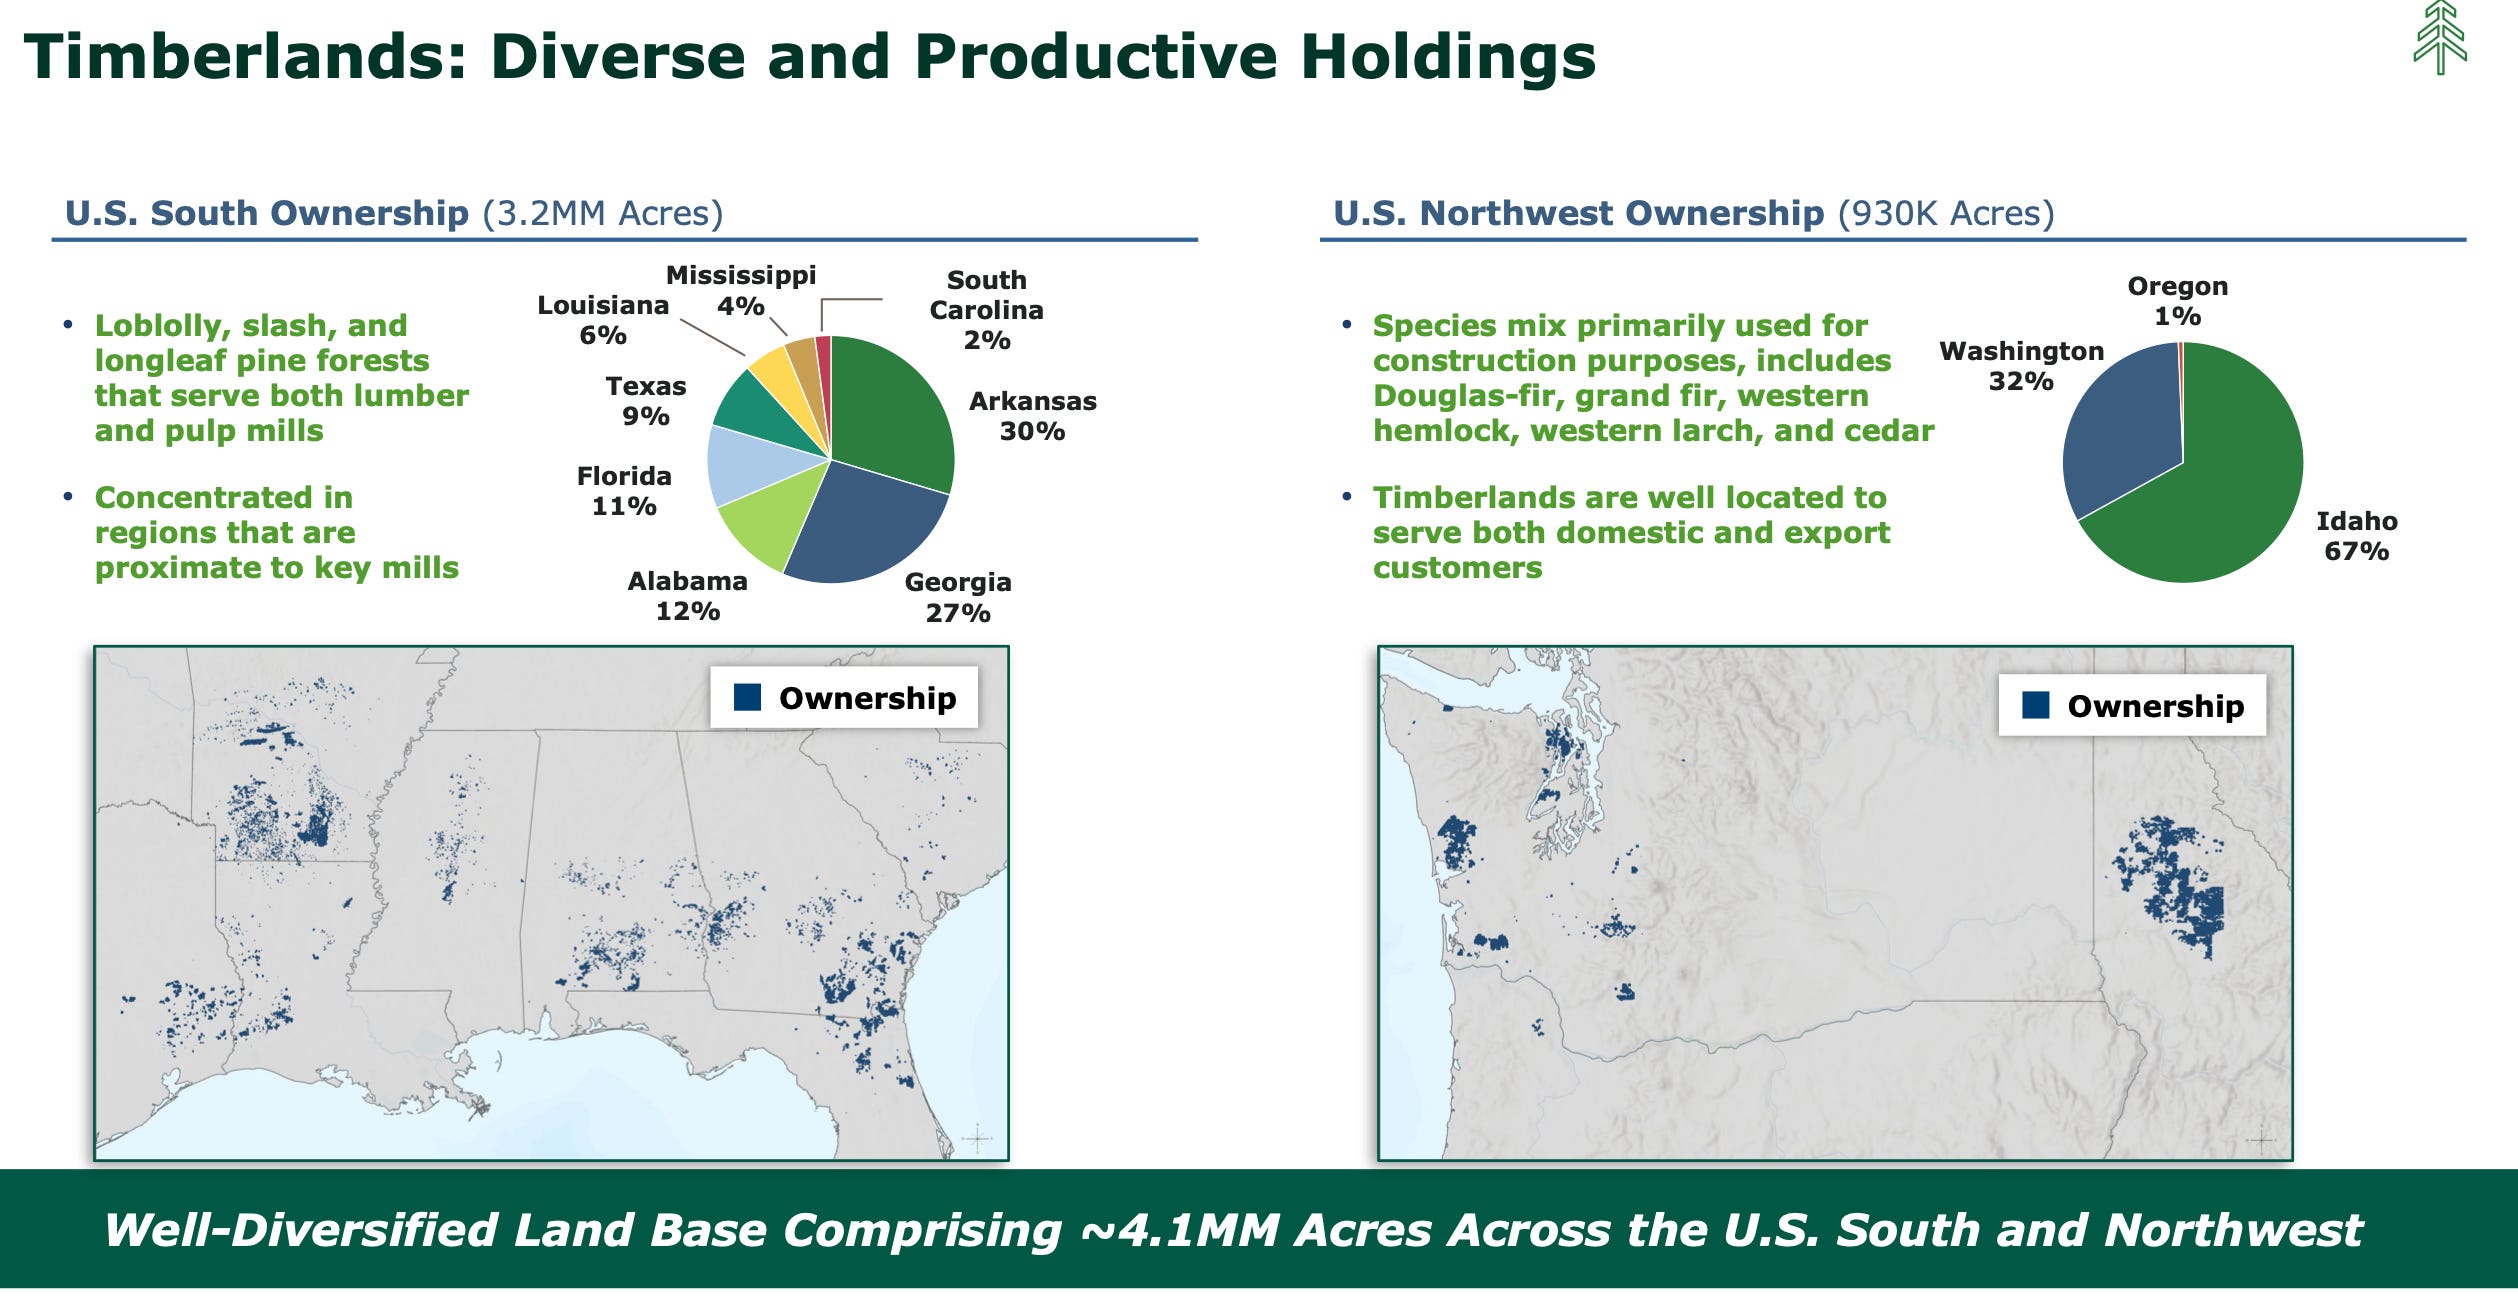
Rayonier’s 4.0 million acres are valued at $393 an acre after other assets, versus $1,200 to $1,800 cutover-land sales, framing the timber…
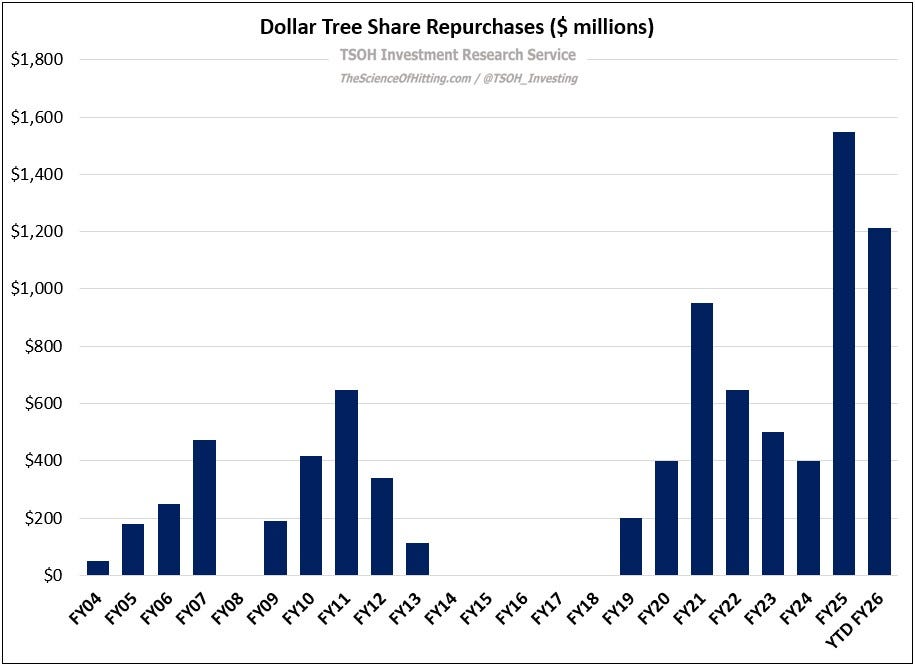
TSOH Weekly Roundup covers Costco’s $4.99 chicken supply chain, Celsius’s 20% energy-drink share, and California utilities’ wildfire…
Southwest Airlines is adding ancillary fees, assigned seating and premium products after a 6.7% Q2 adjusted operating margin, targeting up…
 Tim Dunn
 MGRC · long
McGrath RentCorp's conservatively financed hard assets, pricing growth and a struggling competitor, WSC, underpin the long thesis.
Pinterest’s Q2 showed reaccelerating North American growth, while weaker international trends, AI-related engagement risks and elevated…
 Richard Durant 2 clicks
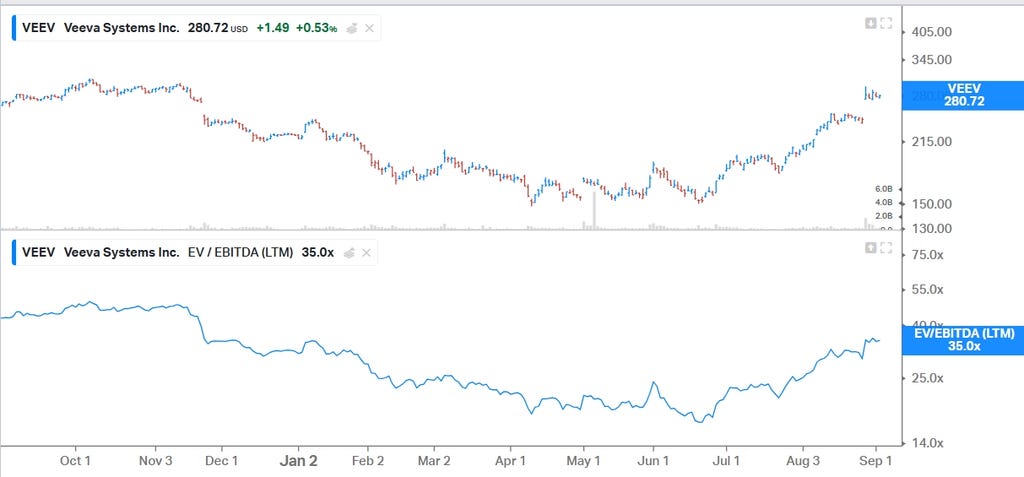
Veeva targets CRM share gains from Salesforce migration delays while Falcon agentic labor expands its reach into life-sciences safety,…
Intuit targets 9.1% FY2027 revenue growth and 23% EPS growth after Q4 revenue rose 13.7%, supported by Global Business Solutions, Credit…
 Treading Softly 5 clicks
CME perpetual-futures activity is tested against more than 240,000 CFTC data points on open interest and dealer positioning.
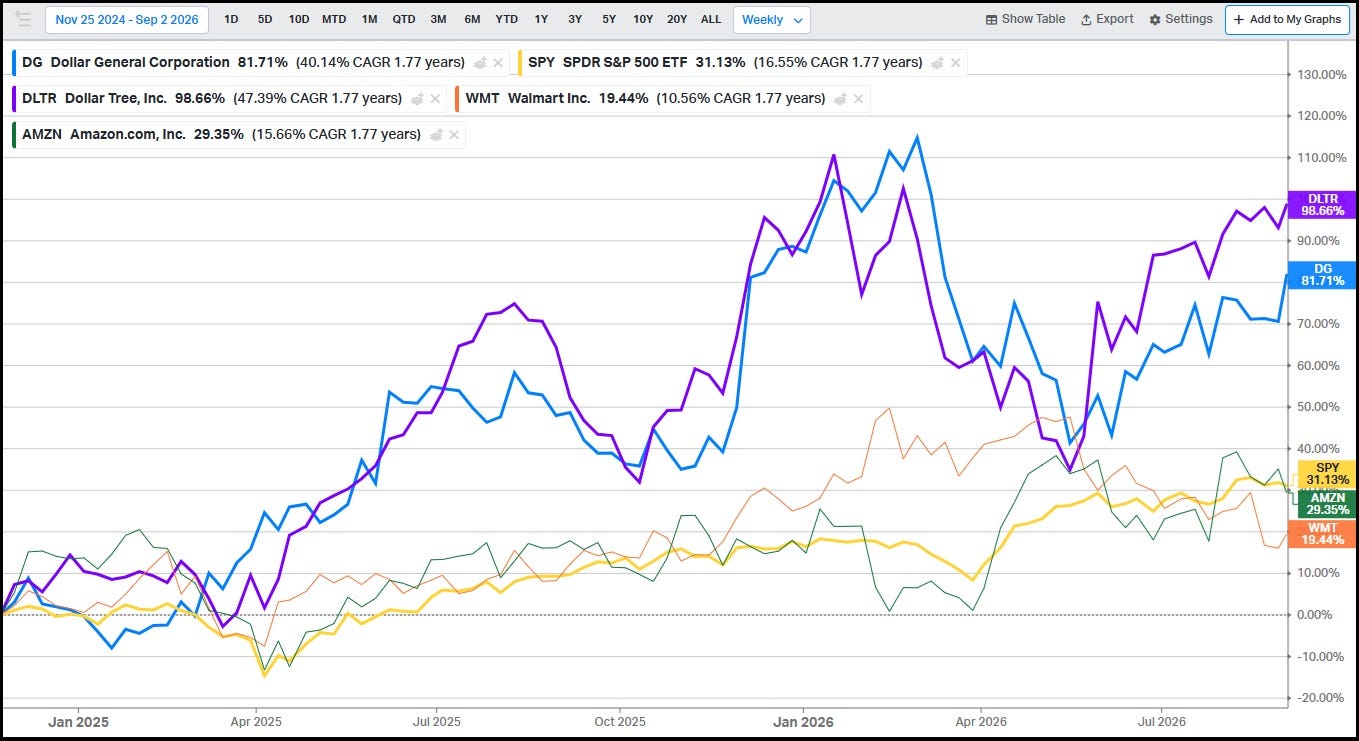
Dollar General’s Q2 FY26 comparable sales rose 3.5%, beating Walmart U.S.
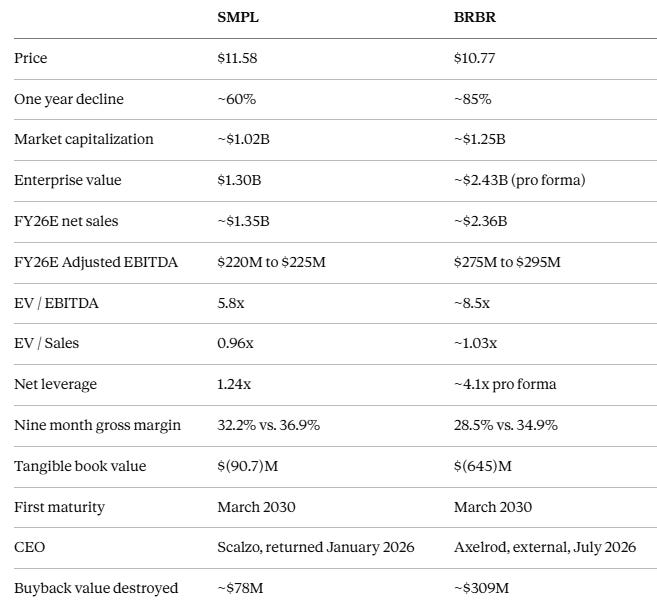
Two U.S. protein-snacking companies lost $6 billion in market value as impairments, inventory growth and margin pressure test whether the…
DoorDash’s delivery economics rely on customer tips and flexible labor, while rising courier costs make autonomous delivery central to…
IREN’s AI contracts now include customer prepayments covering 45% to 55% of GPU CapEx, while three-year pricing has risen 125% since…
 Quantryon Capital 5 clicks
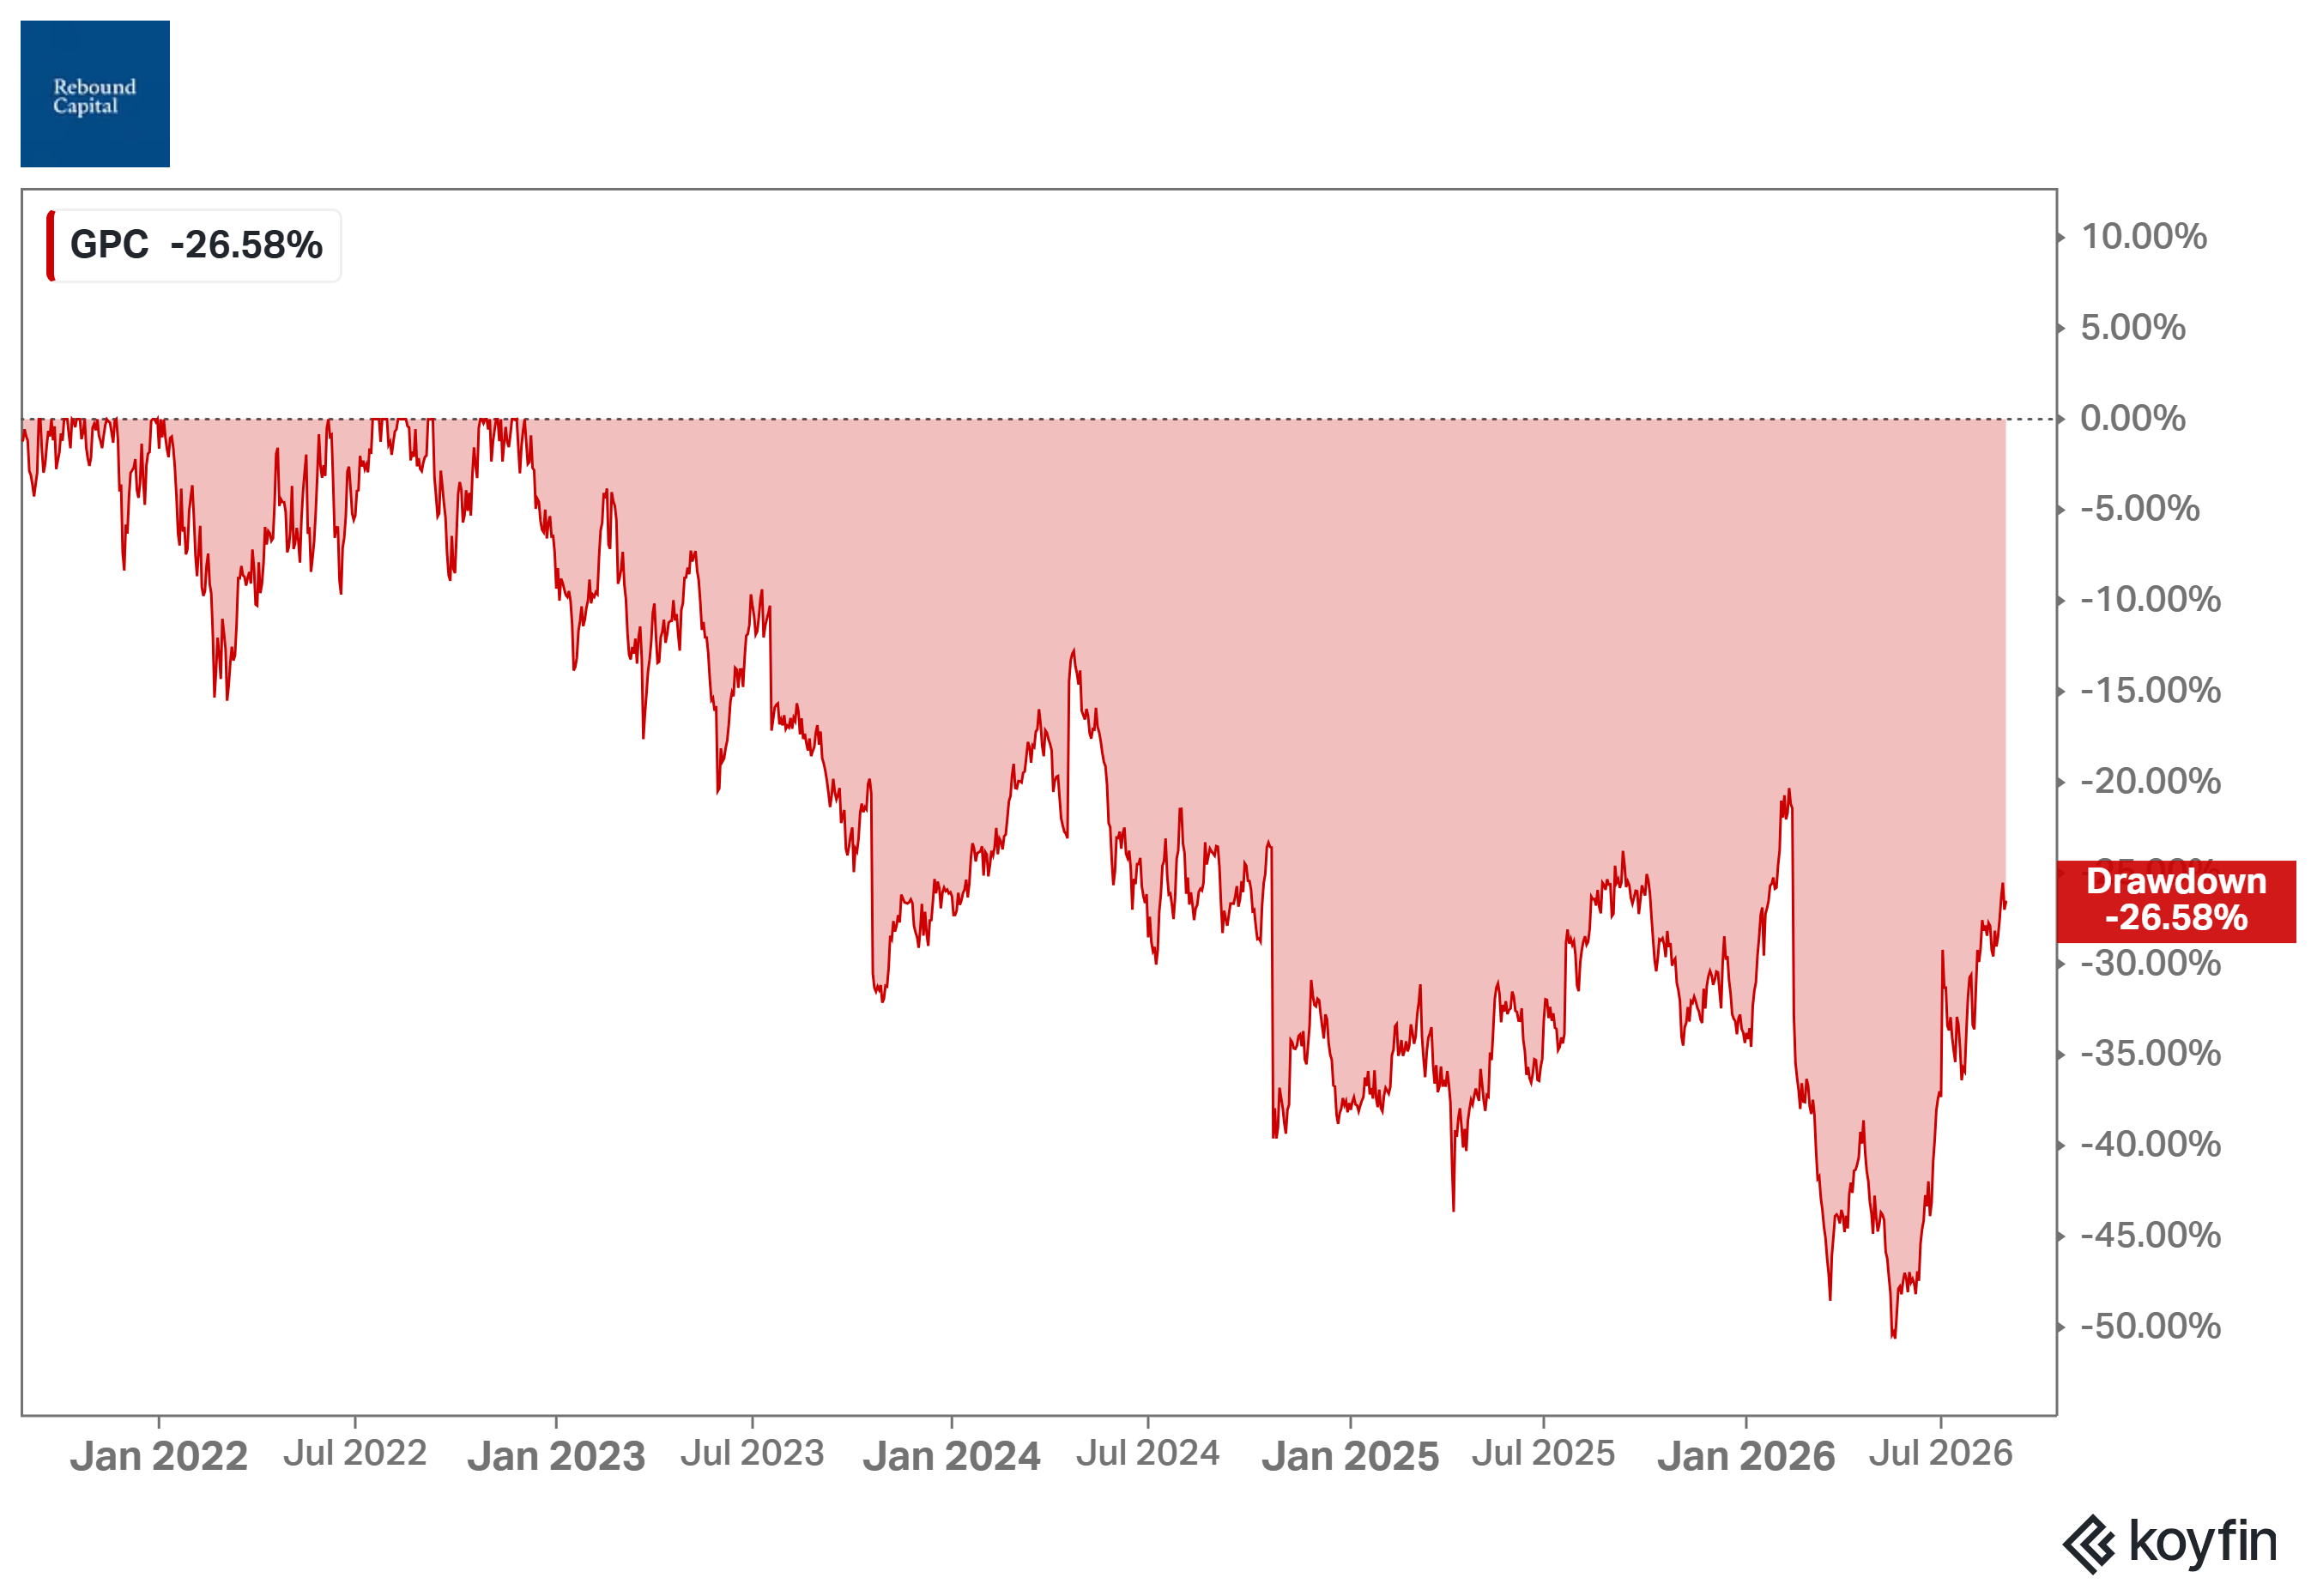
Genuine Parts Company is one of eight potential rebound stocks on RC’s September 2026 watchlist.
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai Equity Eagle
 Eudaemon Research
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.