The Non-linear Economics of Grocery Delivery Basket
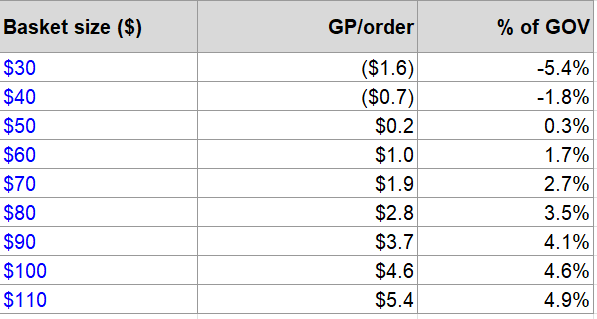
Instacart’s larger grocery baskets create disproportionately better delivery economics than DoorDash’s, making half the basket size worth far less than half the profit.
Instacart’s larger grocery baskets create disproportionately better delivery economics than DoorDash’s, making half the basket size worth far less than half the profit.
$PLUS Accelerating decline: Networking -37% (largest category), Product sales -18%, zero margin/ low quality Professional services now 15% of sales. Cut FY2026 top and bottom-line guide by 7% w further cuts almost certain to come. Trading at 14x 2026 guidance vs peers at 6-8x.
$ACA Levered roll-up (4x levered) hodgepodge of low-quality cap intensive commodity businesses w struggling end-markets (sub-scale aggregates, building products, ag). Negative organic growth w unrealistic guidance. Forced to sell an asset to avoid covenant breach. 30x P/E
$DAKT Just won the massive jumbotron project for the new Titans stadium. Estimated to be $180M. Will be the largest set of displays in the NFL. Bills, Browns stadiums to be announced soon. Wouldn’t be surprised if Mitsubishi acquires them given interest in the category.
$NX 5% of COGS/ direct input costs sourced from China. Tariffs + zero pricing power, high fixed cost structure + only 30% GMs = 25-30% hit to EBIT. Add 4x leverage, declining volumes, ambitious mgmt guidance while integrating a large acquisition is a setup for a trainwreck.
$AVO calling out the fact that they have been overearning and margins reverting. “experienced normalization of our per unit avocado margins during in Q1.” Noted weak harvest anticipated in Mexcico. $CVGW will be even more adversely impacted by these factors.
$DAKT CEO departing, new high-quality CFO (temp) w very attractive secular tailwinds in digital display demand + activist involvement = increased likelihood of takeout. Optimal business for PE. Multiple logical strategics. +75% upside.
$FTDR Vol declining (existing home sales=driver). Pricing lagging inflation, massively over-earning. Problematic given 25% churn w aggressive new entrants. Dubious company overall. Investor day yesterday was comical, compared themselves to $NFLX. Earnings misses coming.
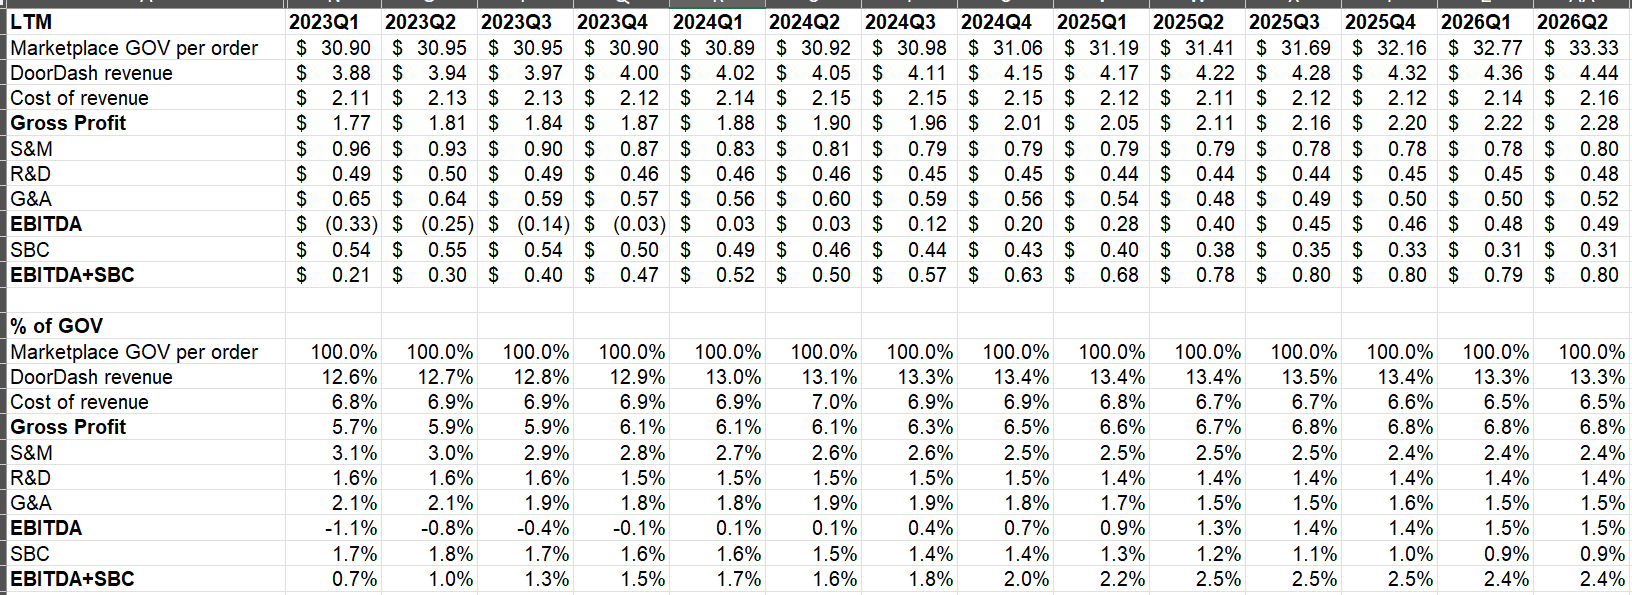
Instacart’s per-order unit economics provide a benchmark for assessing DoorDash’s LTM profitability and operating model.
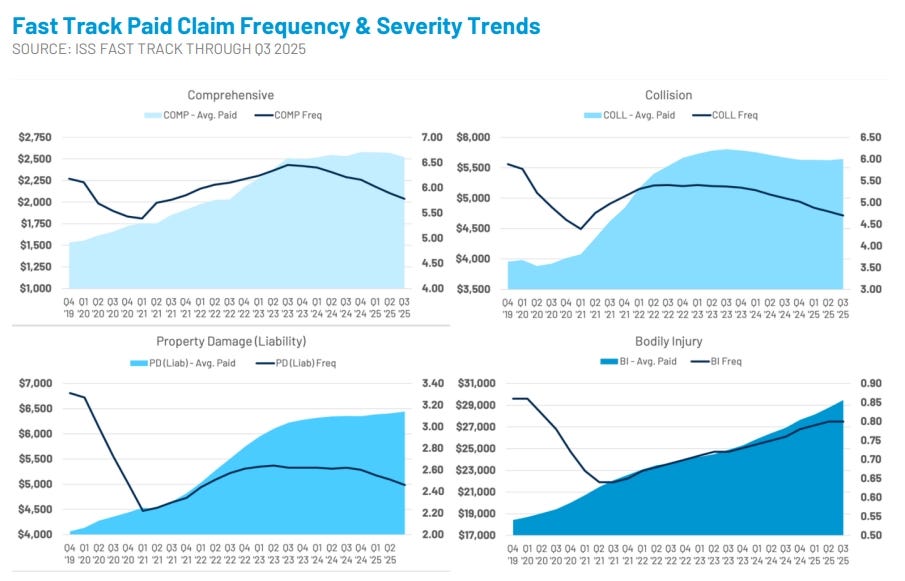
CCC, the dominant auto physical-damage claims estimator, connects 27 of the top 30 insurers with 31,000 repair shops as takeout rumors…
 TEM 2026-08-20
Tempus AI's diagnostics and data businesses grew Q2 2026 revenue 19.4% year over year, with FDA approvals, expanded tests and pricing aimed…
Verra Mobility's new seven-year Avis agreement replaces a customer worth over 10% of revenue on materially worse economics, exposing…
SA 2026-08-20 Seabridge Gold's KSM gold-copper project could re-rate on a joint venture, 2027 feasibility study and infrastructure progress, with gold…
 Redfern Research
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028…
PGY 2026-08-19 Pagaya Technologies reported Q2 2026 network volume of $3.54 billion, 19% revenue growth and 99% adjusted net-income growth, while trading…
 Akim Guerreiro
Jumia’s January 2028 $7/$15 call spread risks $1.15 for up to $6.85 if cost cuts and marketplace growth deliver adjusted EBITDA and…

IREN awarded each co-CEO roughly 9 million RSUs, about 2.5% of shares and $400 million, in exchange for no further equity grants until…

Nubank's 140 million customers, 20% efficiency ratio and 30% ROE frame whether its high-teens P/E reflects a scalable fintech or a maturing…
 DASH · long
DoorDash holds roughly 60% U.S. market share in on-demand restaurant logistics, underpinning a long thesis on its defensible delivery…
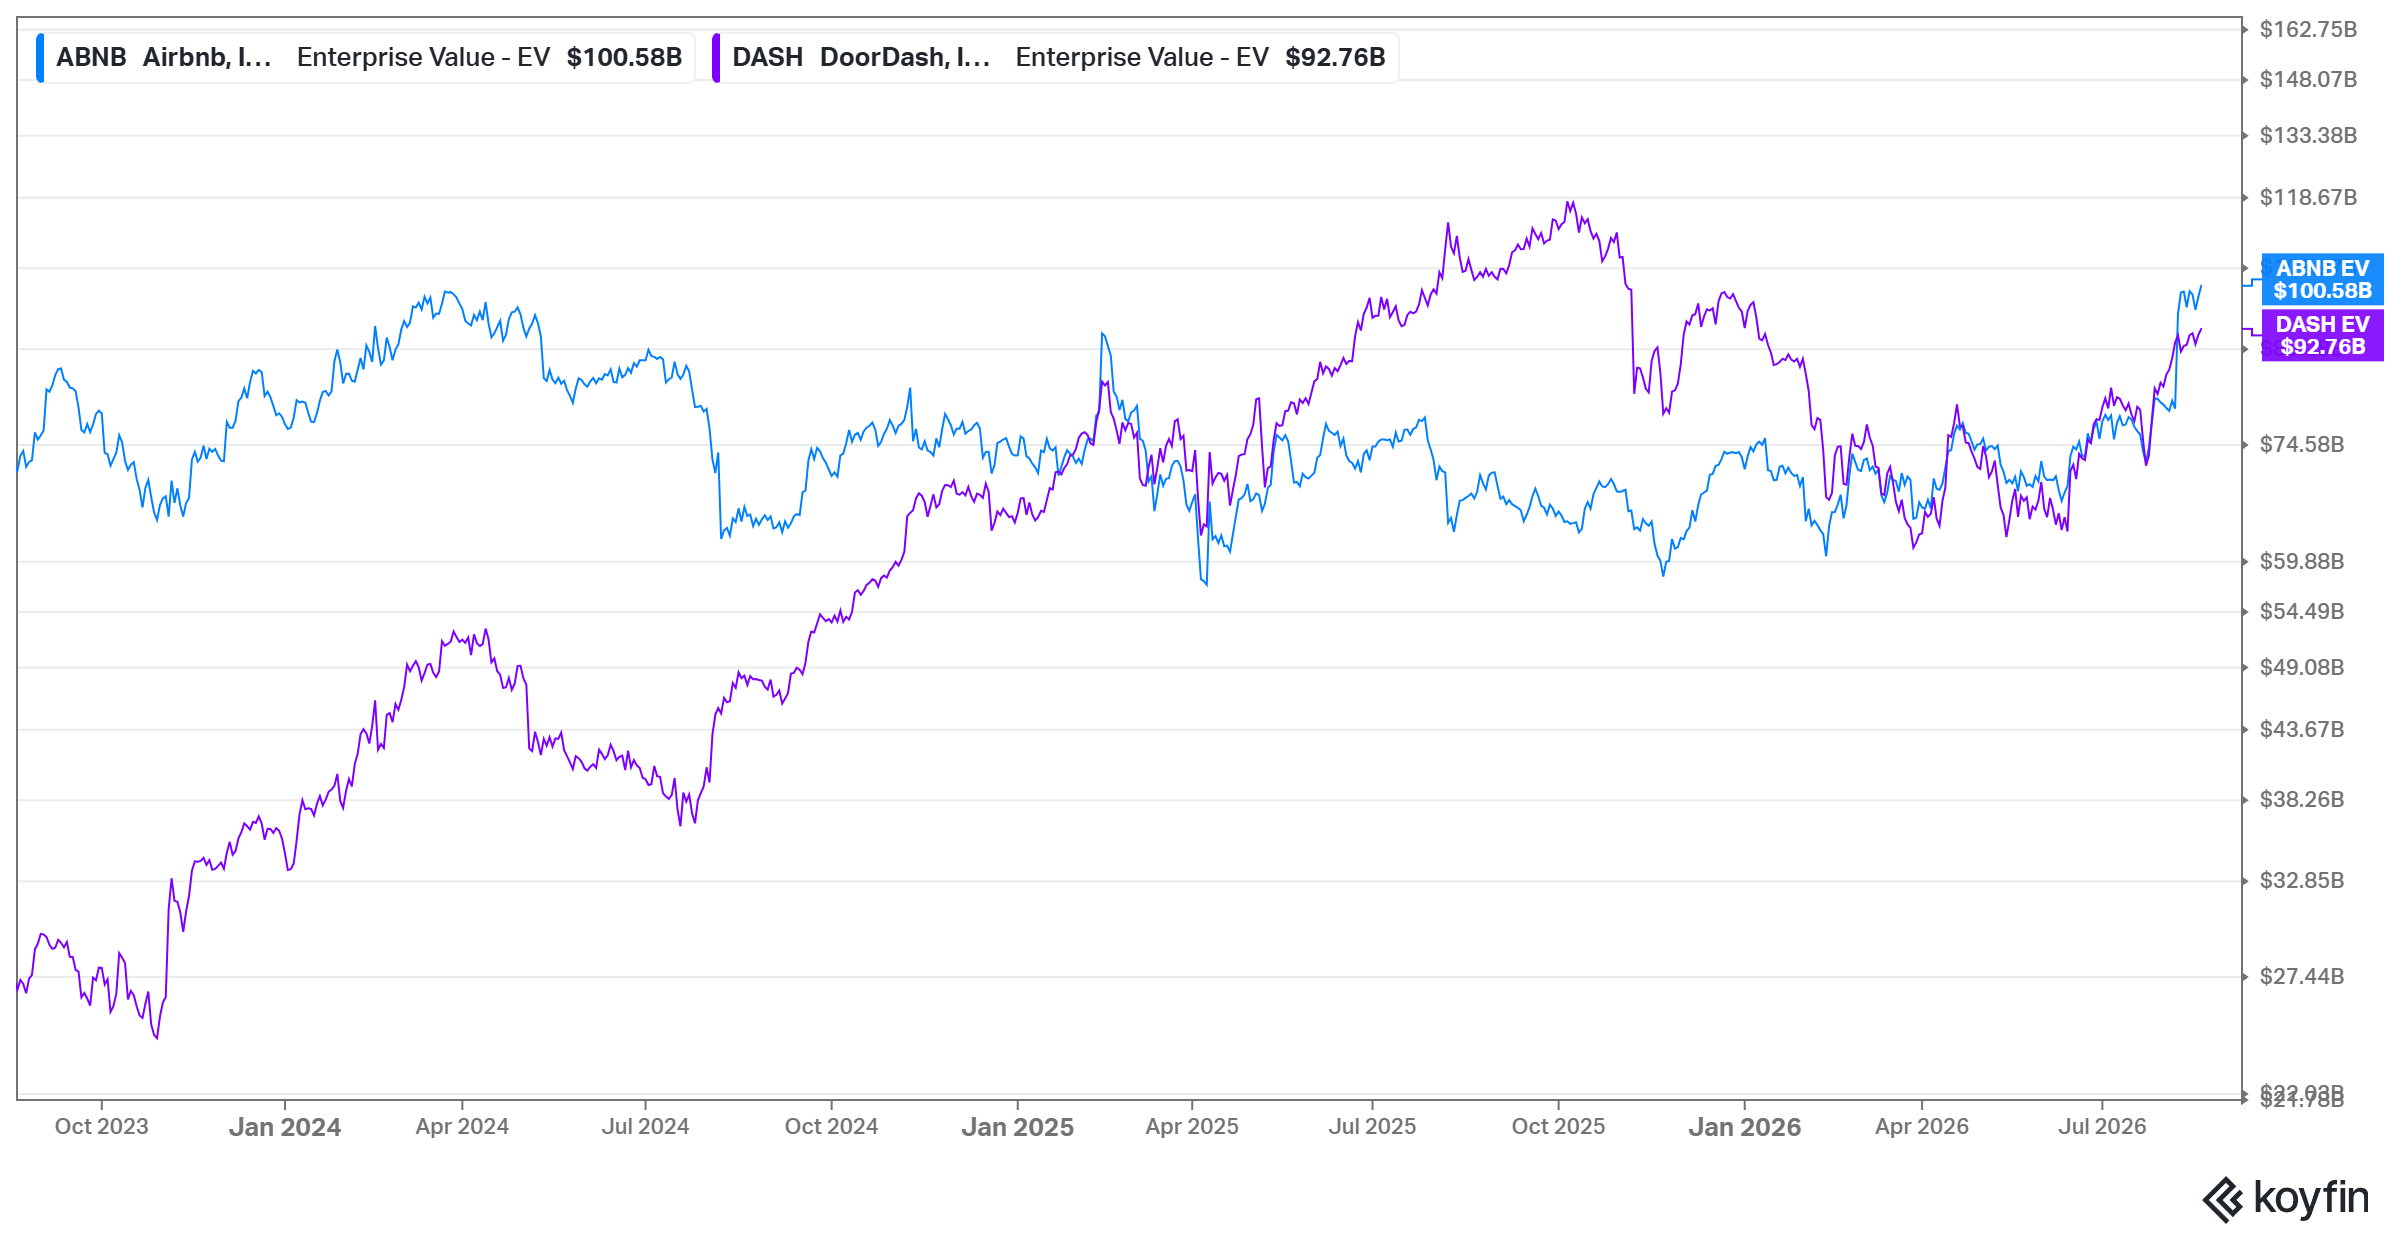
Airbnb shares have risen about 50% since October 2025, prompting a revised 2026 model and return assumptions at the current price.
CRWV 2026-08-19 CoreWeave’s Q2 converted backlog into sales, expanded margins and lifted operating leverage as active contracts topped half of its $104.2…
 Future Stack Investment
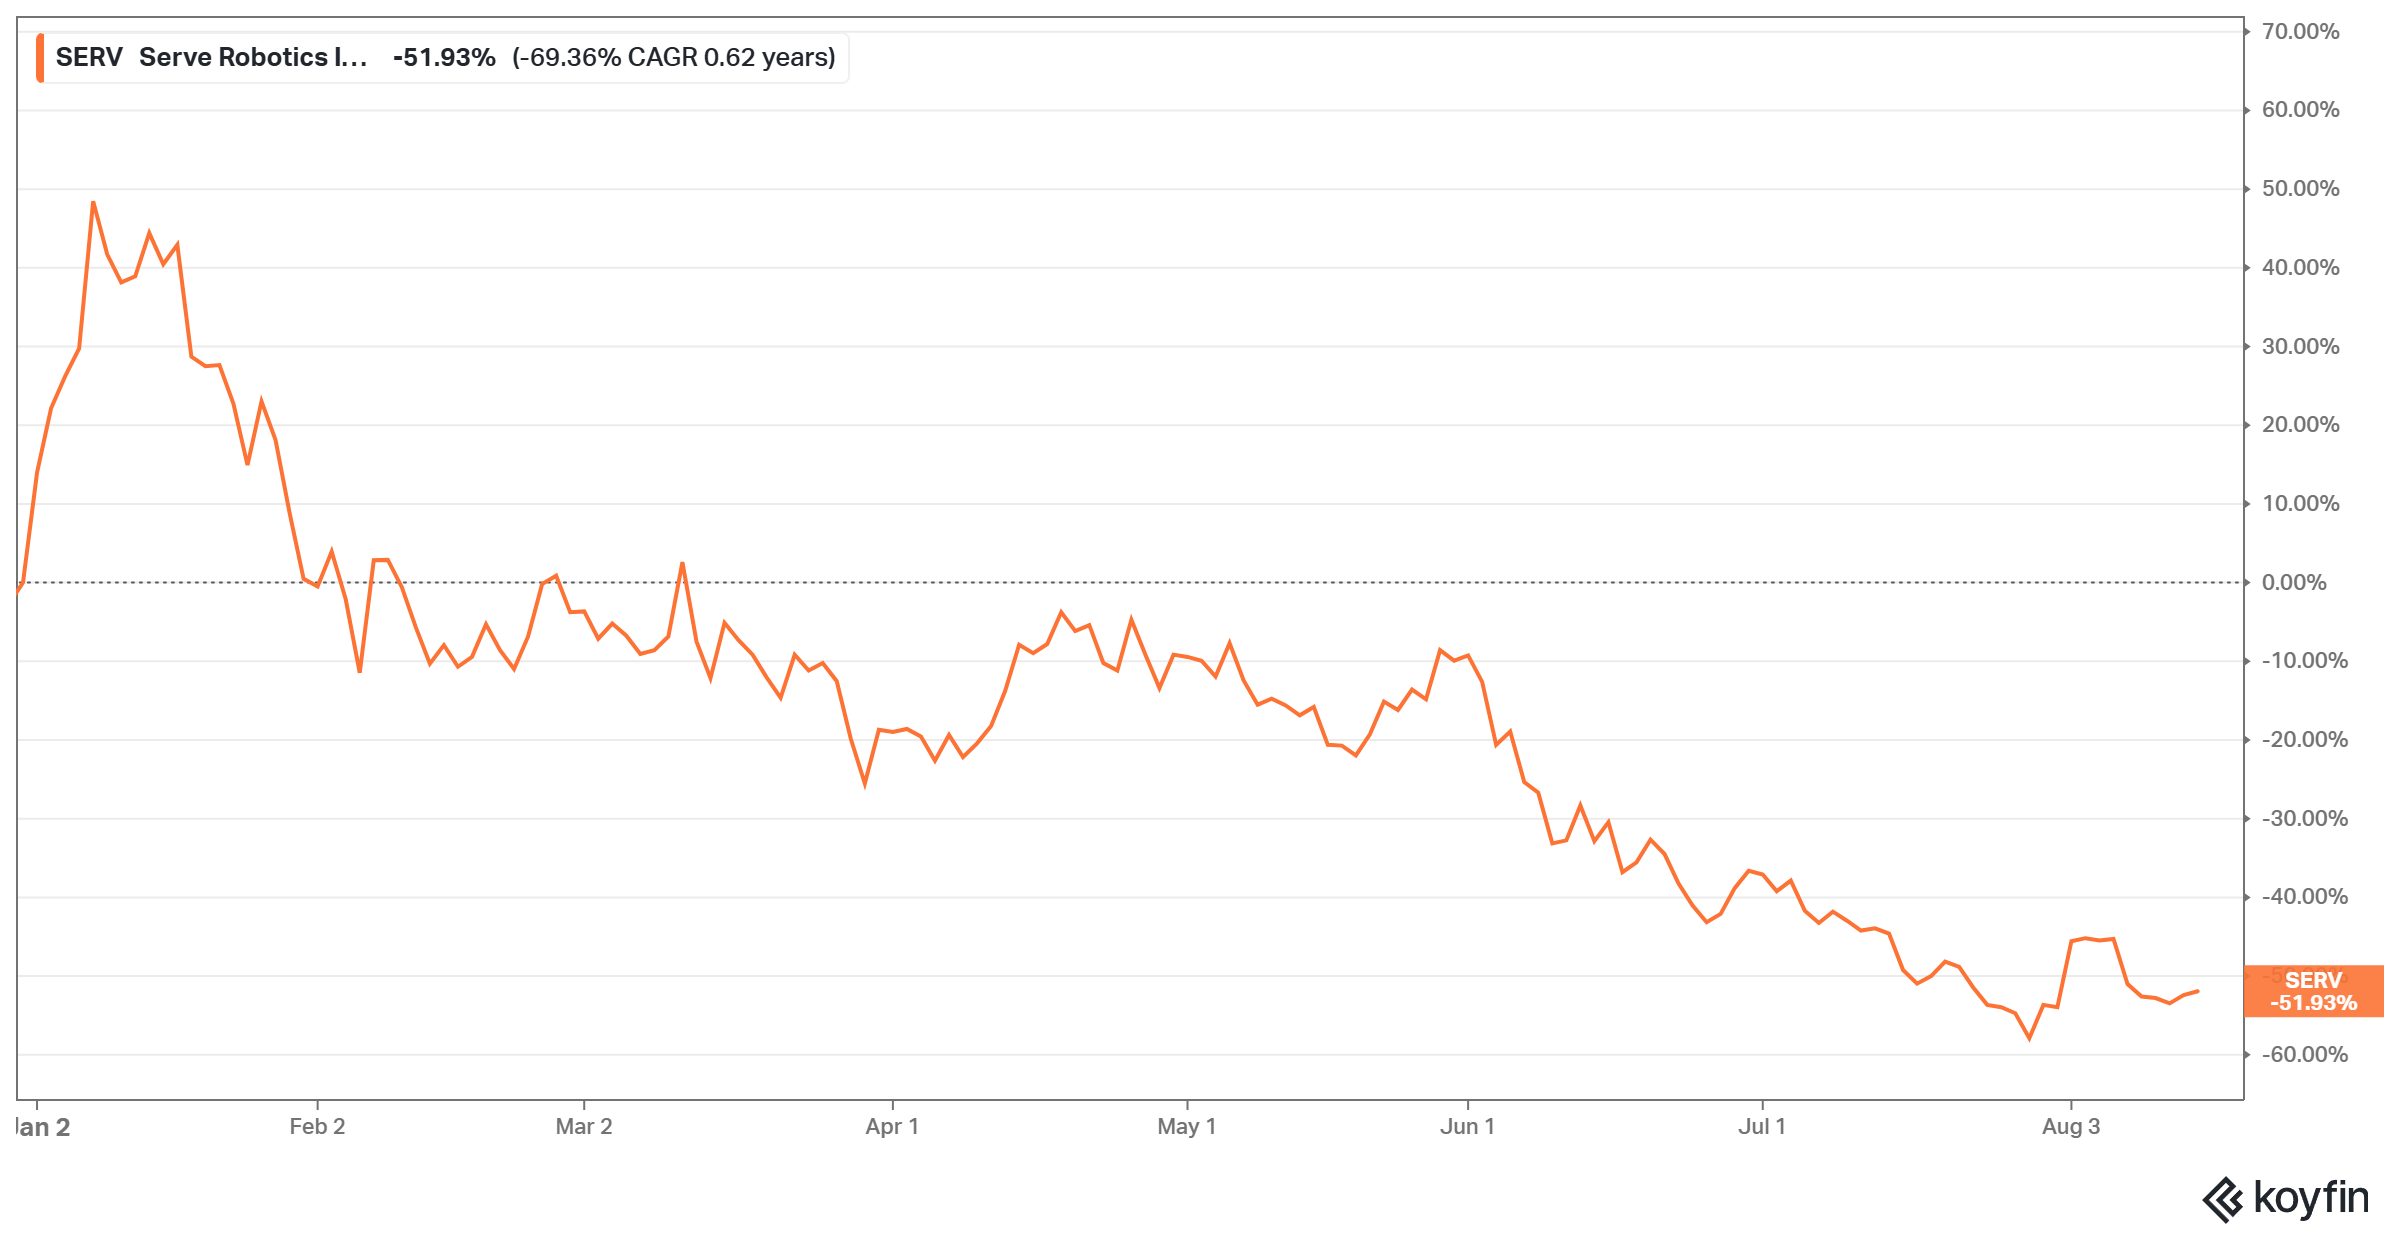
DoorDash’s integrated autonomous-delivery strategy contrasts with Uber’s 2026 divestment of Serve Robotics, its former delivery-robot…
E.W. Scripps, Team Internet, Monro, doValue and Inter & Co feature as special-situation trades involving mergers, asset sales, leverage and…
HubSpot trades near its 2020 share price despite quadrupled revenue and $750 million in free cash flow, with Breeze AI upside weighed…

DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.

CoreWeave and Nebius cite AI compute shortages and higher-priced GPU renewals, but older-chip utilization and depreciation vary across…
Macy’s and Kohl’s face renewed short cases as their recent reratings ignore fading store-refresh gains, credit-card earnings exposure and…
Zoetis’s U.S. companion-animal revenue fell 6% as dermatology competition drove rebates and discounts, pushing full-year net pricing to…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.