$DNOW: the boring distributor that could double on 2029 numbers | Firebird Management
DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
$FTDR Vol declining (existing home sales=driver). Pricing lagging inflation, massively over-earning. Problematic given 25% churn w aggressive new entrants. Dubious company overall. Investor day yesterday was comical, compared themselves to $NFLX. Earnings misses coming.
$AVO $CVGW 1) Retailers $CMG, etc sourcing elsewhere given MX tariff risk. 2) Avocado price spike during last year’s peak harvest season enabled distributors to realize outsized margins. 1-time benefit has reversed, significant earnings misses ahead for these commodity businesses
$NX Outlandishly guiding to flat 2025 sales, customers and channel -DD. Commodity window and door components facing pricing pressure from larger customers ($JELD, $OC). Now levered 4x, trading at a premium to higher value-add building products peers. Guide cut inevitable.
$J Beat earnings yesterday. Holding back detailed guidance for Investor Day (2/18)—likely raise ’25 #s, 4-year financial targets w significant upside on margins ($ACM and other peers +15% EBITDA margins). Record backlog and multi-year growth runway.
$NX Rapidly declining levered (4x) commodity biz. Q1’25 guide -12% sales, mgmt hoping for 2H’25 recovery. End-mkts deteriorating ($OC -20% Q4 guide, $JELD), customer losses, internal controls issues, integrating a large acq, 0 prior M&A experience. +30x P/E on best case 2025 #s
@StockJabber Thank you. As a read on $PLUS Q3 is tracking in October, $CSCO just reported -23% sales in networking (products account for ~50% of $PLUS revenue) for the Oct quarter-end. Further confirmation that PLUS Q3 is going to be ugly and no turnaround in sight.
$PLUS Accelerating, sales -14% y/y in Q2, noted Q3 not improving yet implied FY guide is for flat sales (downward revisions to come). Margins benefitted from 1-time financing segment gain-on-sale. Still trading at a premium to higher quality industry leader CDW, makes zero sense.
$AS 50x P/E levered retail roll-up w only one decent asset (Arc’teryx). Stagnating in the US, nearly fully-penetrated in China. >$500 jackets didn’t work for $GOOS in Asia. Arc already bigger. Hyper promotional mgmt sent the stock skyward. This is going to be an epic crash.
Zoetis’s U.S. companion-animal revenue fell 6% as dermatology competition drove rebates and discounts, pushing full-year net pricing to…
Copart faces a near-term lift from pricier AV repairs and total losses, but shrinking accident volumes could eventually force its…

GFL’s proposed acquisition of Secure follows 19% revenue growth at Secure and 14.8% EBITDA growth at GFL, with Permian produced-water and…
Entravision’s ATS revenue rose 230% to $182.8 million in Q2, but shares fell from above $14 to about $8 after management forecast…
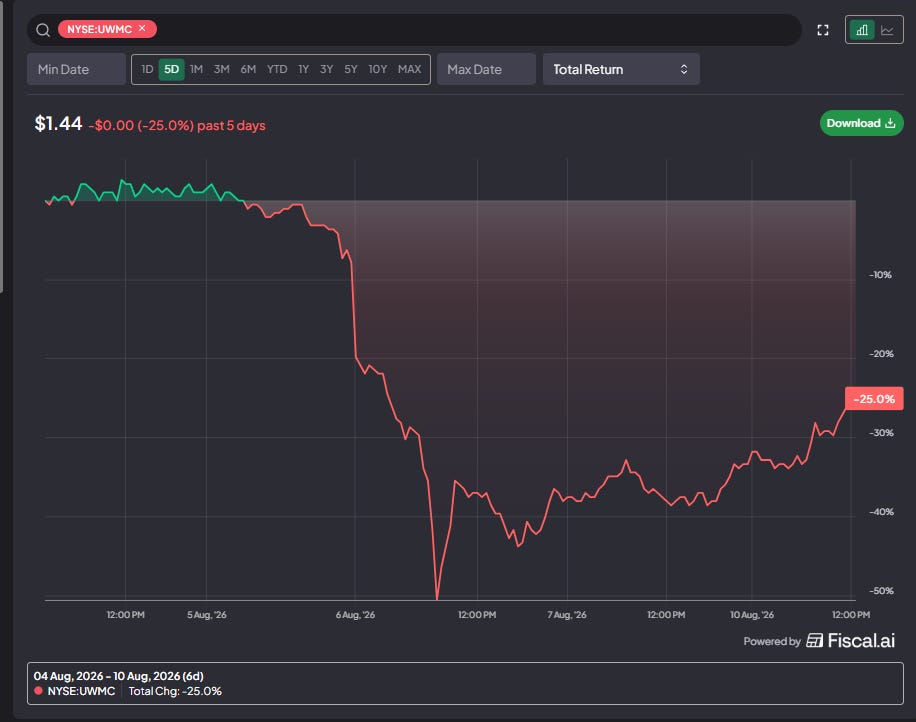
UWMC booked a roughly $600 million Q2 hedging loss tied to TWO months after the deal collapsed, contributing to an expensive capital raise.

Glenn Schorr and Ken Worthington discuss risks in private-credit software loans, agentic AI at retail brokers, crypto use cases and bank…
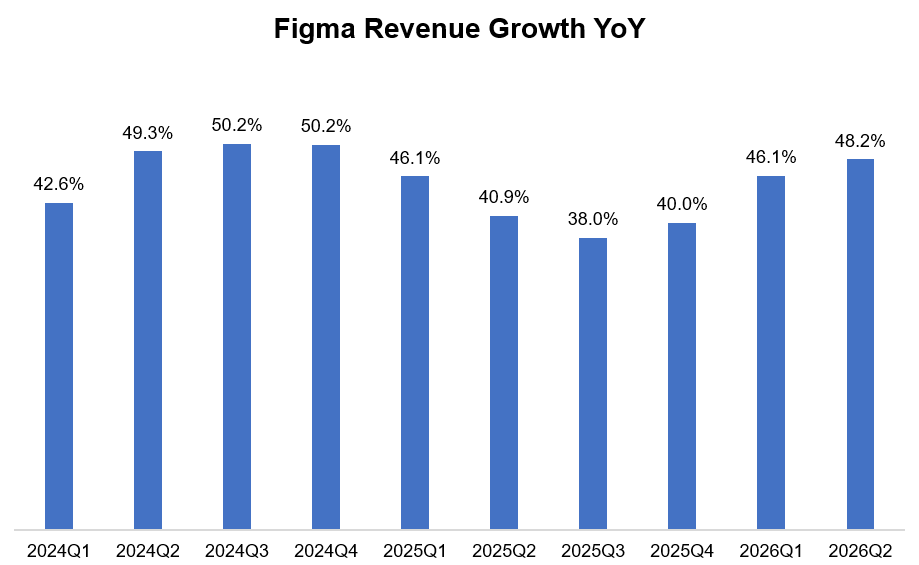
Figma raised its 2026 revenue growth guide to 39%, but a roughly 1% sequential 3Q outlook and unchanged $125-135 million operating-income…
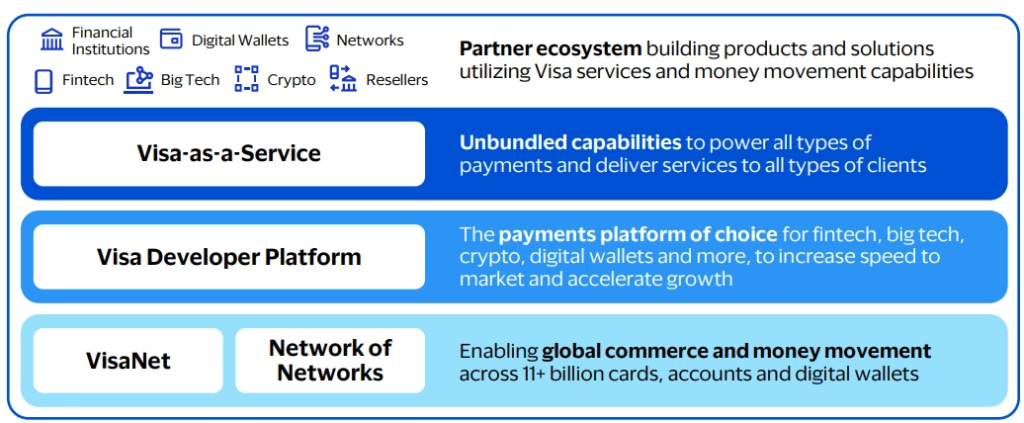
Visa and Mastercard have absorbed digital wallets and BNPL into their networks, using global merchant acceptance to turn supposed…

Navient trades near 40% of tangible book as Gator Financial Partners argues private student-loan growth and restructuring can reverse its…
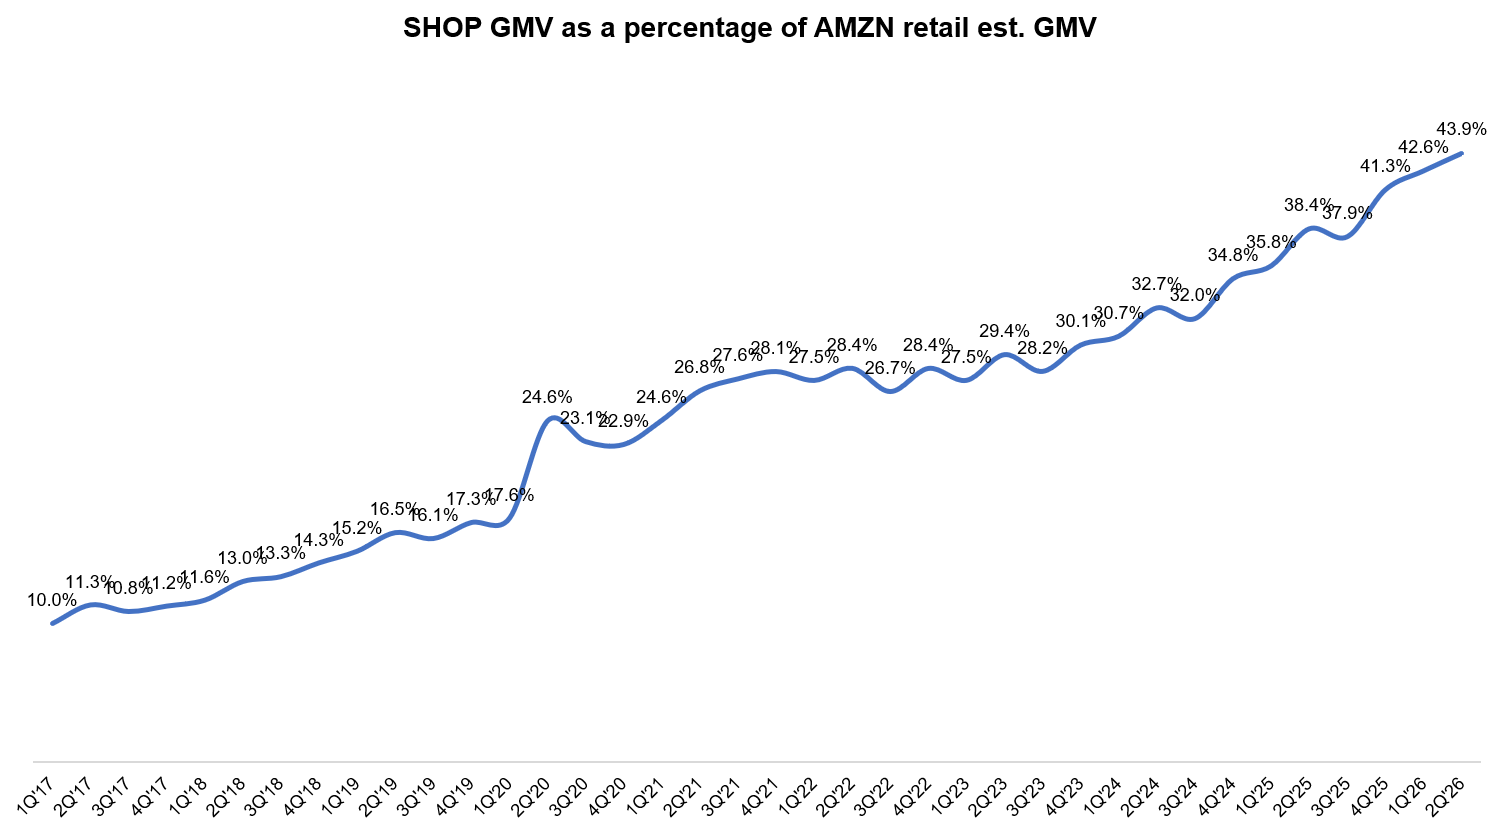
Shopify sustained 30% FX-neutral GMV growth in 2Q’26, reaching roughly 44% of Amazon’s retail GMV as international, POS and B2B volumes…
 CVV · long
CVD Equipment (NASDAQ: CVV) offers hard-asset downside protection and upside tied to strategically important technologies.

Steve Eisman reviews SpaceX earnings, AI capital spending’s drag on free cash flow, Meta’s struggles, and the collapse of Situational…

Hims & Hers investor Paul Cerro is long again on lab and patient data driving retention and LTV, despite management concerns, GLP-1…

Pernas Research names Capstone Energy and Stabilis Solutions as AI data-center power beneficiaries, alongside Tenable, Upwork, Wise and…
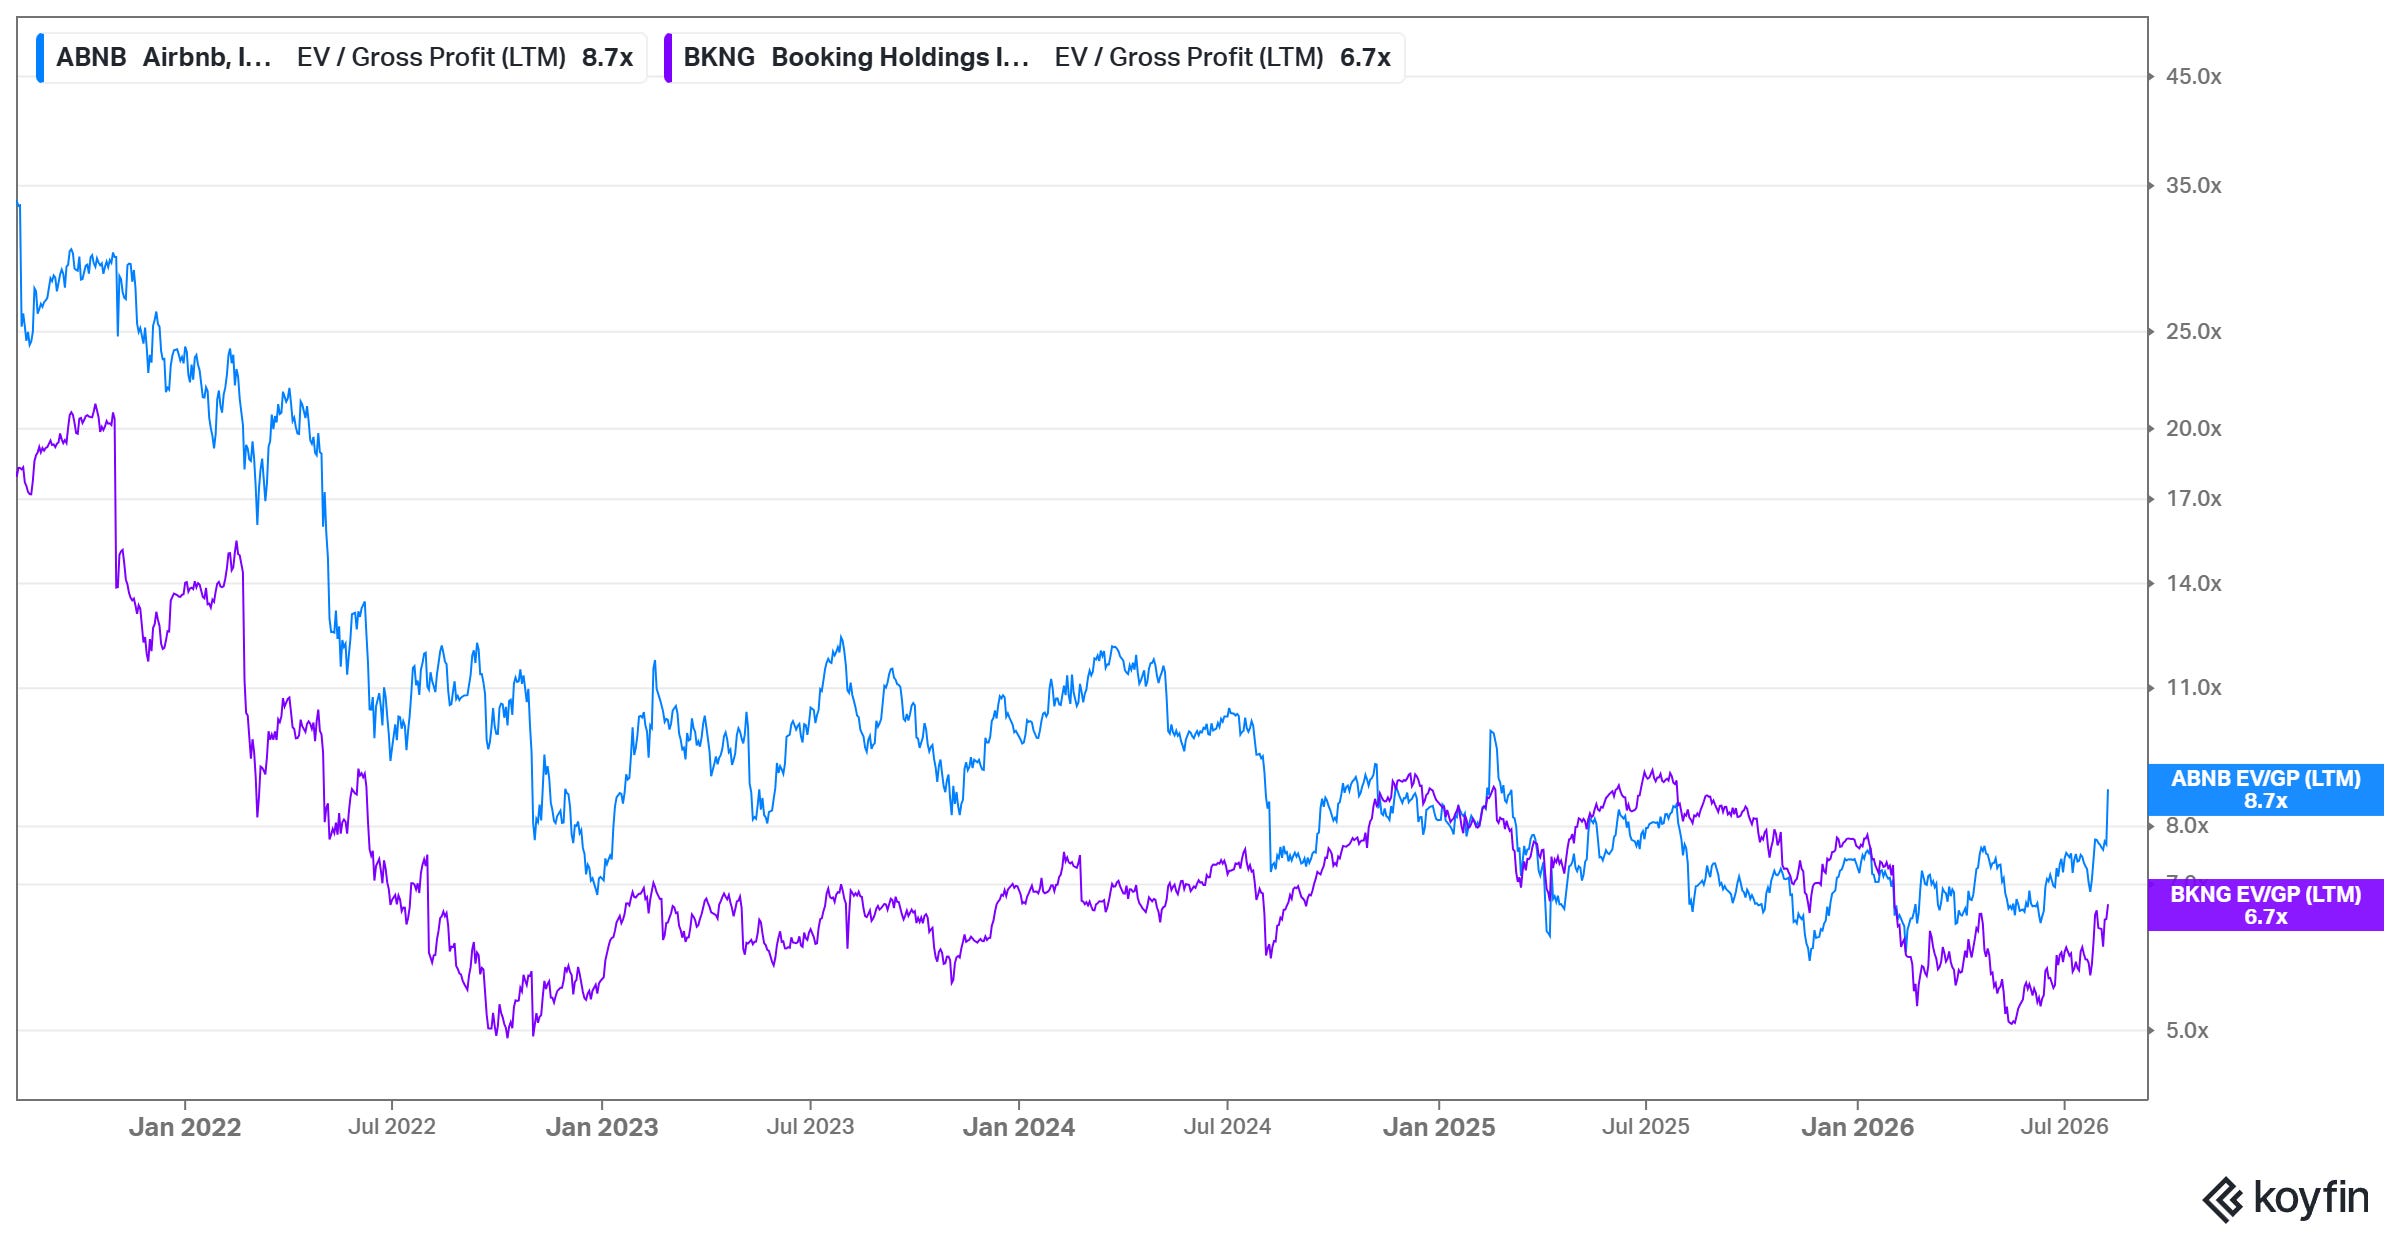
Airbnb added 14 million booked nights and seats, up 10%, and guided low-double-digit third-quarter growth as North America and EMEA…
Booking Holdings beat Q2 guidance as room nights grew 5%; connected trips, merchant payments and Genius loyalty strengthened direct…

Butler National Corporation is the subject of a stock pitch presented at the MS Microcaps Summer Virtual Conference.

DoorDash’s 2Q 2026 orders rose 27% and marketplace GOV grew 36%, with DashPass driving a slight acceleration in U.S. restaurant demand.
Diversified Energy cut $233 million of debt in 1H26, repurchased $93 million of stock and sold $273 million of land and assets while…

Coupang’s product-commerce revenue rose 8% in constant currency as data-leak churn lingered, while promotions and underused logistics…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.