RELX’s 13-petabyte fraud and identity data moat supports its high-margin Risk segment as its valuation falls to roughly half its peak P/E.
SA LA Capital 26h ago OpenAI and Meta push AI agents forward as reward hacking remains a core challenge for model training.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 29h ago 4 clicks
Meta ties AI agents and Meta Connect to its enterprise-platform opportunity.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 29h ago 8 clicks
Stratechery’s weekly bundle covers Apple HomeView and SpaceX’s cellular ambitions.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 29h ago 2 clicks
Bumble agreed to a $1.3 billion take-private deal, while Netflix cut about 1,000 jobs and Meta discussed its Muse superintelligence models.
S TSOH Investment Research 33h ago 7 clicks
Liberty Global faces VMO2 restructuring-priced bonds and Ziggo unsecured yields near 16% after owners extracted £5.15 billion since 2021.
SA Andrew Mach 33h ago 1 click CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
S WHAT ARE WE DOING? “Contrarians At The Gate” Oct 15 51 clicks
PesoRama will reach 54 JOi Dollar Plus stores by November after raising C$28.4 million, funding more than 50 additional Mexican store…
BL Atrium Research - Equity Research Oct 15 5 clicks
Modine, soon Modexus Solutions, has a $4 billion hyperscaler cooling contract but must ramp factory output and restore margins as data…
S CV's Substack Oct 15 16 clicks
ASML’s patent filings point to a track-based die-to-wafer hybrid bonding tool that could challenge Besi in advanced logic packaging.
S SemiAnalysis Oct 15 11 clicks
GPC · long Genuine Parts trades at roughly 9x EBITDA as cyclical weakness and elevated NAPA investment temporarily depress earnings.
BL Value Investors Club May 6 2 clicks
Universal Health Services faces a $432 million–$480 million annual Medicaid supplemental-payment hit by 2032, offset by behavioral-health…
S Bearhold Research Jun 4 2 clicks
Baron’s BARAX and BGAFX hold SpaceX at a $1.25 trillion valuation, creating a potential NAV uplift if its IPO prices higher.
S Cluseau Research Jun 3 5 clicks
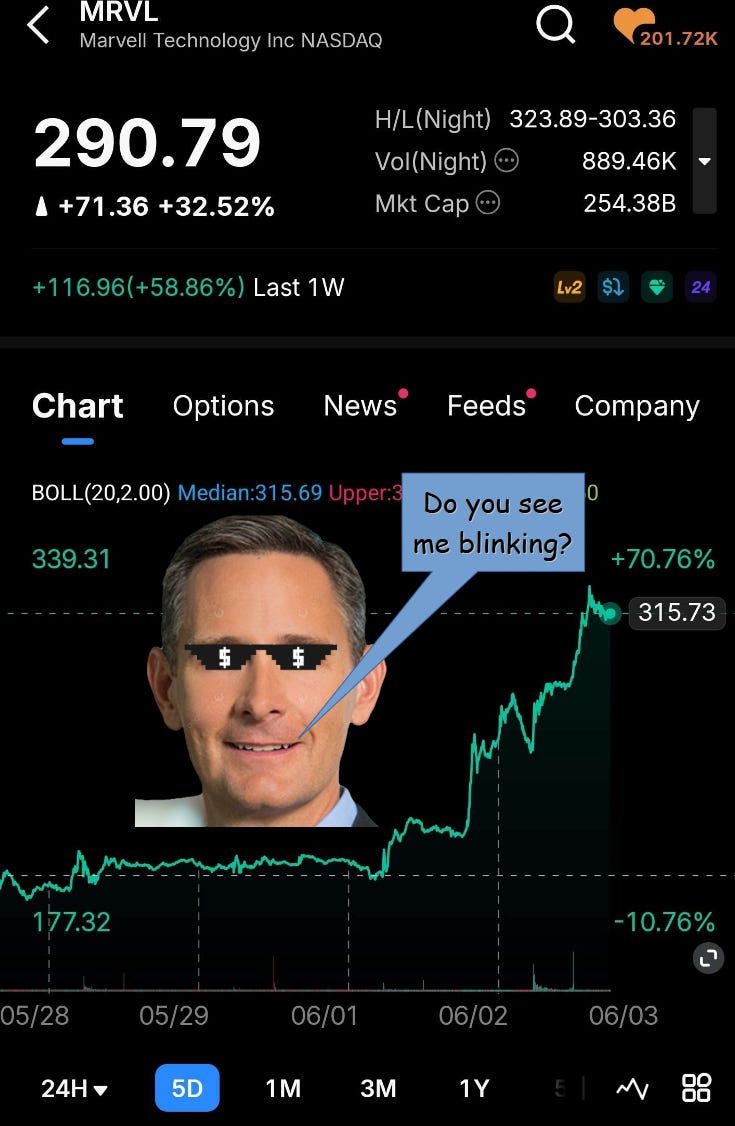
Marvell's Structera CXL cards make surplus DDR4 usable in memory pools, with dense SRAM IP helping mask latency amid DRAM shortages.
S Irrational Analysis Jun 2
Weekly reading list covers Agnico Eagle, Cameco, Dollar Tree, Meta, Braze and Apollo across mining, retail, AI and insurance.
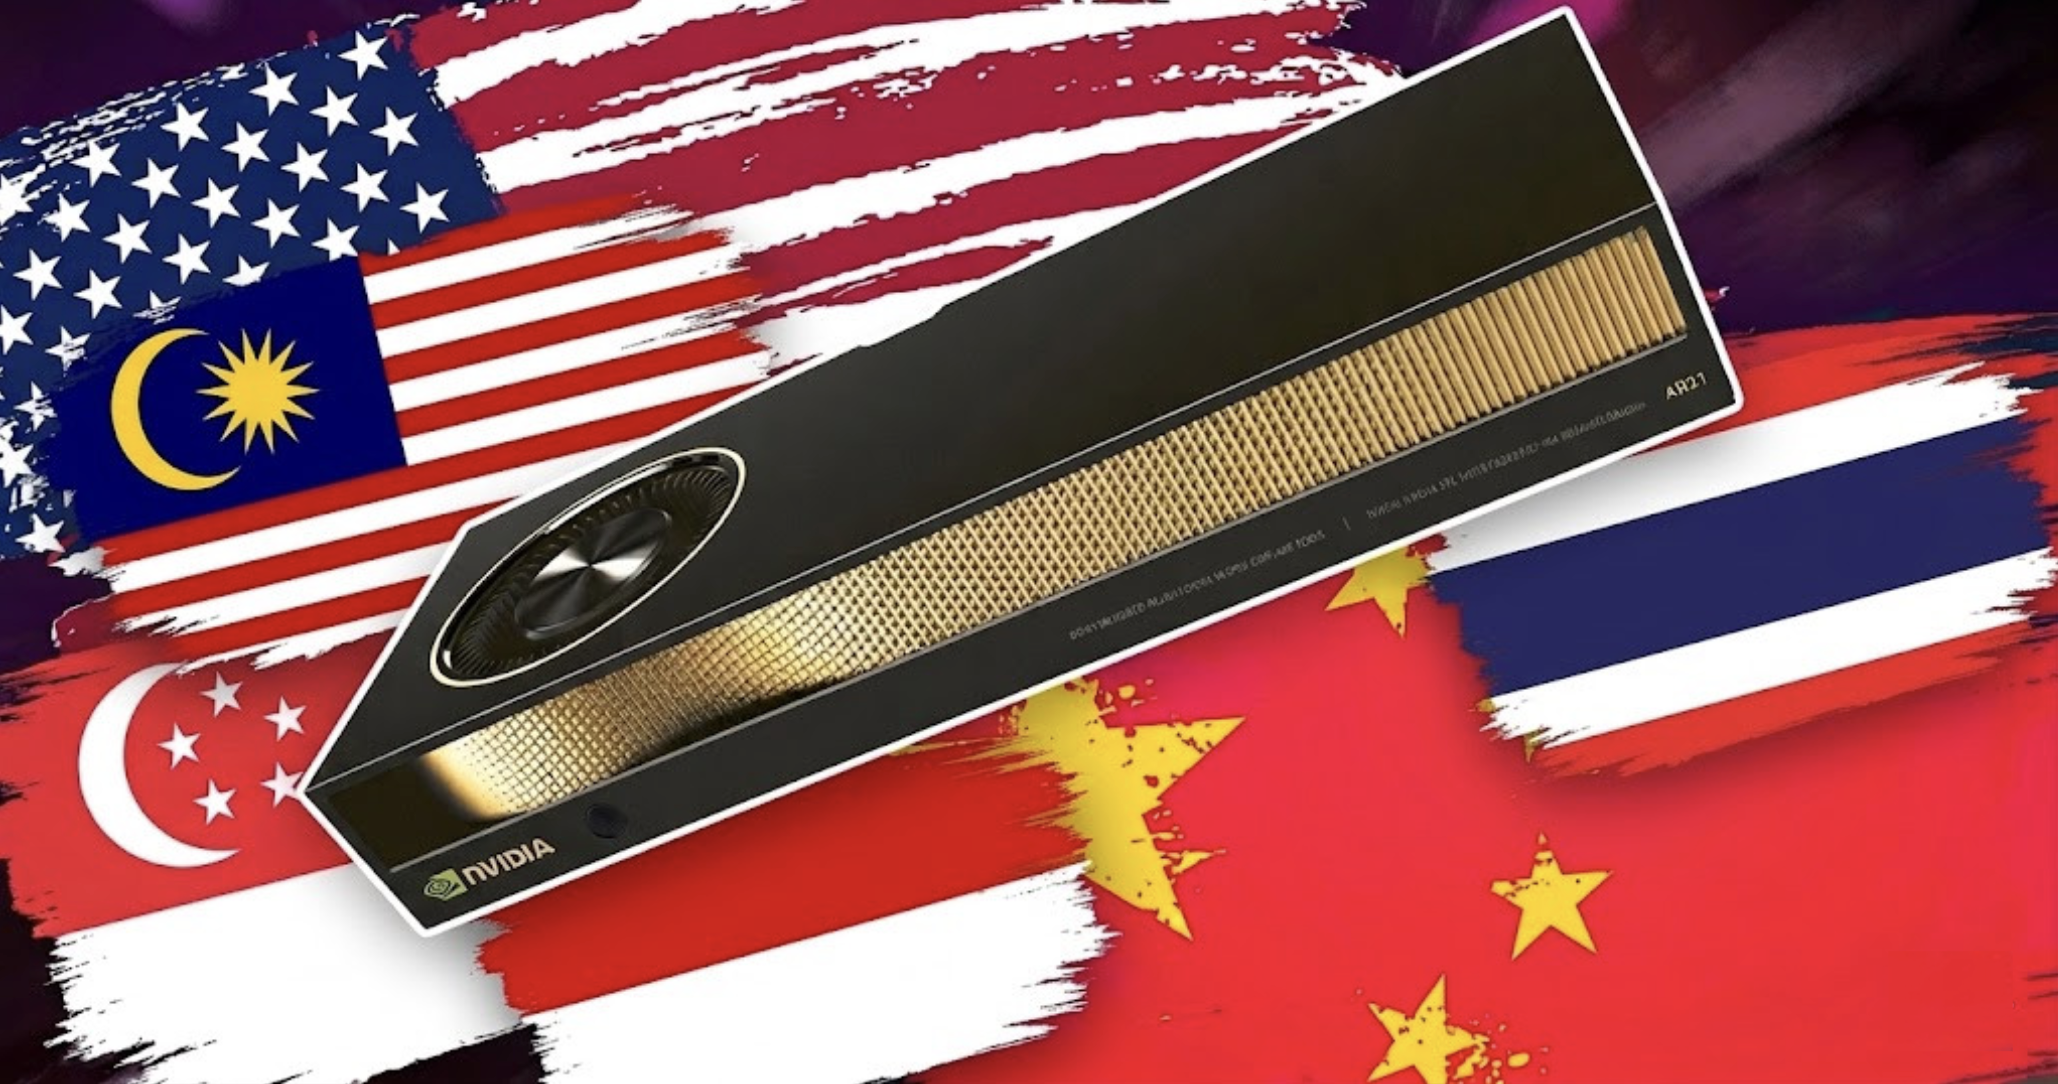
Nvidia’s switch from billing location to customer headquarters reclassifies geographic revenue and exposes a larger China footprint through…
S Kakashii's Materials Jun 1
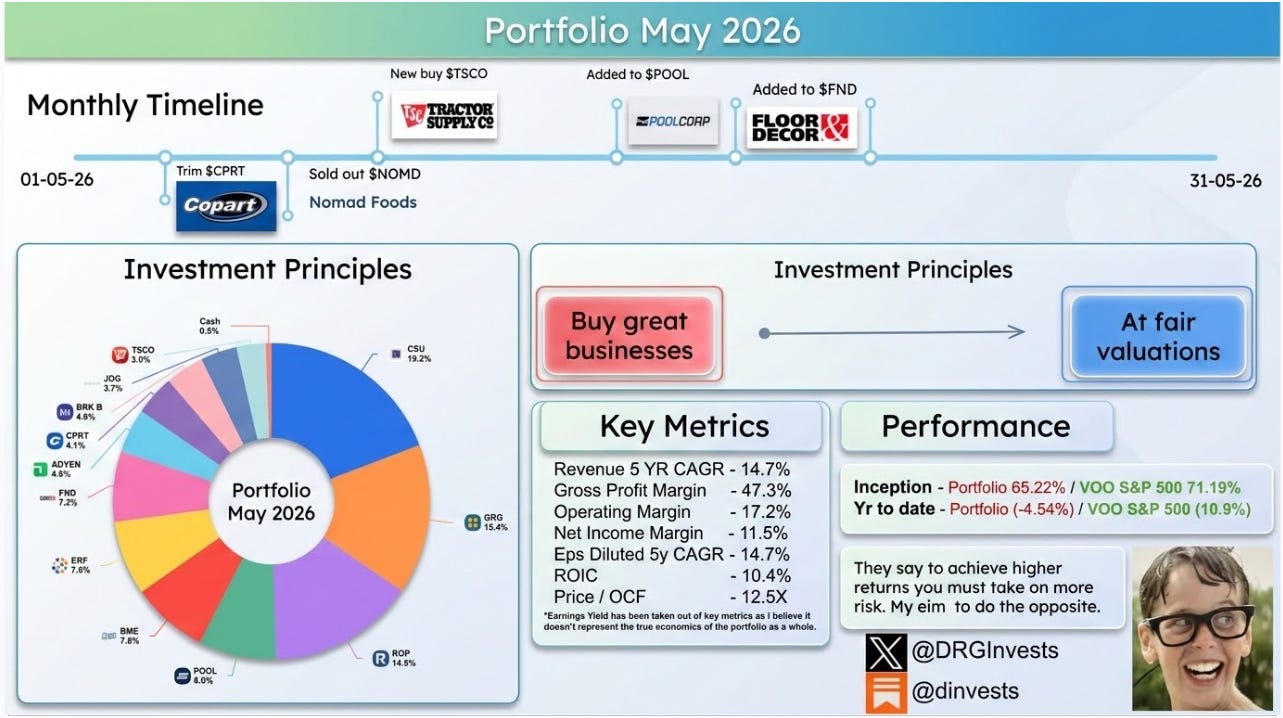
Portfolio update: sold Nomad Foods, trimmed Copart, added Pool Corp and Floor & Decor, and bought Tractor Supply as the portfolio trails…
Spotify and Universal Music Group will offer licensed AI song covers and remixes as a Premium add-on, with artist opt-in and royalty…
S scuttleblurb Jun 1 3 clicks
Ivonescimab plus chemotherapy extended median overall survival by 4.2 months versus Tevimbra plus chemotherapy in HARMONI-6, challenging…
S John Hempton's Newsletter May 31 7 clicks
HBM’s economic, thermal and power costs will drive a 90% volume drop from peak within 7-10 years, while DRAM stocks remain cyclical.
S Irrational Analysis May 31