RELX’s 13-petabyte fraud and identity data moat supports its high-margin Risk segment as its valuation falls to roughly half its peak P/E.
SA LA Capital 25h ago OpenAI and Meta push AI agents forward as reward hacking remains a core challenge for model training.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 28h ago 4 clicks
Meta ties AI agents and Meta Connect to its enterprise-platform opportunity.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 28h ago 8 clicks
Stratechery’s weekly bundle covers Apple HomeView and SpaceX’s cellular ambitions.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 28h ago 2 clicks
Bumble agreed to a $1.3 billion take-private deal, while Netflix cut about 1,000 jobs and Meta discussed its Muse superintelligence models.
S TSOH Investment Research 32h ago 7 clicks
Liberty Global faces VMO2 restructuring-priced bonds and Ziggo unsecured yields near 16% after owners extracted £5.15 billion since 2021.
SA Andrew Mach 33h ago 1 click CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
S WHAT ARE WE DOING? “Contrarians At The Gate” Oct 15 51 clicks
PesoRama will reach 54 JOi Dollar Plus stores by November after raising C$28.4 million, funding more than 50 additional Mexican store…
BL Atrium Research - Equity Research 47h ago 5 clicks
Modine, soon Modexus Solutions, has a $4 billion hyperscaler cooling contract but must ramp factory output and restore margins as data…
S CV's Substack Oct 15 16 clicks
ASML’s patent filings point to a track-based die-to-wafer hybrid bonding tool that could challenge Besi in advanced logic packaging.
S SemiAnalysis Oct 15 11 clicks
MIDD · long Middleby trades at about 11 times EBITDA, below its history and peers, as a sharper management focus is expected to address the commercial…
BL Value Investors Club May 6
Verisk’s exit from healthcare, financial-services and energy data restored a pure-play insurance analytics model, but D.E.
S scuttleblurb Jun 8 1 click
British American Tobacco targets more than GBP 50 billion of free cash flow by 2030 as Velo oral nicotine gains offset uneven vapor and…
Brown & Brown compounded revenue 14.4% annually since 1998 through more than 650 acquisitions, capped by its nearly $10 billion Accession…
S Eagle Point Capital Jun 6
MSGS, owner of the Knicks and Rangers, filed a Form 10 to explore a spinoff as comparable franchise sales support an $11 billion valuation.
CrowdStrike’s $318 million quarterly stock compensation and payroll taxes equaled 23% of revenue, diluting shareholders while non-GAAP…
S First Strike Research Jun 5
Ford’s 1956 IPO sold 10.2 million shares at $63 each after Goldman Sachs helped resolve the Ford Foundation’s voting-rights problem.
Lawrence Hamtil discusses the farmer mentality, software’s cycle and investing with irreplaceable capital.
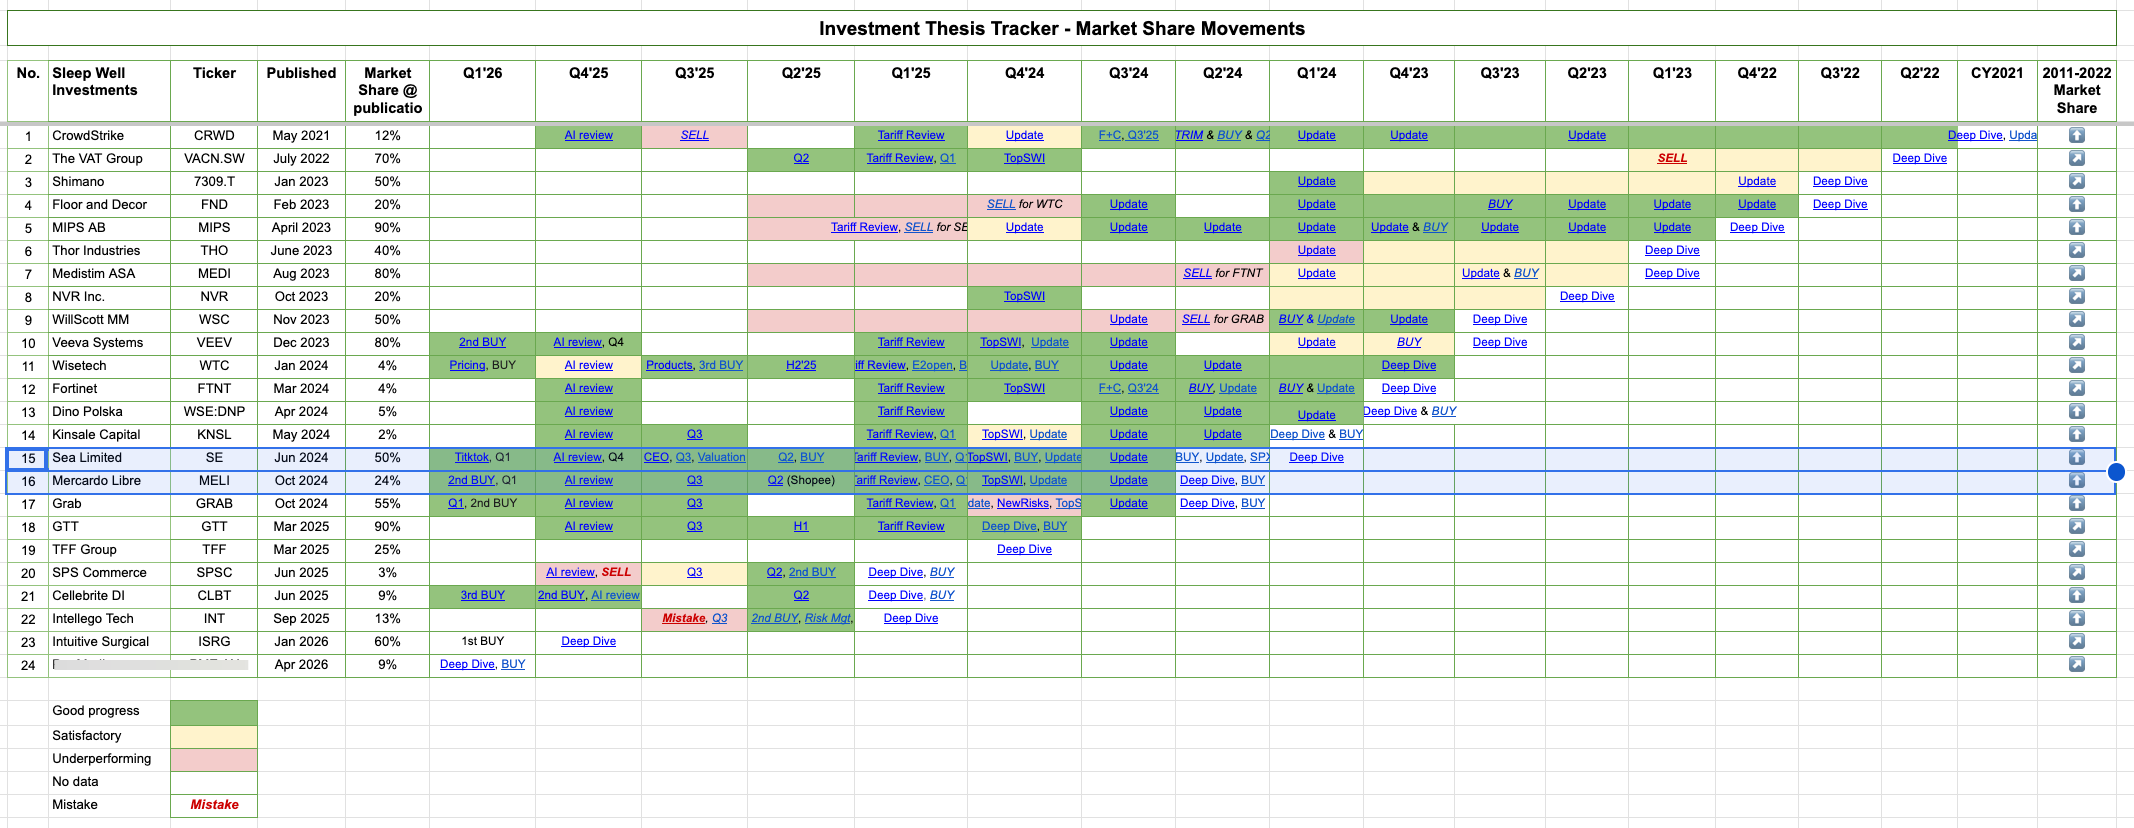
Sea and Mercado Libre defend Brazilian e-commerce share with logistics, cross-border trade, VIP programs and financial services, accepting…
S Sleep Well Investments Jun 5
Infineon’s power semiconductors stand to benefit from AI data centers shifting to 800VDC power delivery, though its sharp rerating to…
S Bristlemoon Capital Jun 4 1 click