Monte Investments Market Brief Vol. CXXXII
CoreWeave and neocloud peers face financing pressure, but sold-out GPU capacity and rising H100 and B200 rental rates support continued AI data-center investment.
CoreWeave and neocloud peers face financing pressure, but sold-out GPU capacity and rising H100 and B200 rental rates support continued AI data-center investment.
$GOOS continues to fly south new 52 week low -88% drawdown over 7 years. https://t.co/V8kTwqDJVy
👀 have been out of $WU for a short time. A sale would not surprise me, but probably makes more sense after it digests $IMXI. https://t.co/bno9ZATJ4I
$PSFE bizarre pivot. I'm long rn, and at first glance don't like the move. https://t.co/K2ZMLhQcro
@sidecarcap @GeoInvesting I should’ve also added $RWWI to this list
@sidecarcap Here’s a few non promotional microcaps we’ve covered at @GeoInvesting throughout the years: $SCIA $MOJO $SIF $ESP $PXHI $KEQU $MUEL $TBTC $RAVE $CRAWA(acquired last year).
Free Recaps of the best new stock ideas, delivered every morning.
Eagle Point Credit's NAV is down 25% YTD and shares nearly 50%, while its expense ratio climbed to 9.21% despite a 25% yield.
 Anthony Cataldo 3 clicks
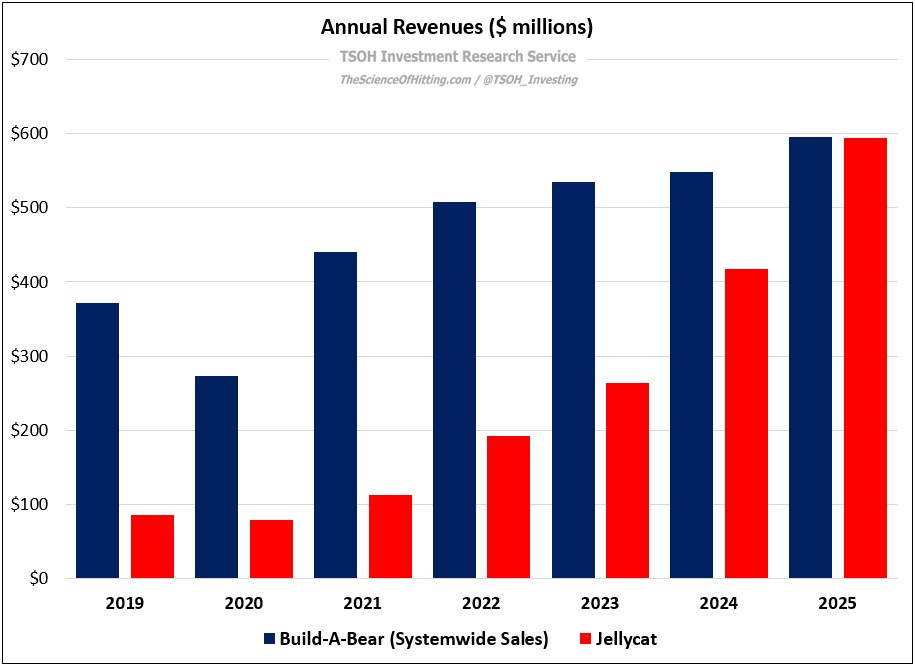
Build-A-Bear's push into prestuffed toys and broader retail distribution tests brand stretchability, but recent results warrant caution.
Lennar’s land-bank costs pressure homebuilding margins, while Flowers Foods weighs a Tastykake sale after falling branded-bread share,…
LendingTree derives roughly two-thirds of revenue from insurance and trades near 4 times expected adjusted earnings despite record revenue,…
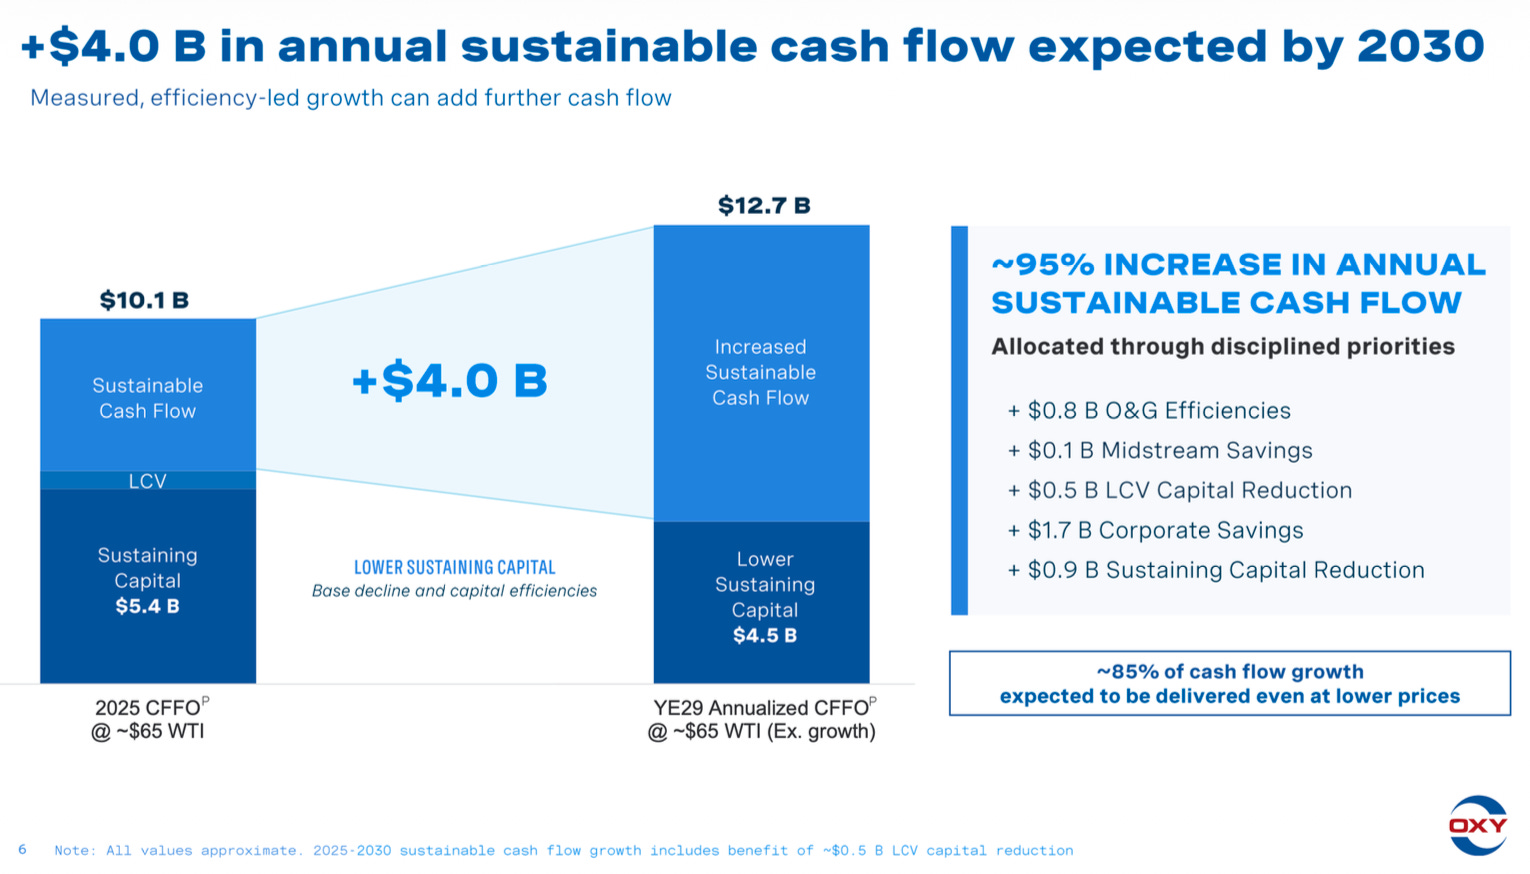
Occidental Petroleum’s debt should fall further after Q3 oil prices averaged $85 per barrel WTI and $91 Brent.
Hess Midstream, Iovance Biotherapeutics, Netlist and nine other lesser-covered stocks make this week’s Undercovered Dozen.
 The Undercovered Dozen 12 clicks
SiriusXM trades at 6.5 times free cash flow, a 15% yield, with high short interest and catalysts that could drive a short squeeze.
 Tim Travis 10 clicks
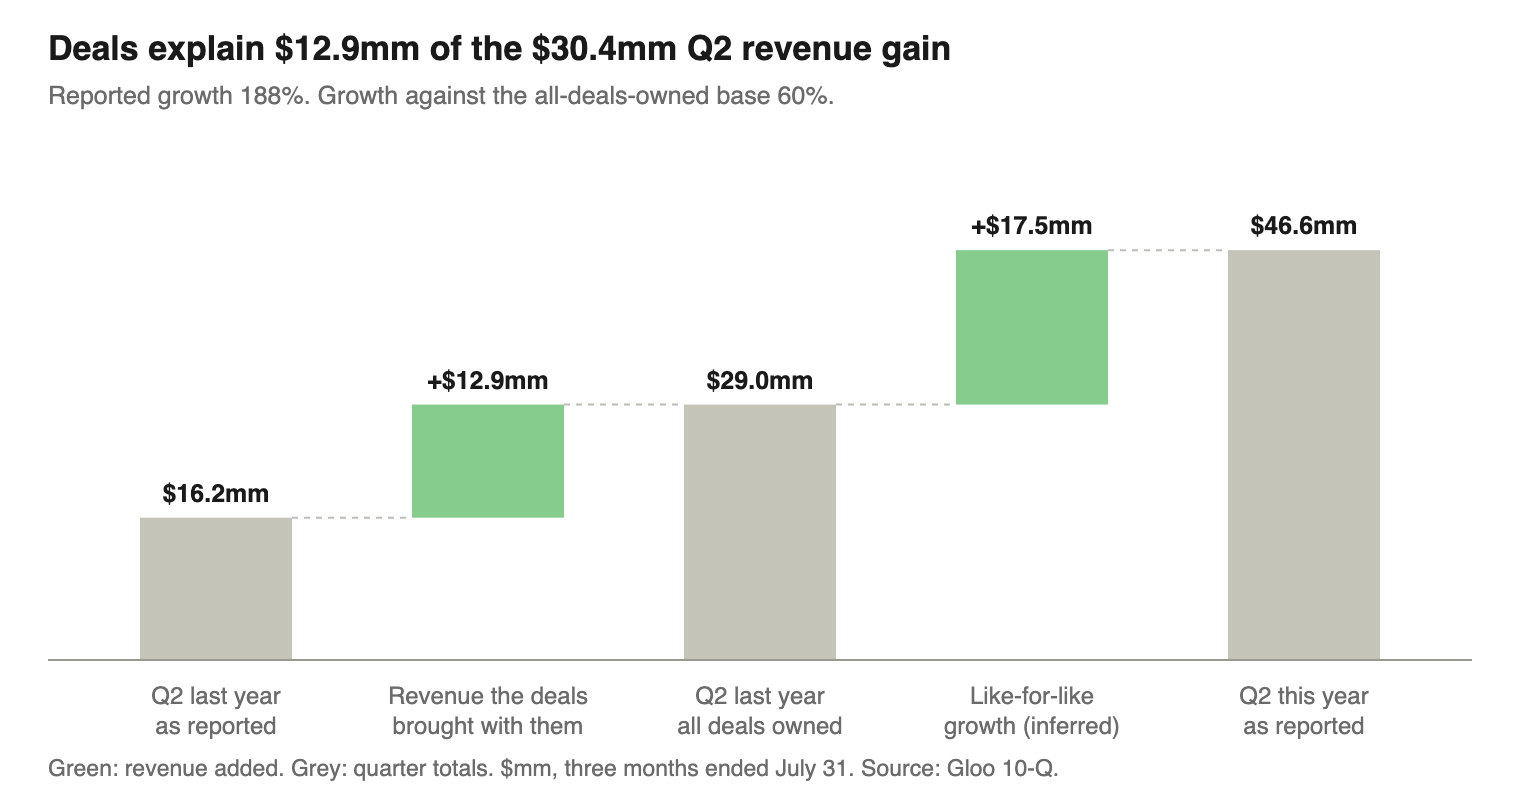
Gloo's $3.25 follow-on, going-concern warning and $28.0 million first-half cash burn frame the short case against its acquisition-driven…
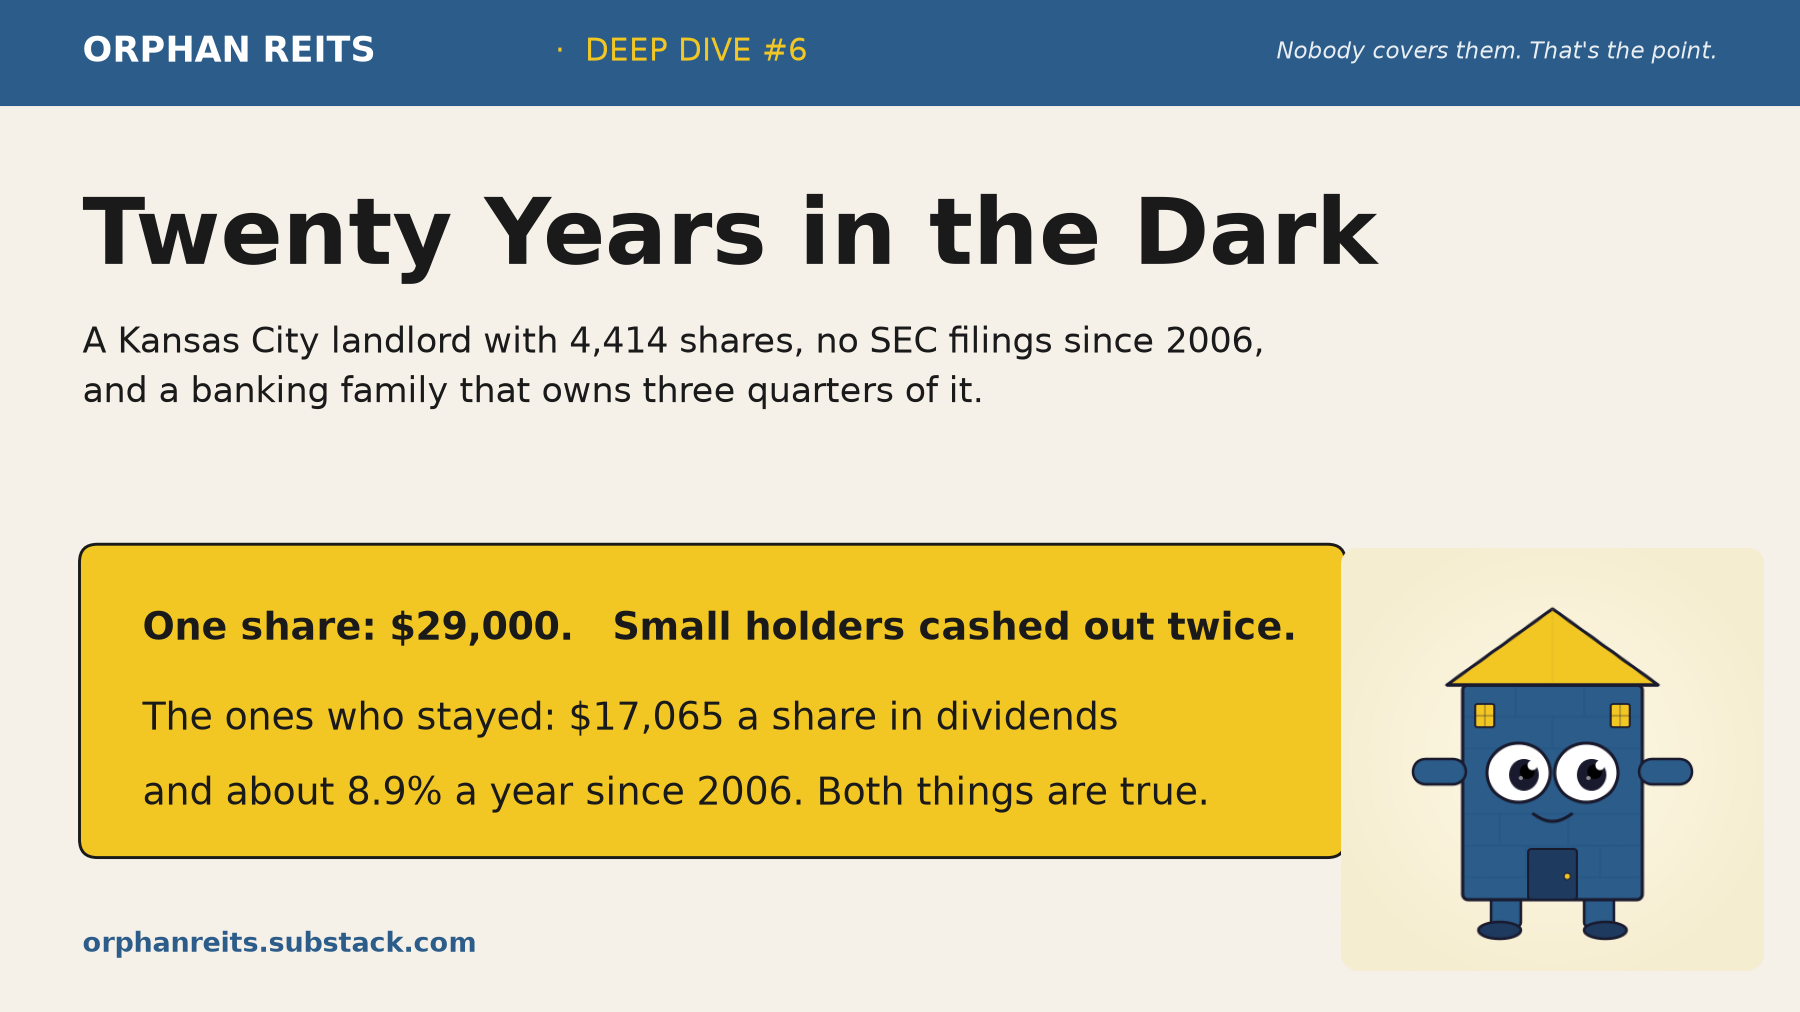
Tower Properties, $TPRP, went dark after a 2006 squeeze-out cut holders below 300, leaving a Kemper-controlled apartment and office…
 SKIN · long
SkinHealth Systems owns a dominant professional skincare consumables franchise but trades at roughly $115 million market cap and $255…
Oruka Therapeutics’ ORKA-001 posted PASI 90 and PASI 100 psoriasis responses at week 28; $1.1 billion of cash funds development through a…
 Equity Eagle 3 clicks
Bumble agreed to a $1.3 billion take-private deal, while Netflix cut about 1,000 jobs and Meta discussed its Muse superintelligence models.
Dorchester Minerals' 9.5% normalized yield and debt-free royalty model are offset by limited upside at $29.71, as extraordinary…
 Atlas Diary 3 clicks
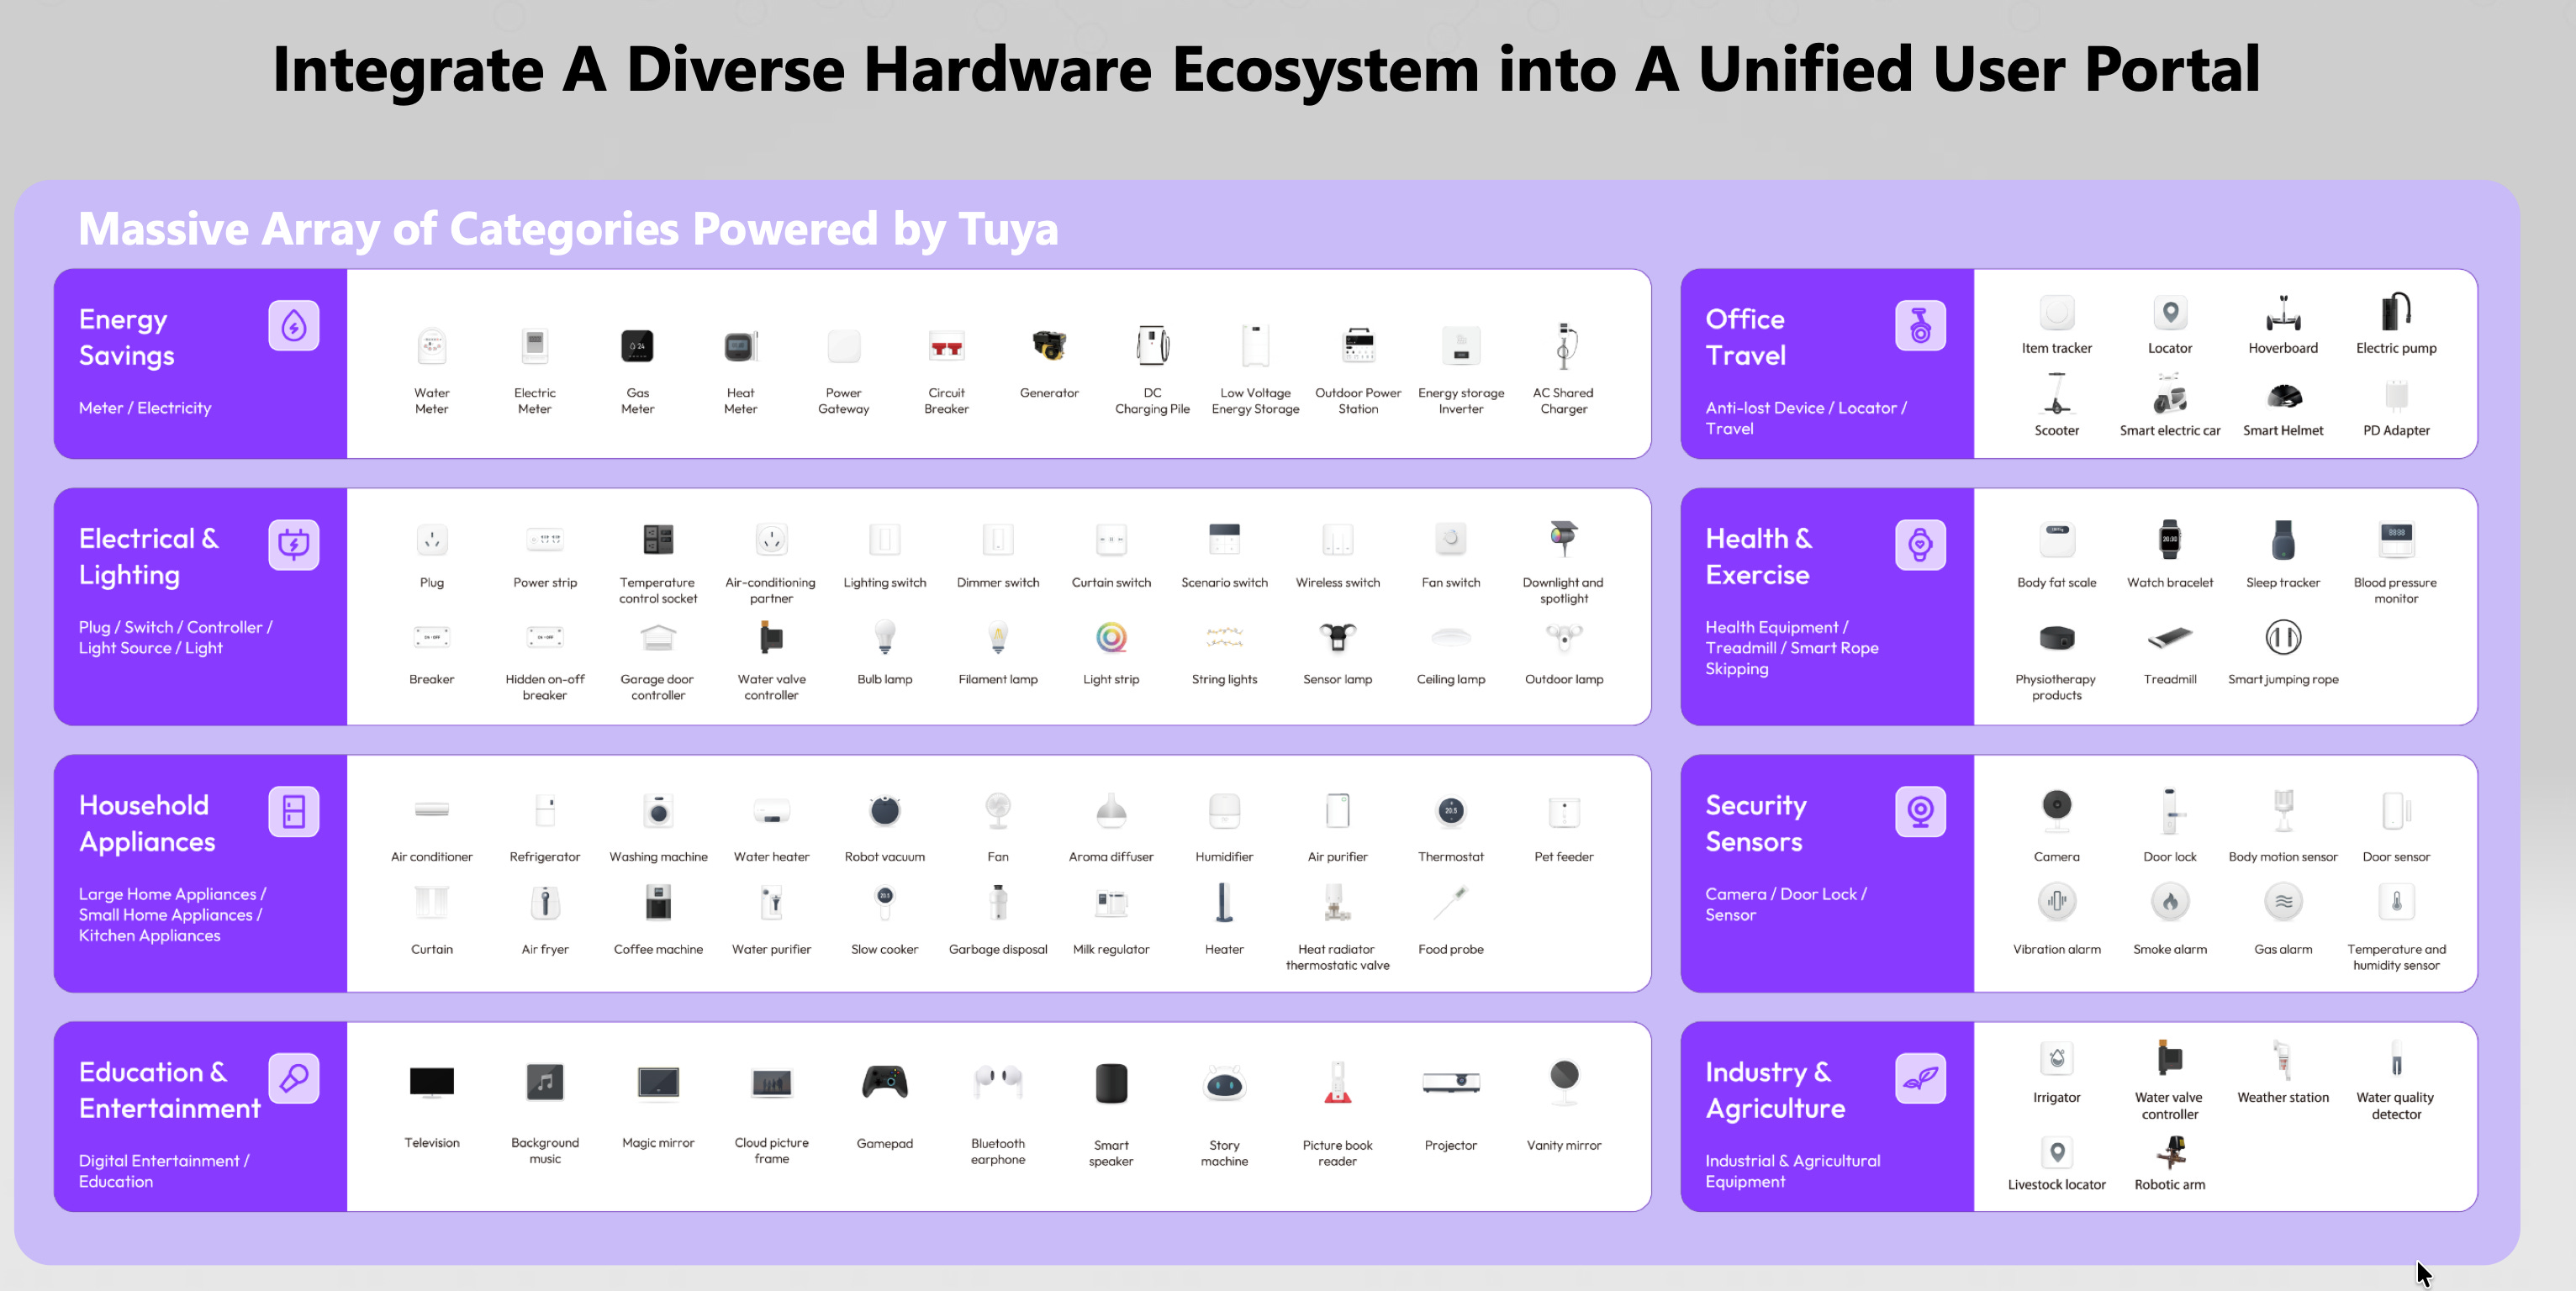
Tuya’s $976 million cash pile equals 94% of its $1.04 billion market cap as its smart-home platform returned to 16% revenue growth in Q2…
PesoRama will reach 54 JOi Dollar Plus stores by November after raising C$28.4 million, funding more than 50 additional Mexican store…
Modine, soon Modexus Solutions, has a $4 billion hyperscaler cooling contract but must ramp factory output and restore margins as data…
Dream Finders Homes’ controlling owner borrowed against DFH stock before the homebuilder agreed to finance an acquisition with costly…
Park Aerospace’s 11% Q2’27 sell-off overlooks sole-source PAC-3 rocket-motor materials and A320neo engine composites, with missile capacity…
UniQure's Huntington's gene therapy faces an FDA accelerated-approval decision around November 1 after three-year data met both agency…
 Bhavneesh Sharma 16 clicks
Have a source we’re missing? Send your pick
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor The Undercovered Dozen Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.
Anything we’re missing?
Send us a pick