Why I sold OB pick for 26 SVM
Silvercorp’s falling Ying grades, prolonged GC suspension, El Domo execution risk and Chaarat funding needs weaken its valuation despite higher silver prices.
Silvercorp’s falling Ying grades, prolonged GC suspension, El Domo execution risk and Chaarat funding needs weaken its valuation despite higher silver prices.
Loop company's bid to buy Arizona bank $BNCC would spike predatory lending, consumer advocacy groups argue - Chicago Sun-Times https://t.co/NQ4aIh3LzV
@leevalueroach $BWEL
Newest out. Scandinavian Tobacco Group: Shear "Q2'26 note." $STG $PM $BTI $IMBBY $MO $HAYPP https://t.co/frArnxjq8I
Free Recaps of the best new stock ideas, delivered every morning.
CareCloud may attract a private-equity buyer after its Q3 call, with acquiring enough shares the main obstacle to a take-private deal.
HEICO sells FAA-approved aircraft replacement parts at 30% to 50% discounts to OEMs, gaining customers as restrictive aftermarket contracts…
Northrop Grumman posted 7% Q3 sales growth to $11.1 billion, lifted profit guidance and reached a record $109.6 billion backlog, led by…
AGI Inc trades at 5.6x earnings after a 35% post-IPO decline, despite roughly 30% ROE and resilient INSS payroll-loan growth.
 Multiplo Invest 5 clicks
CoreWeave and neocloud peers face financing pressure, but sold-out GPU capacity and rising H100 and B200 rental rates support continued AI…
Urban Outfitters' Nuuly subscription service grew sales 28.6% and reached a 10.1% operating margin, with management targeting $700 million…
 IWA Research 2 clicks
Group 1 Automotive’s $1.25 billion Atlanta borrowing lifts net corporate debt to about $4.4 billion; a 2009-style downturn leaves it near…
LCNB’s Q3 2026 net interest income rose 8.6% year over year as the bank beat revenue and EPS estimates, while trading at a 27% discount to…
 Sorrento Research
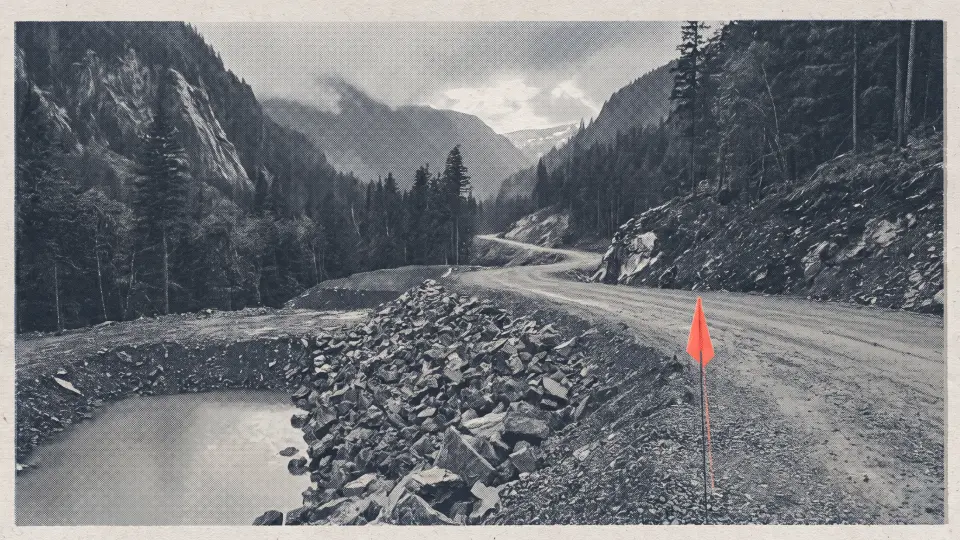
Copper Fox’s C$9.1 million Schaft Creek program advances metallurgical, tailings, water and road studies toward a pre-feasibility study,…
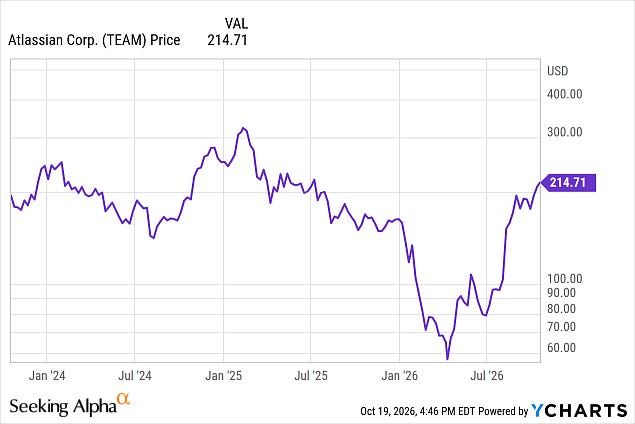
Atlassian is sold after a 130% gain, while iShares MSCI Indonesia ETF is added following the market plunge; the update also assesses the…
 CHGG · long
Chegg is framed as a binary long with 500% upside against 20% downside.

Northrop Grumman reports Q3 2026 on October 20 with a $105 billion backlog, up 16% year over year, and trades at 23 times trailing…
Nebius reported Q2 revenue growth of 454% and $3 billion ARR, targeting 5GW of AI capacity by 2030 after a Palantir partnership.
 Salix Research 12 clicks
AppLovin rebuilt its ad model with AXON 2.0, lifting LTM revenue to about $7 billion and margins to 77% as Unity competition threatens ad…
Lanxess can force Advent to buy at least half its Envalior stake in April 2028, potentially raising about €745 million to reduce net debt.
Eagle Point Credit's NAV is down 25% YTD and shares nearly 50%, while its expense ratio climbed to 9.21% despite a 25% yield.
 Anthony Cataldo 5 clicks
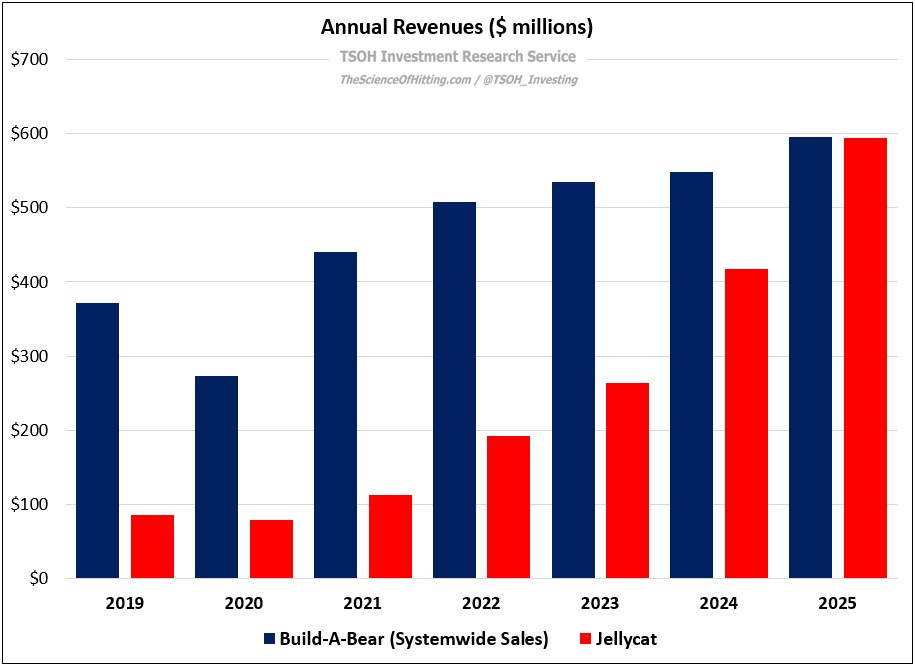
Build-A-Bear's push into prestuffed toys and broader retail distribution tests brand stretchability, but recent results warrant caution.
Lennar’s land-bank costs pressure homebuilding margins, while Flowers Foods weighs a Tastykake sale after falling branded-bread share,…
LendingTree derives roughly two-thirds of revenue from insurance and trades near 4 times expected adjusted earnings despite record revenue,…
 Michael Fitzsimmons 4 clicks
Have a source we’re missing? Send your pick
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.
Anything we’re missing?
Send us a pick