Why CENX Is Best Positioned for the U.S. Aluminum Comeback
Century Aluminum (CENX) could benefit from U.S. tariffs, Midwest aluminum premiums and constrained global supply, with the stock trading near 3x projected FY2027 free cash flow.
Century Aluminum (CENX) could benefit from U.S. tariffs, Midwest aluminum premiums and constrained global supply, with the stock trading near 3x projected FY2027 free cash flow.
Realty Income trades near $58, with 2026 AFFO guidance of $4.45 to $4.46 per share and a 5.5% dividend yield supported by a low-70% payout…
 Treading Softly 3 clicks
S&P Global’s valuation swung from 7x earnings in 2009 to 50x in 2024 as ratings, indices and proprietary data expanded through acquisitions…
Amneal Pharmaceuticals posted its fourth straight earnings beat, with Q3 revenue up 10%, raised FY26 guidance and an expanding biosimilar…
 Albert Anthony 4 clicks
Monte Investments rotated Nvidia into Alphabet before earnings and reviews Knife River’s margin squeeze, AMD’s World Labs acquisition, and…
Elanco’s earnings inflection and prospective dividend support targeted low-double-digit EPS growth despite Zoetis discounting.
Bruce Flatt’s Brookfield built 19 percent annual returns by buying distressed real assets below replacement cost with long-term…
Entravision’s AdTech revenue rose 133% and EBIT 261% in Q3 as management weighs TV-station sales before its TelevisaUnivision agreement…
LyondellBasell’s target falls to $75 from $80 as lower 2028 earnings, higher ethane costs and Chinese overcapacity outweigh its stronger…
 Investor Overview 4 clicks

Steve Eisman, Dan Ives and Gil Luria assess how the midterms could reshape AI data-center spending, Google search growth, and competition…
FactSet CEO Sanoke Viswanathan discusses using the firm’s client relationships and data platform to deploy AI across finance.
 TOST · long
Toast is pitched as a long opportunity on its growth runway and margin expansion after recent software and payments underperformance.
Reddit's search-traffic selloff overlooks that logged-in app users generate more than 80% of monetization, supporting a $130 one-year…
 M&M Capital 3 clicks

Accenture reported 6.5% FY26 revenue growth and $11.6 billion in free cash flow, while fixed-price contracts above 65% of bookings retain…
Adobe (ADBE) became a full position at about $246, backed by buybacks and confidence it can adapt to AI competition.
Sonida Senior Living owns 153 senior housing properties after a March 2026 merger doubled its scale, with aging-driven demand and tight…
Ondas reported $167.5 million in Q3 revenue but spent $562 million of cash, halved gross margin and fell below its $6 stop level.
Offshore Radar maps 160-plus listed offshore rigs, contracts, day rates and uncontracted capacity through 2029.
Travere Therapeutics' FILSPARI has two FDA approvals and is driving revenue growth, while TVTX shares have nearly tripled since August 2025.
 Out of Ignorance 3 clicks
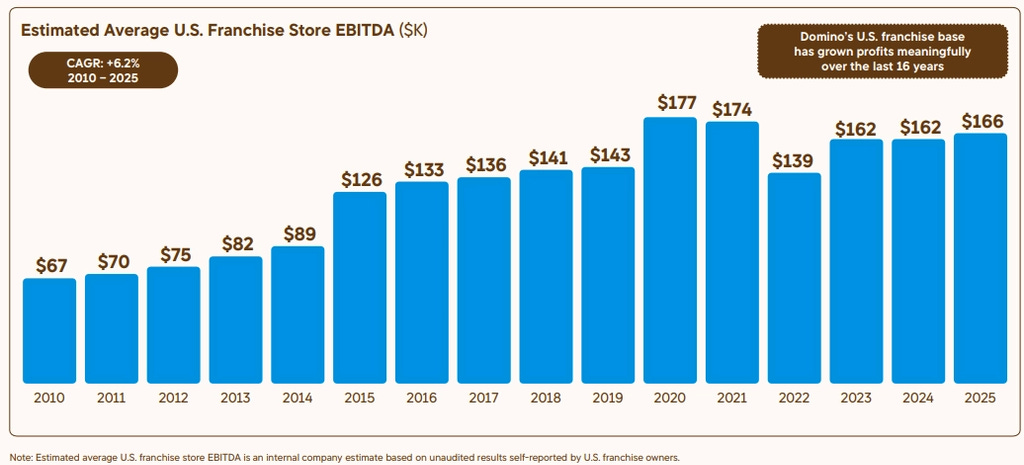
Domino’s built PULSE, online ordering and Pizza Tracker into a delivery machine, driving 10% annual global retail sales growth after its…
Nubank and MercadoLibre update target prices as Brazil’s 9% real rates, weaker currency and tighter credit favor their cost advantages and…
Every publication on this site, hand-picked.
 Adam Schadt Albert Anthony
 Alexander Grover
 Andres Veurink
 APAC Research
 Arizona Equity Research
 Atlas Diary
 Bay Area Ideas
 Benjamin C. Barry
 Bernard Zambonin
 Blake Winiecki
 Capital Connoisseur
 Chetan Woodun
 Crimson And Gold Research
 Cypriot Invests
 Dane Bowler
 Daniel Bell
 Daniel Jones
 Daniel Schönberger
 Danil Sereda
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Edmund Ingham
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Gil Rotstein
 Given Mahlangu
 Gytis Zizys
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Kevin Avroutskii
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Louis Gerard M&M Capital
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Multiplo Invest
 Myriam Alvarez
 Nicolas Bolsinger
 Number Cruncher
 Oakoff Investments
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Sanjay Swamy
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 Terry Chrisomalis
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Yiannis Zourmpanos
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Garrett Arms
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 Japan Deep Value
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kingdom Capital
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.