Trading Post November 16, 2026
Adobe (ADBE) became a full position at about $246, backed by buybacks and confidence it can adapt to AI competition.
Adobe (ADBE) became a full position at about $246, backed by buybacks and confidence it can adapt to AI competition.

$CDNA - About to breakdown.

@TLandstreet @orrdavid At $LINC they are
Offshore Radar maps 160-plus listed offshore rigs, contracts, day rates and uncontracted capacity through 2029.
Travere Therapeutics' FILSPARI has two FDA approvals and is driving revenue growth, while TVTX shares have nearly tripled since August 2025.
 Out of Ignorance 1 click
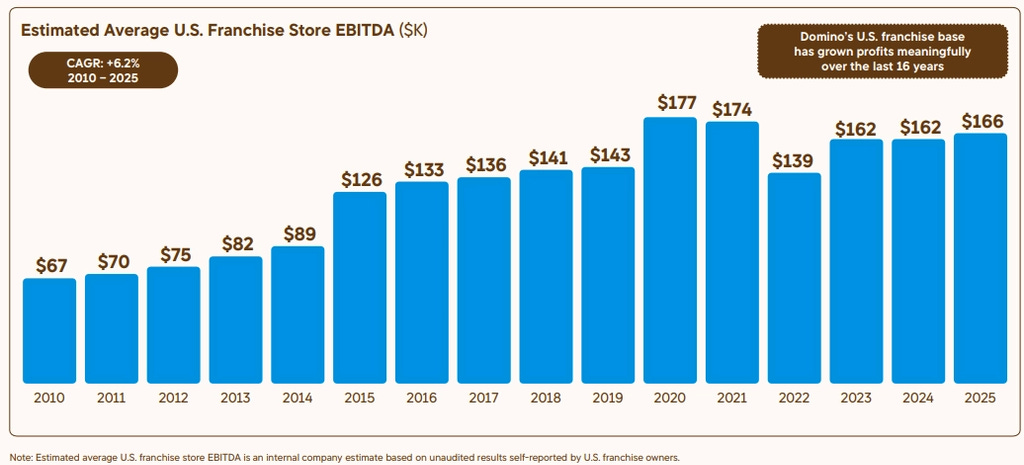
Domino’s built PULSE, online ordering and Pizza Tracker into a delivery machine, driving 10% annual global retail sales growth after its…
Nubank and MercadoLibre update target prices as Brazil’s 9% real rates, weaker currency and tighter credit favor their cost advantages and…
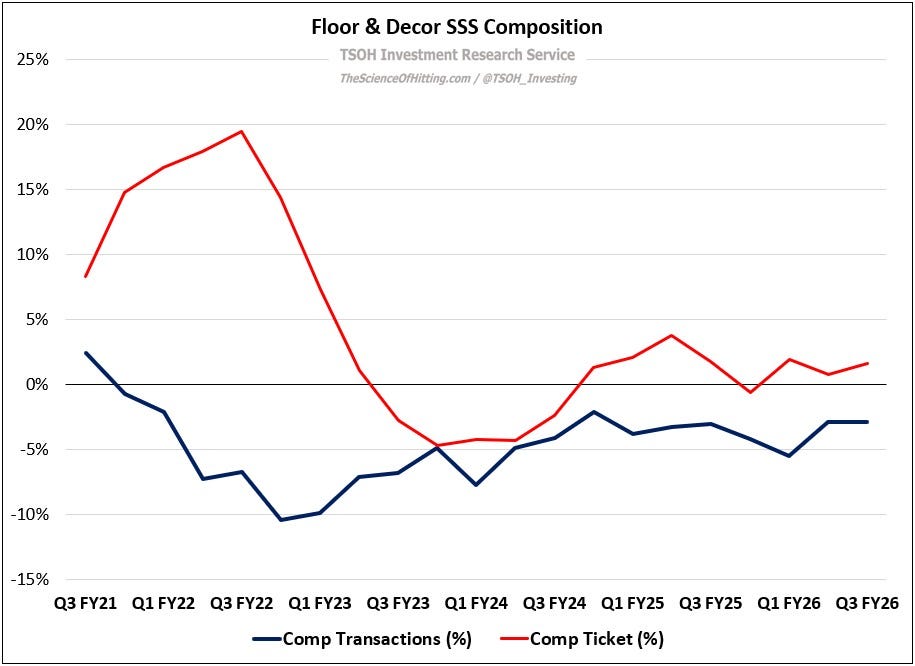
Floor & Decor has logged 20 straight quarters of comp transaction declines, with Q3 quarter-to-date same-store sales down about 3.8% as…
HCI Group grew Q3 revenue 13% and net income 27%, with $2 billion of invested assets driving investment income.
 Given Mahlangu 1 click
TPG trades 20% below its average distributable-earnings multiple despite the fastest fee-related earnings growth among alternative…
CDW CEO Chris Leahy says AI spending is entering a second wave focused on putting technology to work in everyday consumption.
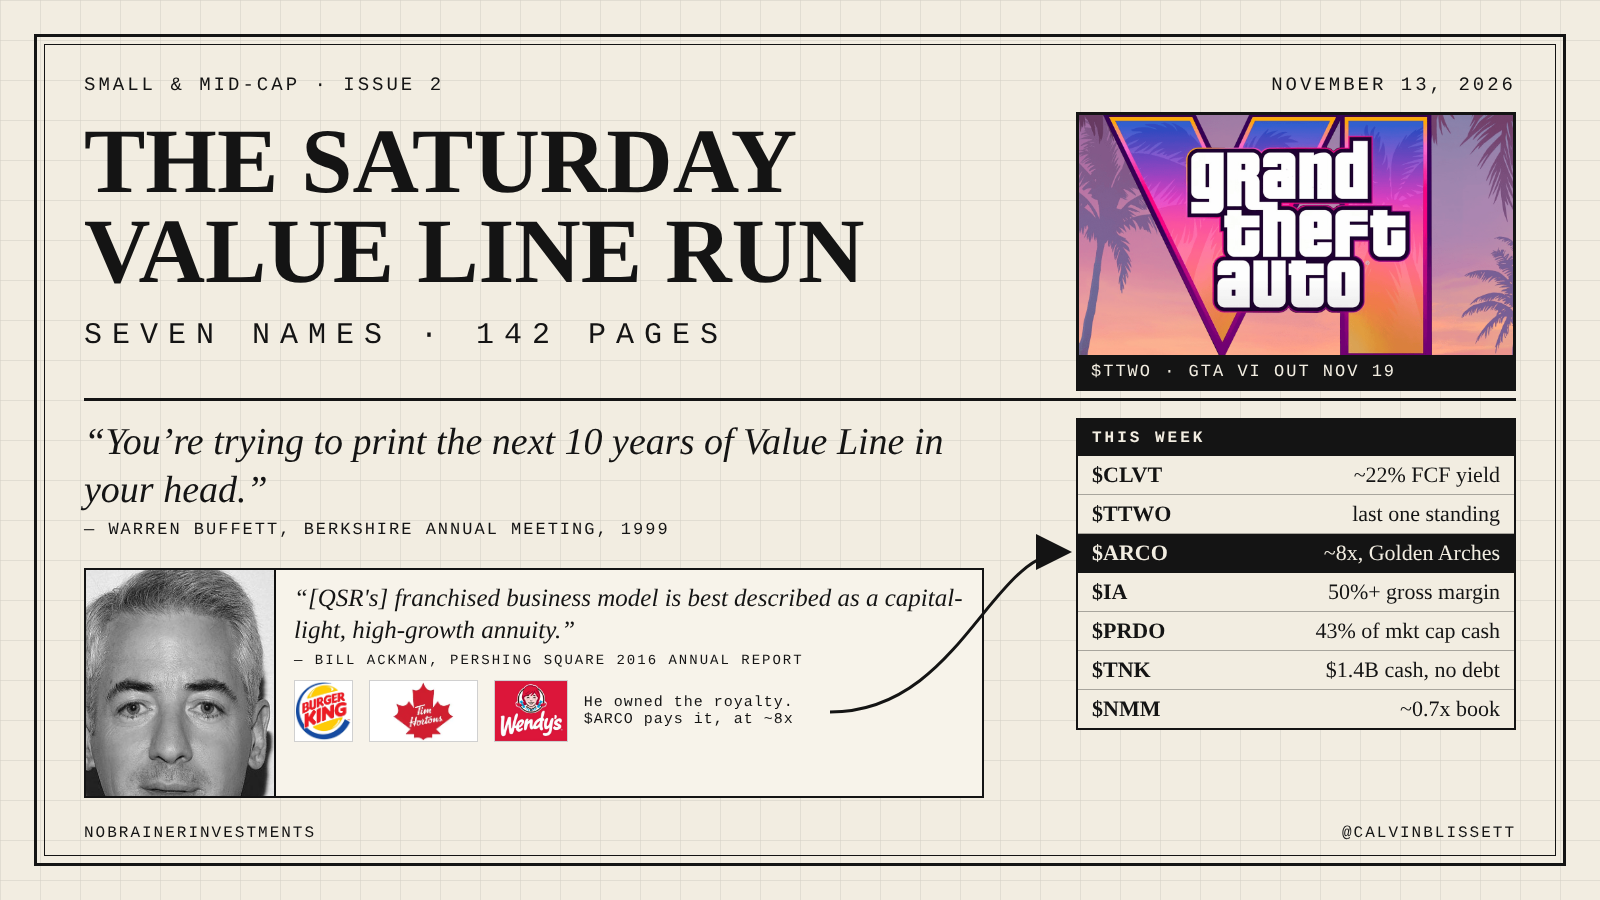
Clarivate, Take-Two and Arcos Dorados lead a seven-stock Value Line screen focused on debt paydown, GTA VI economics and Latin American…
Hyster-Yale remains under pressure as Americas revenue fell to $608.6 million from $732.7 million, while $100 million of planned cost…
 Daniel Jones
 GTLB · long
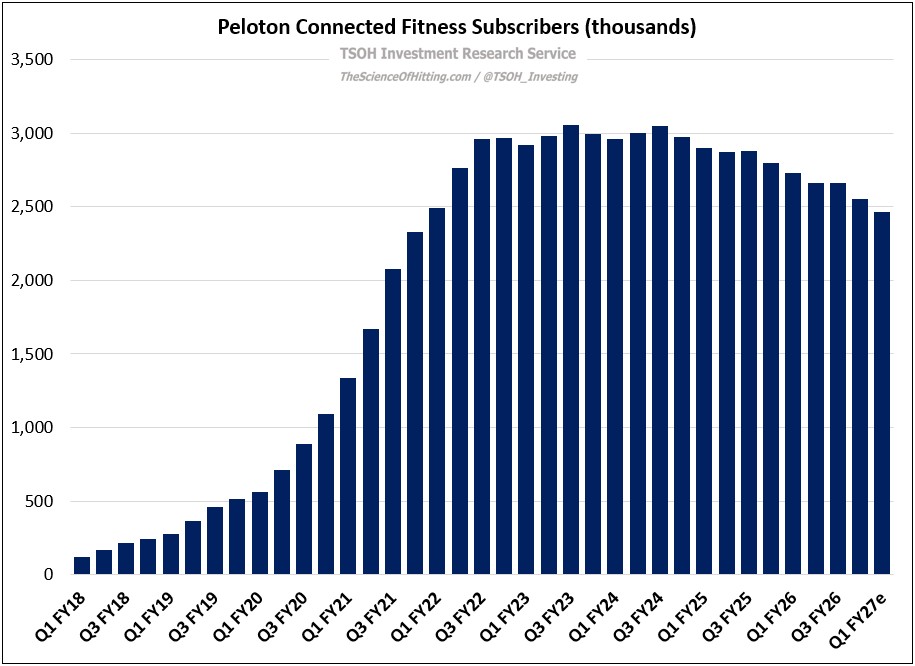
Peloton’s improved balance sheet has not stopped weak subscription trends or sharp volatility, prompting purchases near $3.70, a later…

Navient trades near 40% of tangible book as Gator Financial Partners argues private student-loan growth and restructuring can reverse its…
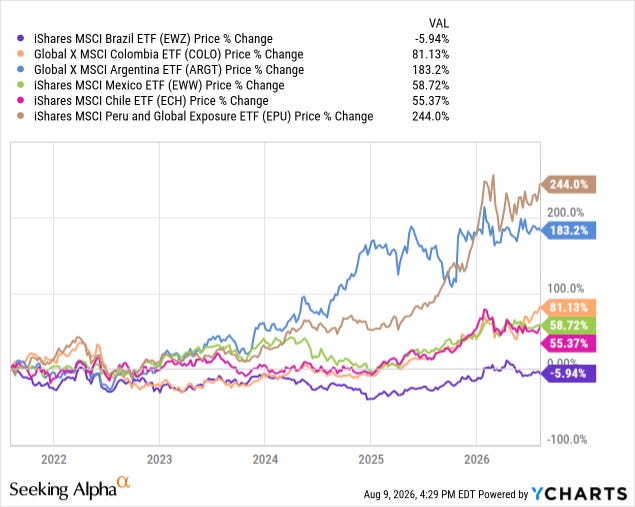
Colombia’s Abelardo de la Espriella signals tax cuts and an Ecopetrol revival, while Inter & Co.
Cerebras’s upcoming WSE 3.5 targets power delivery and clock speeds; the analysis argues parametric yield, not defect routing, is key to…
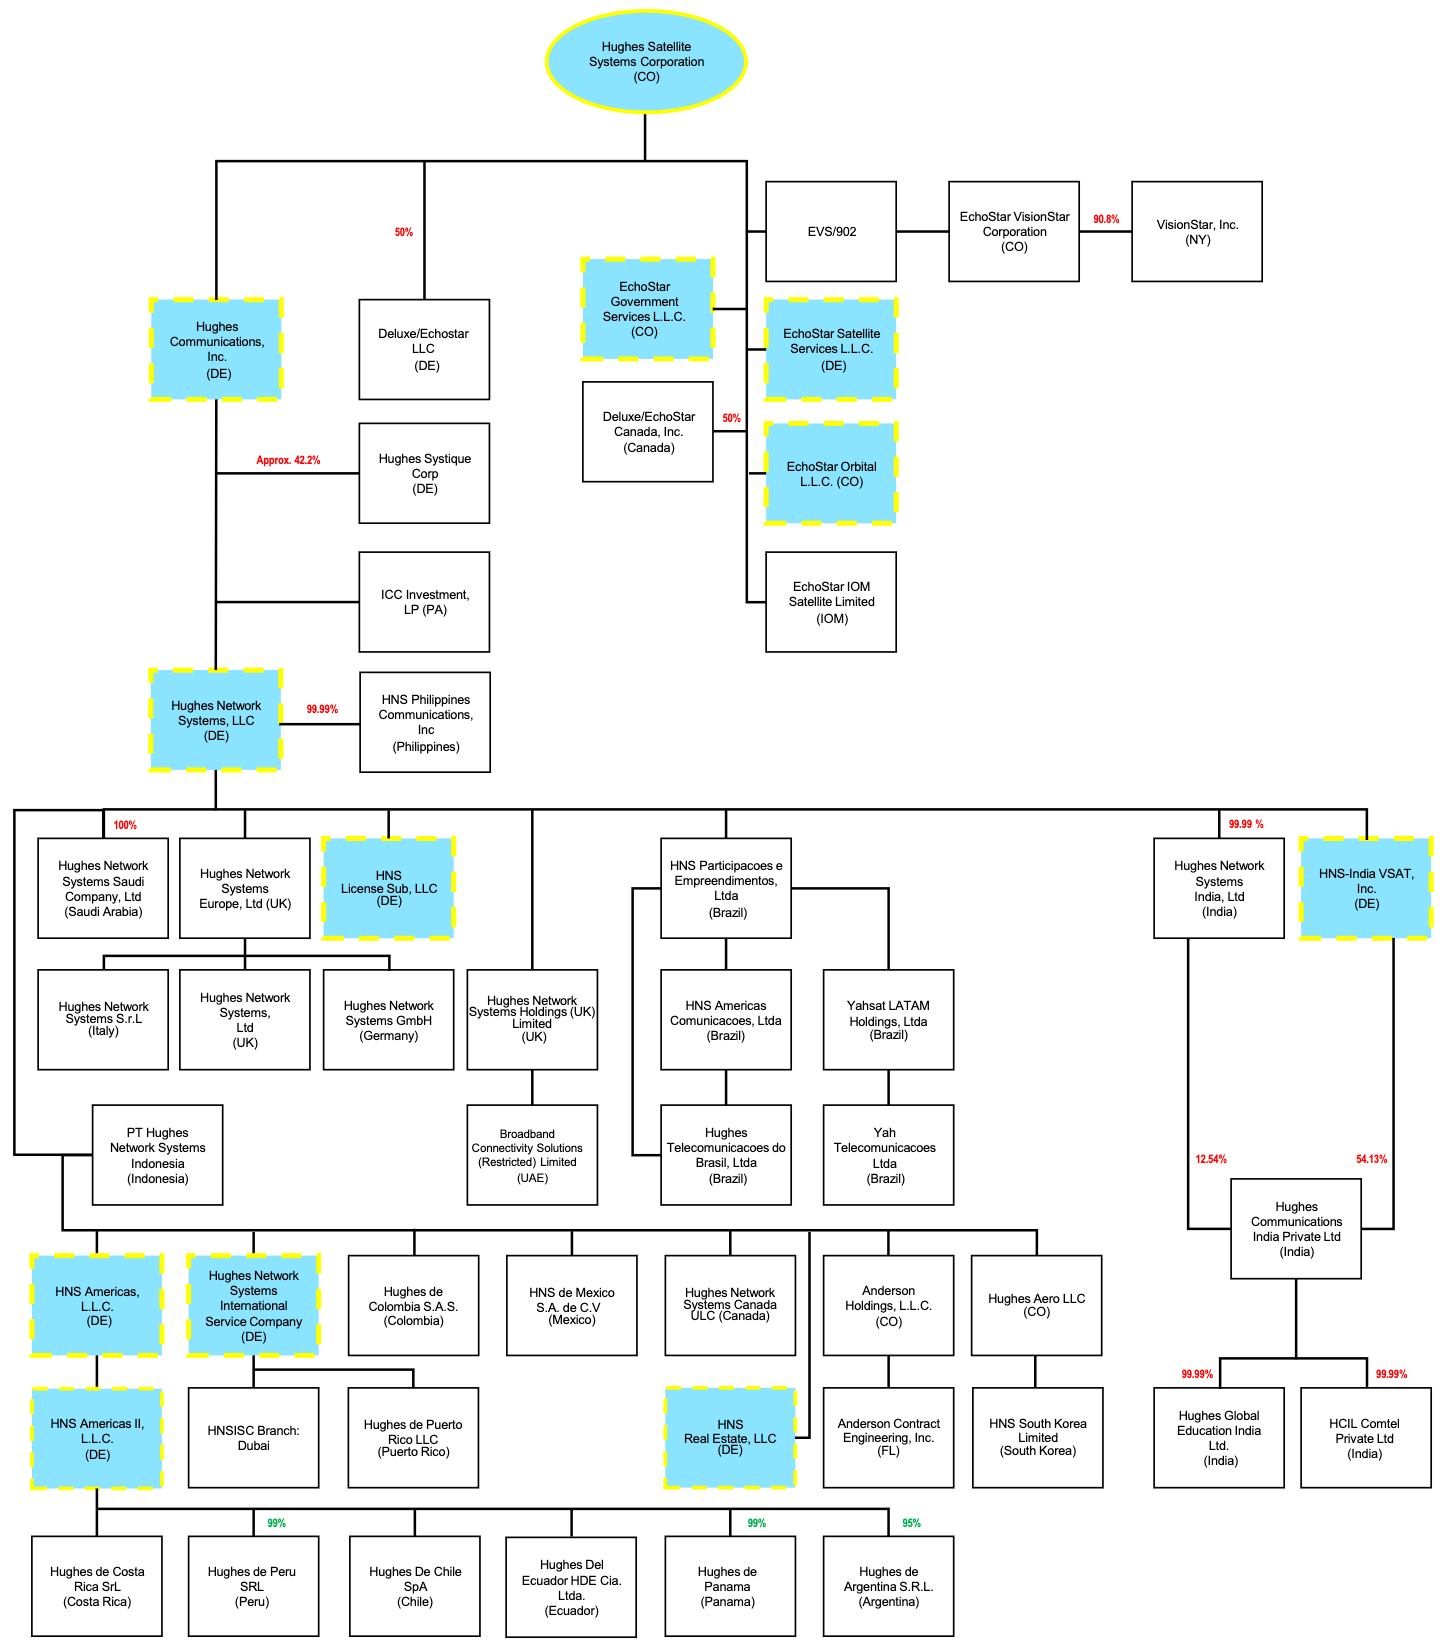
Hughes Satellite Systems, owned by EchoStar, and 11 affiliates filed Chapter 11 cases in the Southern District of Texas on August 2, 2026.
Genius Sports reported $195.5 million revenue, up 65%, and signed Kalshi for soccer data, expanding sports-data sales to prediction markets…
Aquarian won Brighthouse Financial despite a lower bid after higher offers failed to secure reinsurance for its legacy liabilities and thin…
Bumble fell, Shift4 dropped 23% and WeightWatchers rose 18% after earnings, prompting added Shift4 exposure and a sharp WeightWatchers…
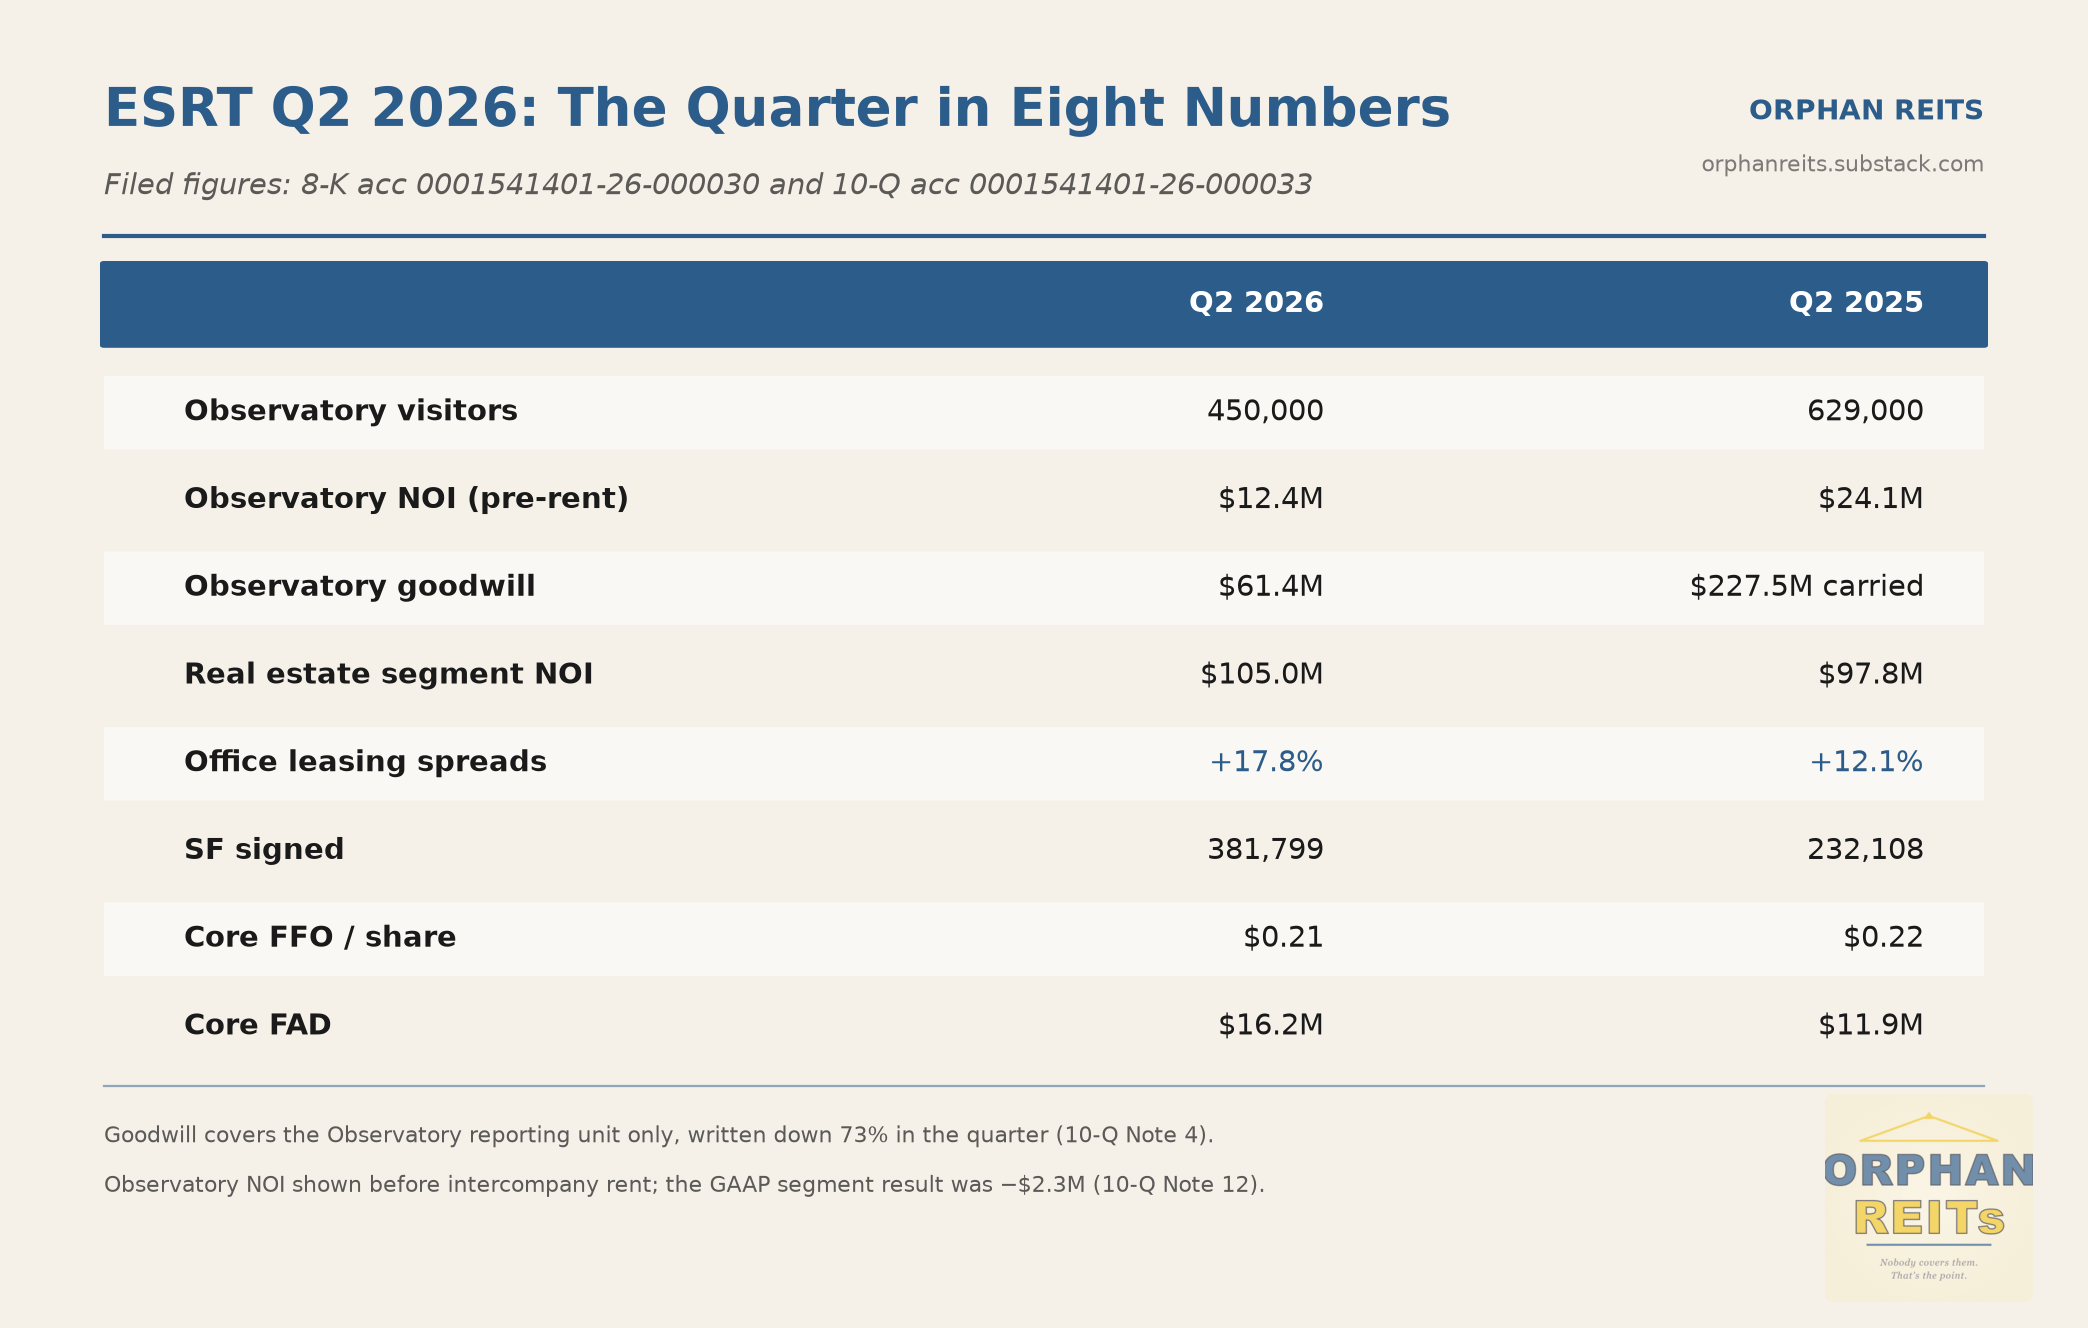
ESRT’s Observatory impairment and accelerating visitation decline weaken its non-office thesis, yet downside valuation cases put shares at…
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Atlas Diary
 Bay Area Ideas
 Benjamin C. Barry
 Bernard Zambonin
 Blake Winiecki
 Capital Connoisseur
 Chetan Woodun
 Crimson And Gold Research
 Cypriot Invests
 Dane Bowler
 Daniel Bell Daniel Jones
 Daniel Schönberger
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Gil Rotstein Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Kevin Avroutskii
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Louis Gerard
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Nicolas Bolsinger
 Oakoff Investments
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Sanjay Swamy
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 Terry Chrisomalis
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Yiannis Zourmpanos
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.