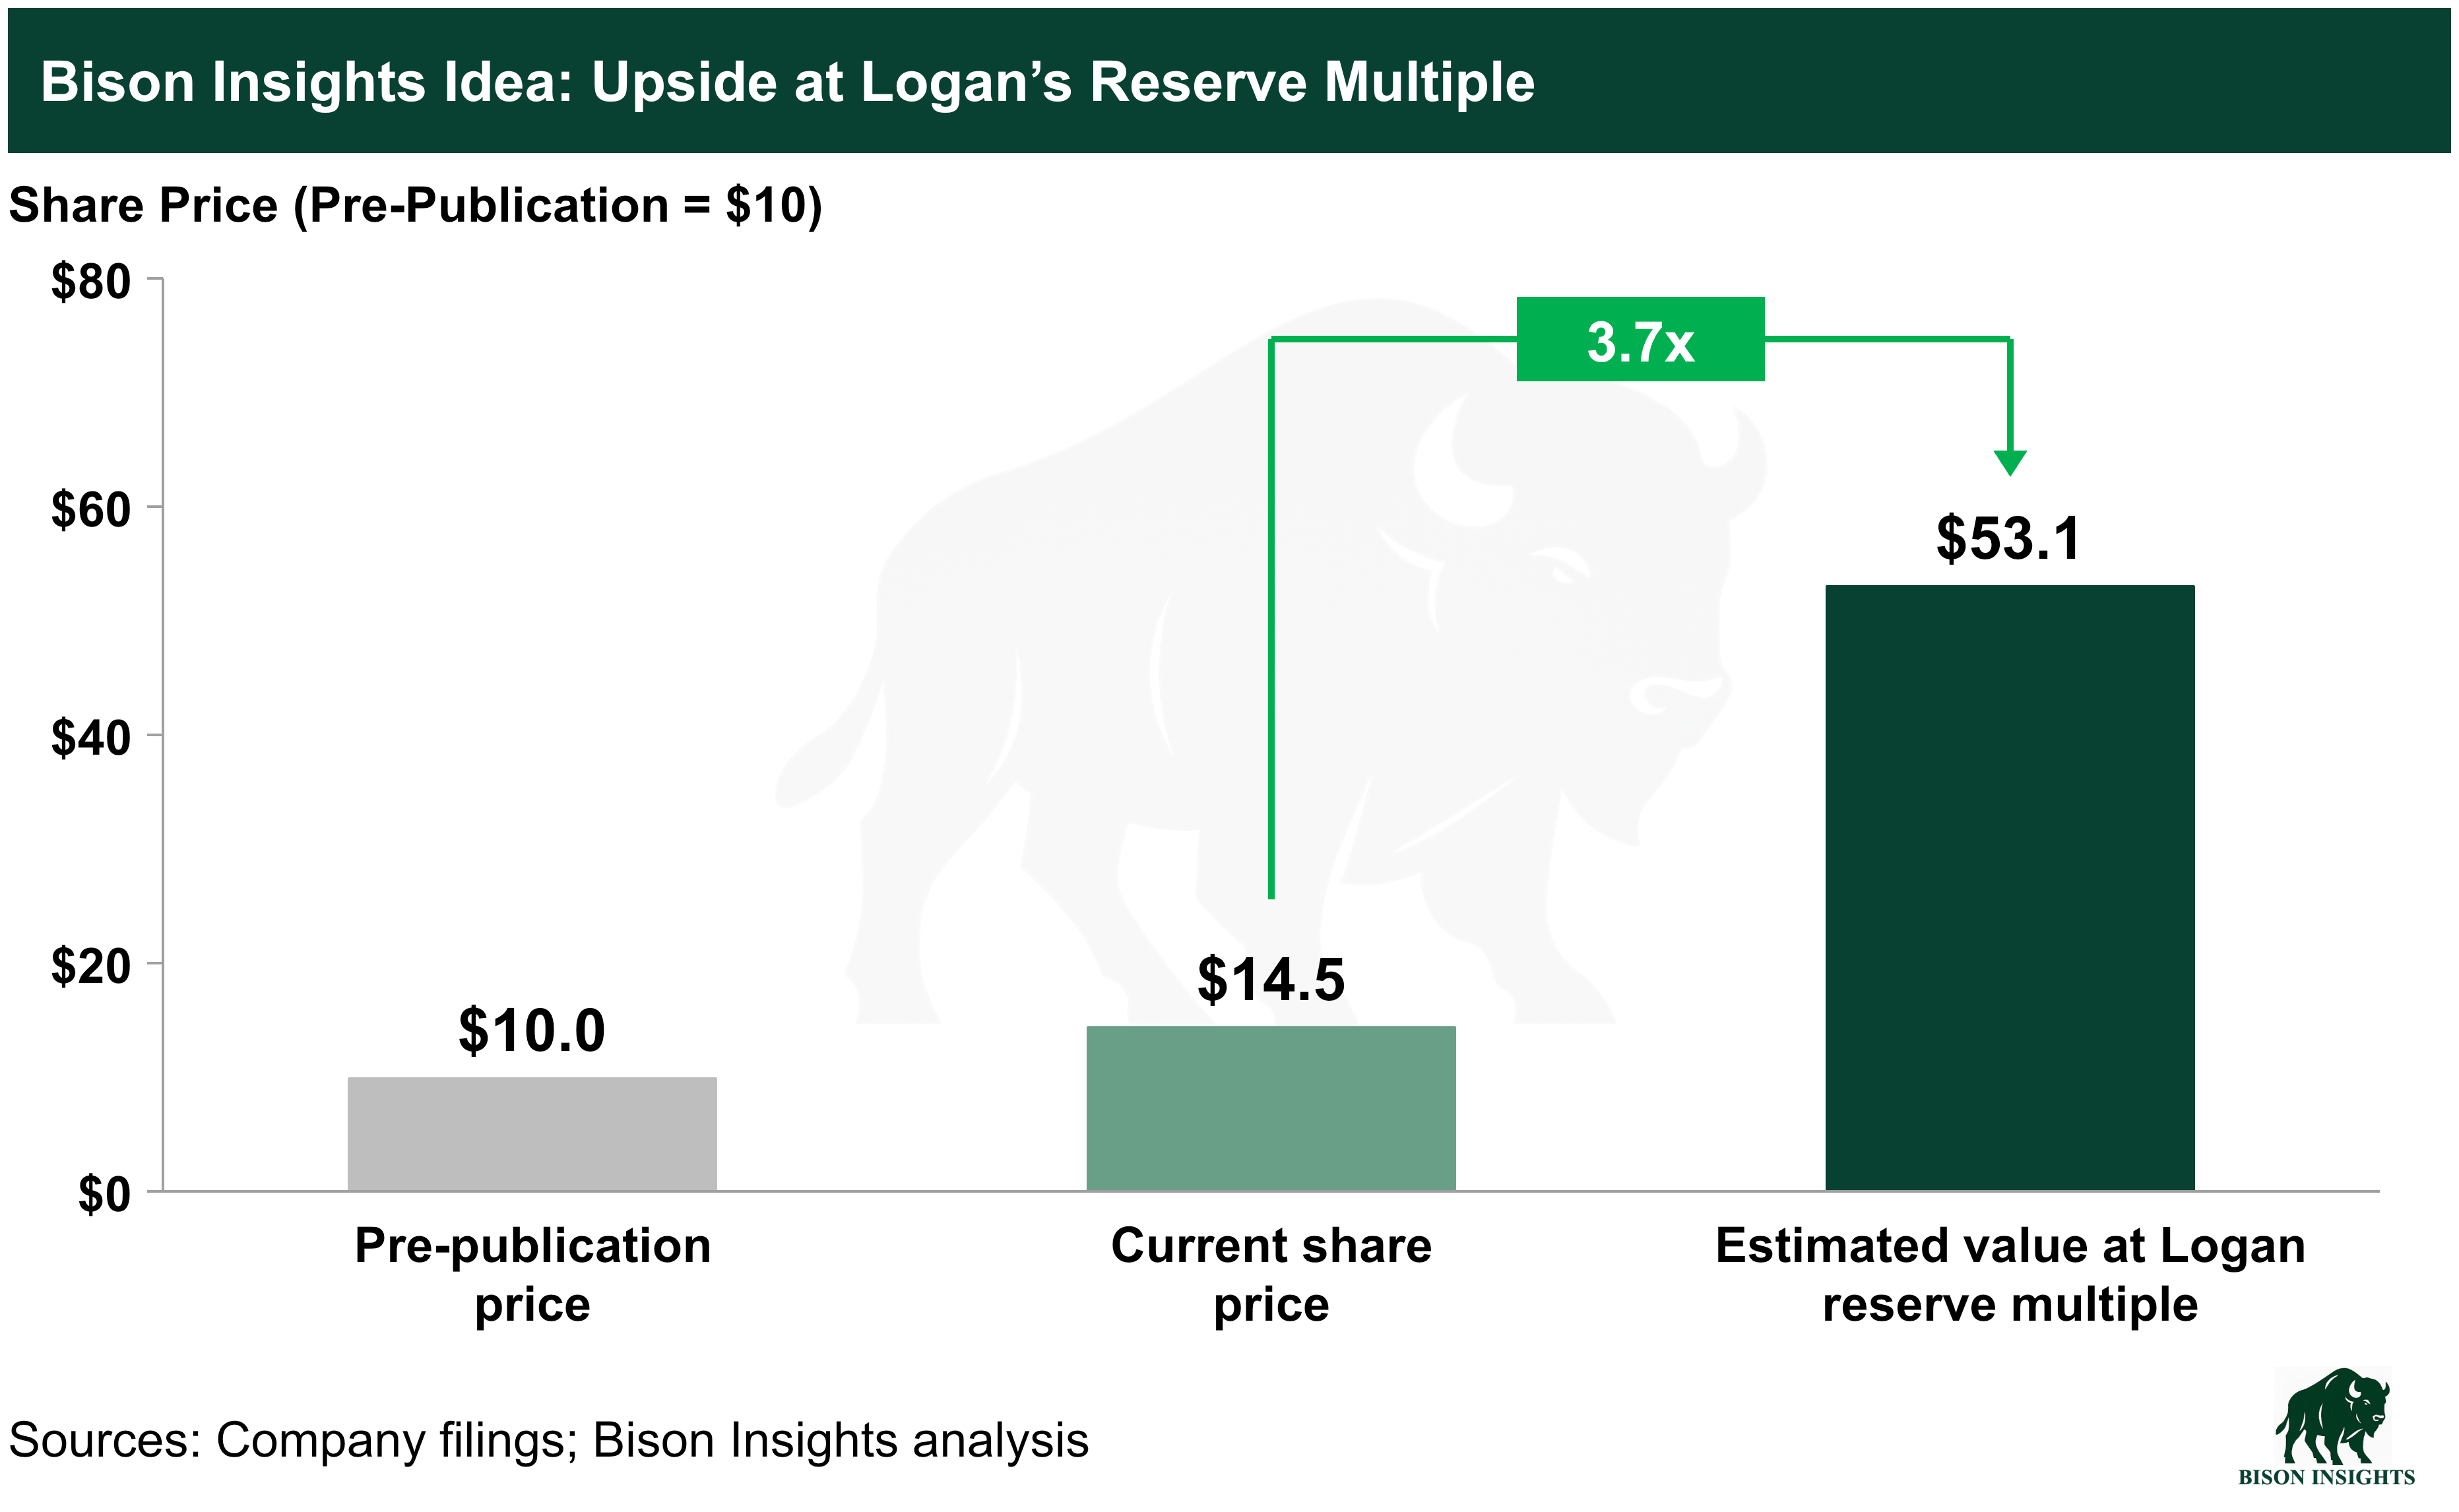David Orr argues AI compute capex will create a major oversupply, pressuring semiconductor trades, software moats and white-collar wages…
YT The Monetary Matters Network 5h ago 2 clicks
BL Clark Street Value 21h ago 3 clicks
Teads’ revenue fell 26% and its stock dropped 38% as Google AI summaries cut publisher referral traffic, worsening losses and straining its…
S PETITION 29h ago 2 clicks
Cars.com is assessed through Buffett-style owner earnings, focusing on cash retained after maintenance capital spending rather than GAAP…
S The Owner's Memo 30h ago 1 click
Quantum Corp. surged while Quantum Computing slumped again after their Tuesday reports.
BL The Technology Letter 42h ago 3 clicks
Lion Copper targets 2030 Nevada copper production at Yerington, with Rio Tinto’s Nuton funding its 2027 feasibility study under a 65%…
BL Atrium Research - Equity Research 42h ago 3 clicks
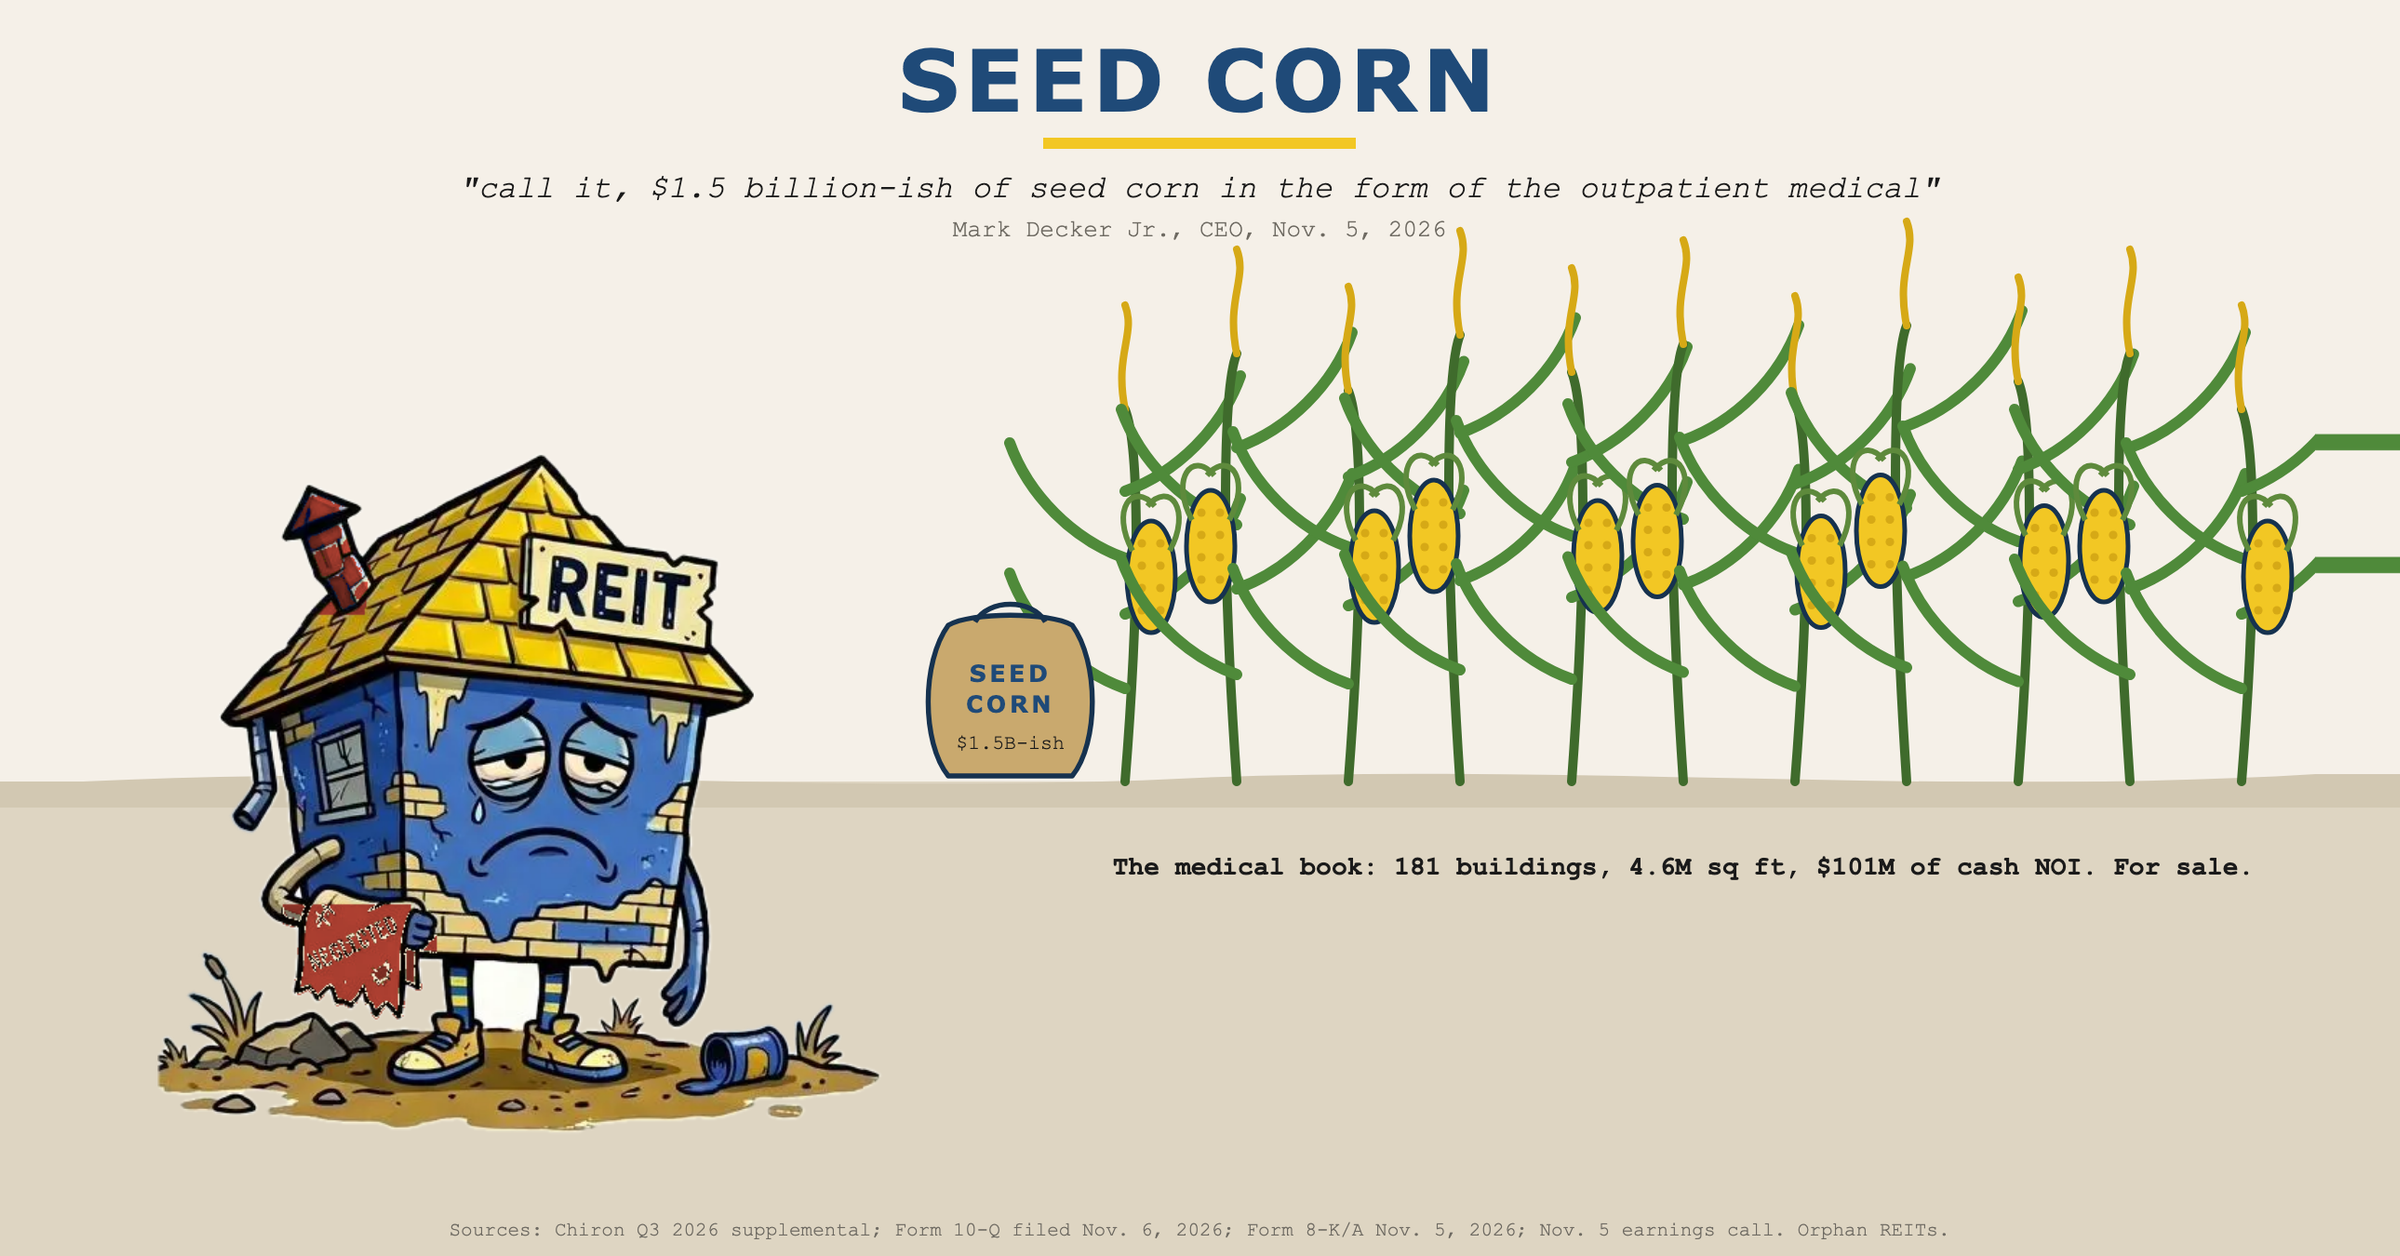
Chiron’s failed $49 million Beaumont sale and $178 million Pinnacle acquisition leave XRN with $70 million of liquidity and medical-office…
S Orphan REITs Nov 9 3 clicks
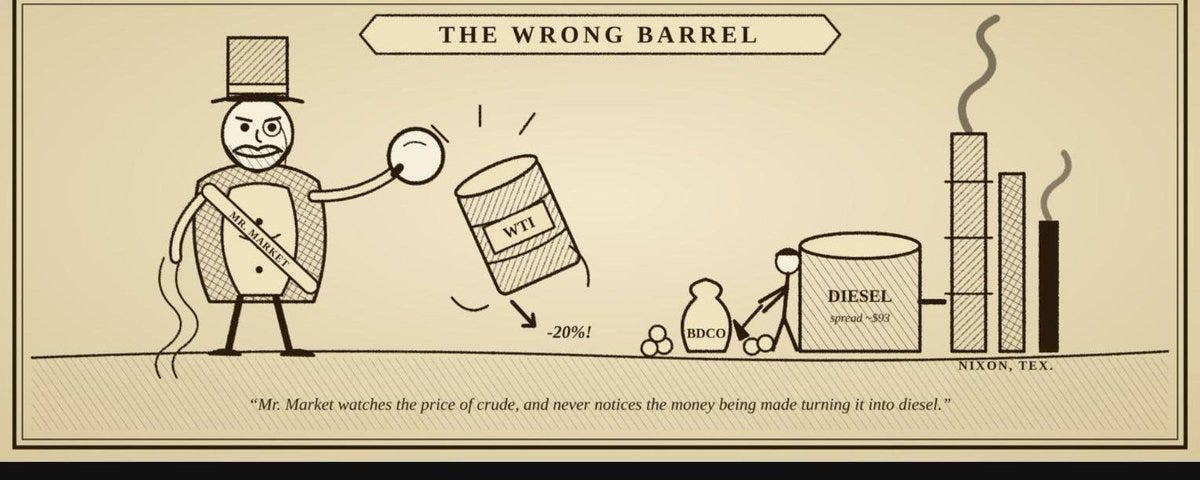
Blue Dolphin Energy trades near 1.3 times earnings as its Texas refinery benefits from diesel shortages, with projected 2026 EBITDA of $111…
S Capital Employed Nov 8 6 clicks
Blue Dolphin’s 15,000-barrel-per-day Texas refinery earned $2.18 per share in first-half 2026 as diesel shortages widened crack spreads,…
S Calvin Blissett Nov 8 2 clicks
NGVC · long Natural Grocers (NGVC) returned to $27.80 after a prior long entry at $21 and exit recommendation at $46.
BL Value Investors Club Aug 11
EVC's Q3 update cites $30 million for a single station, a broadcast-business sale and stronger positioning for 2027.
S Nat Stewart - Stock Picking Newsletter Nov 6 26 clicks
Ovintiv’s C$1.26 billion purchase of Logan Energy at roughly 2x proved reserve value points to further consolidation among Canadian oil…
S Bison Insights Nov 6 4 clicks
Entravision’s Q3 ad-tech revenue reached $177.2 million, up 133% year over year, while total revenue rose 88% to $226.3 million and diluted…
S The Value Road Nov 6 4 clicks
CareCloud rebuilt its sales organization under Christopher Langehaug after 18 months without a sales leader, with a second sales rep…
S Calvin Blissett Nov 6 7 clicks
Diversified Energy reported $255.6 million of “true” nine-month free cash flow, while its $1.8 billion Birch acquisition would shift…
S The Oak Bloke Nov 6 4 clicks
CareCloud’s Q3 revenue rose 9% through acquisitions but fell 8% pro forma; the RCM consolidator targets 25–30% margins by shifting acquired…
S Calvin Blissett Nov 6 2 clicks
BL Clark Street Value Nov 5 5 clicks
AutoNation, Lear, NexPoint, AudioCodes and Xponential Fitness lead a 52-situation screen spanning buybacks, insider purchases, M&A and…
S Latticework by MOI Global Nov 5 6 clicks
Nine Mile Metals is the subject of a research note.
BL Atrium Research - Equity Research Nov 4 5 clicks