Quick note on LSAK and GRPN
Lesaka expects its Bank Zero acquisition to close by end-January 2027, though it could still close this calendar year.
Lesaka expects its Bank Zero acquisition to close by end-January 2027, though it could still close this calendar year.
@Edi_the_don_ @dcblocher @NerdcapK @Jijdnf @eric7411 @aakashchhunchha @JLTazzy @KK_Investing @see_dog_cap @Cameron_Invest @asymetricbets Sorry Edi not watchable, next one on $CCLD will be, full transcript is above though
This is going to be very relevant for a position I'm about to write-up on Seeking Alpha.... Not $MNRO but definitely helps them too.... For another stock - this is a dream forecast.... especially with over 50% of the float sold short....
Goldman notes $ACMR’s strong guide, Chinese memory exposure, and increasing localization, driving revenues and earnings for the next few years. $140 PT on 31x ‘30 EPS discounted back. While I might not value it that way, who am I to argue?
have been out of $SNWV for several months but I just put a stinkbid in at $1.50. Feel free to hit it!
$CCOI My call with Dave Schaeffer is up. Full Q&A on data center sales, the $700M refi, IPv4, note buybacks and life after the T-Mobile payments.
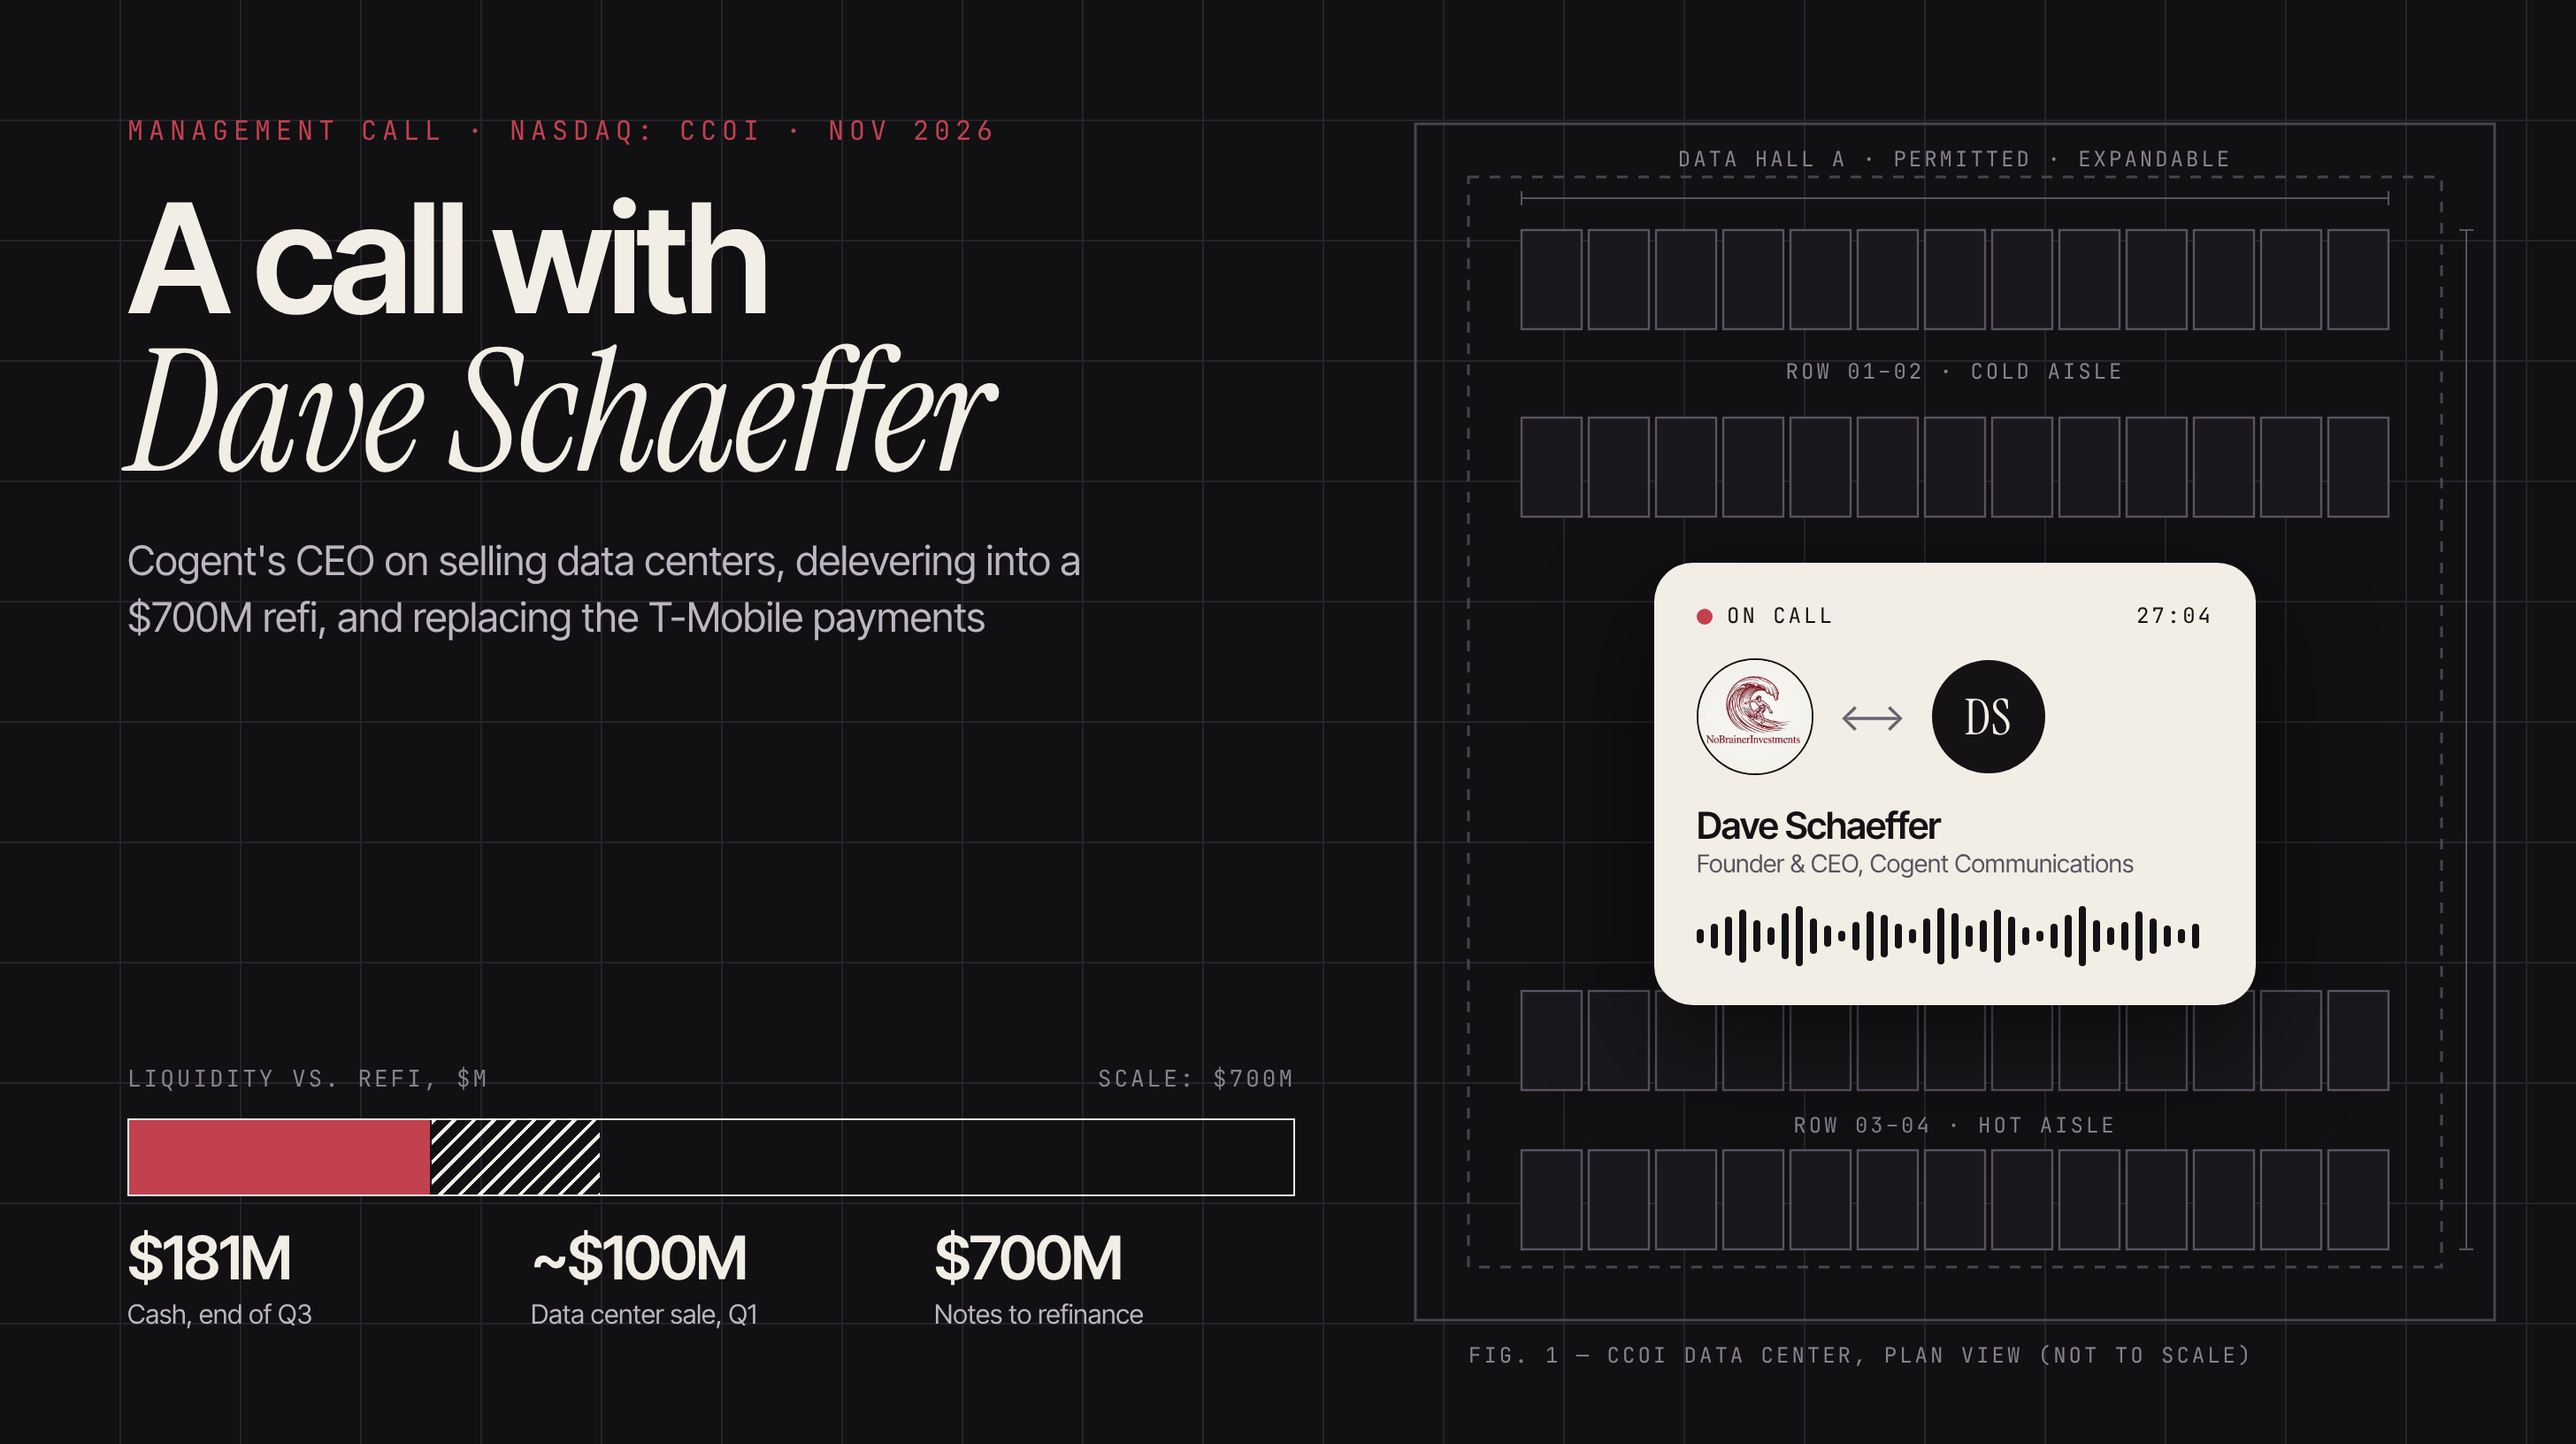
Cogent expects to replace roughly $100 million of T-Mobile payments ending in 2028 through cost cuts and high-margin on-net sales, while…
TransMedics targets multi-organ transplant growth through 2027 trials, OCS Kidney and European expansion after Q3 revenue rose 41% to $203…
 Conviction Queue
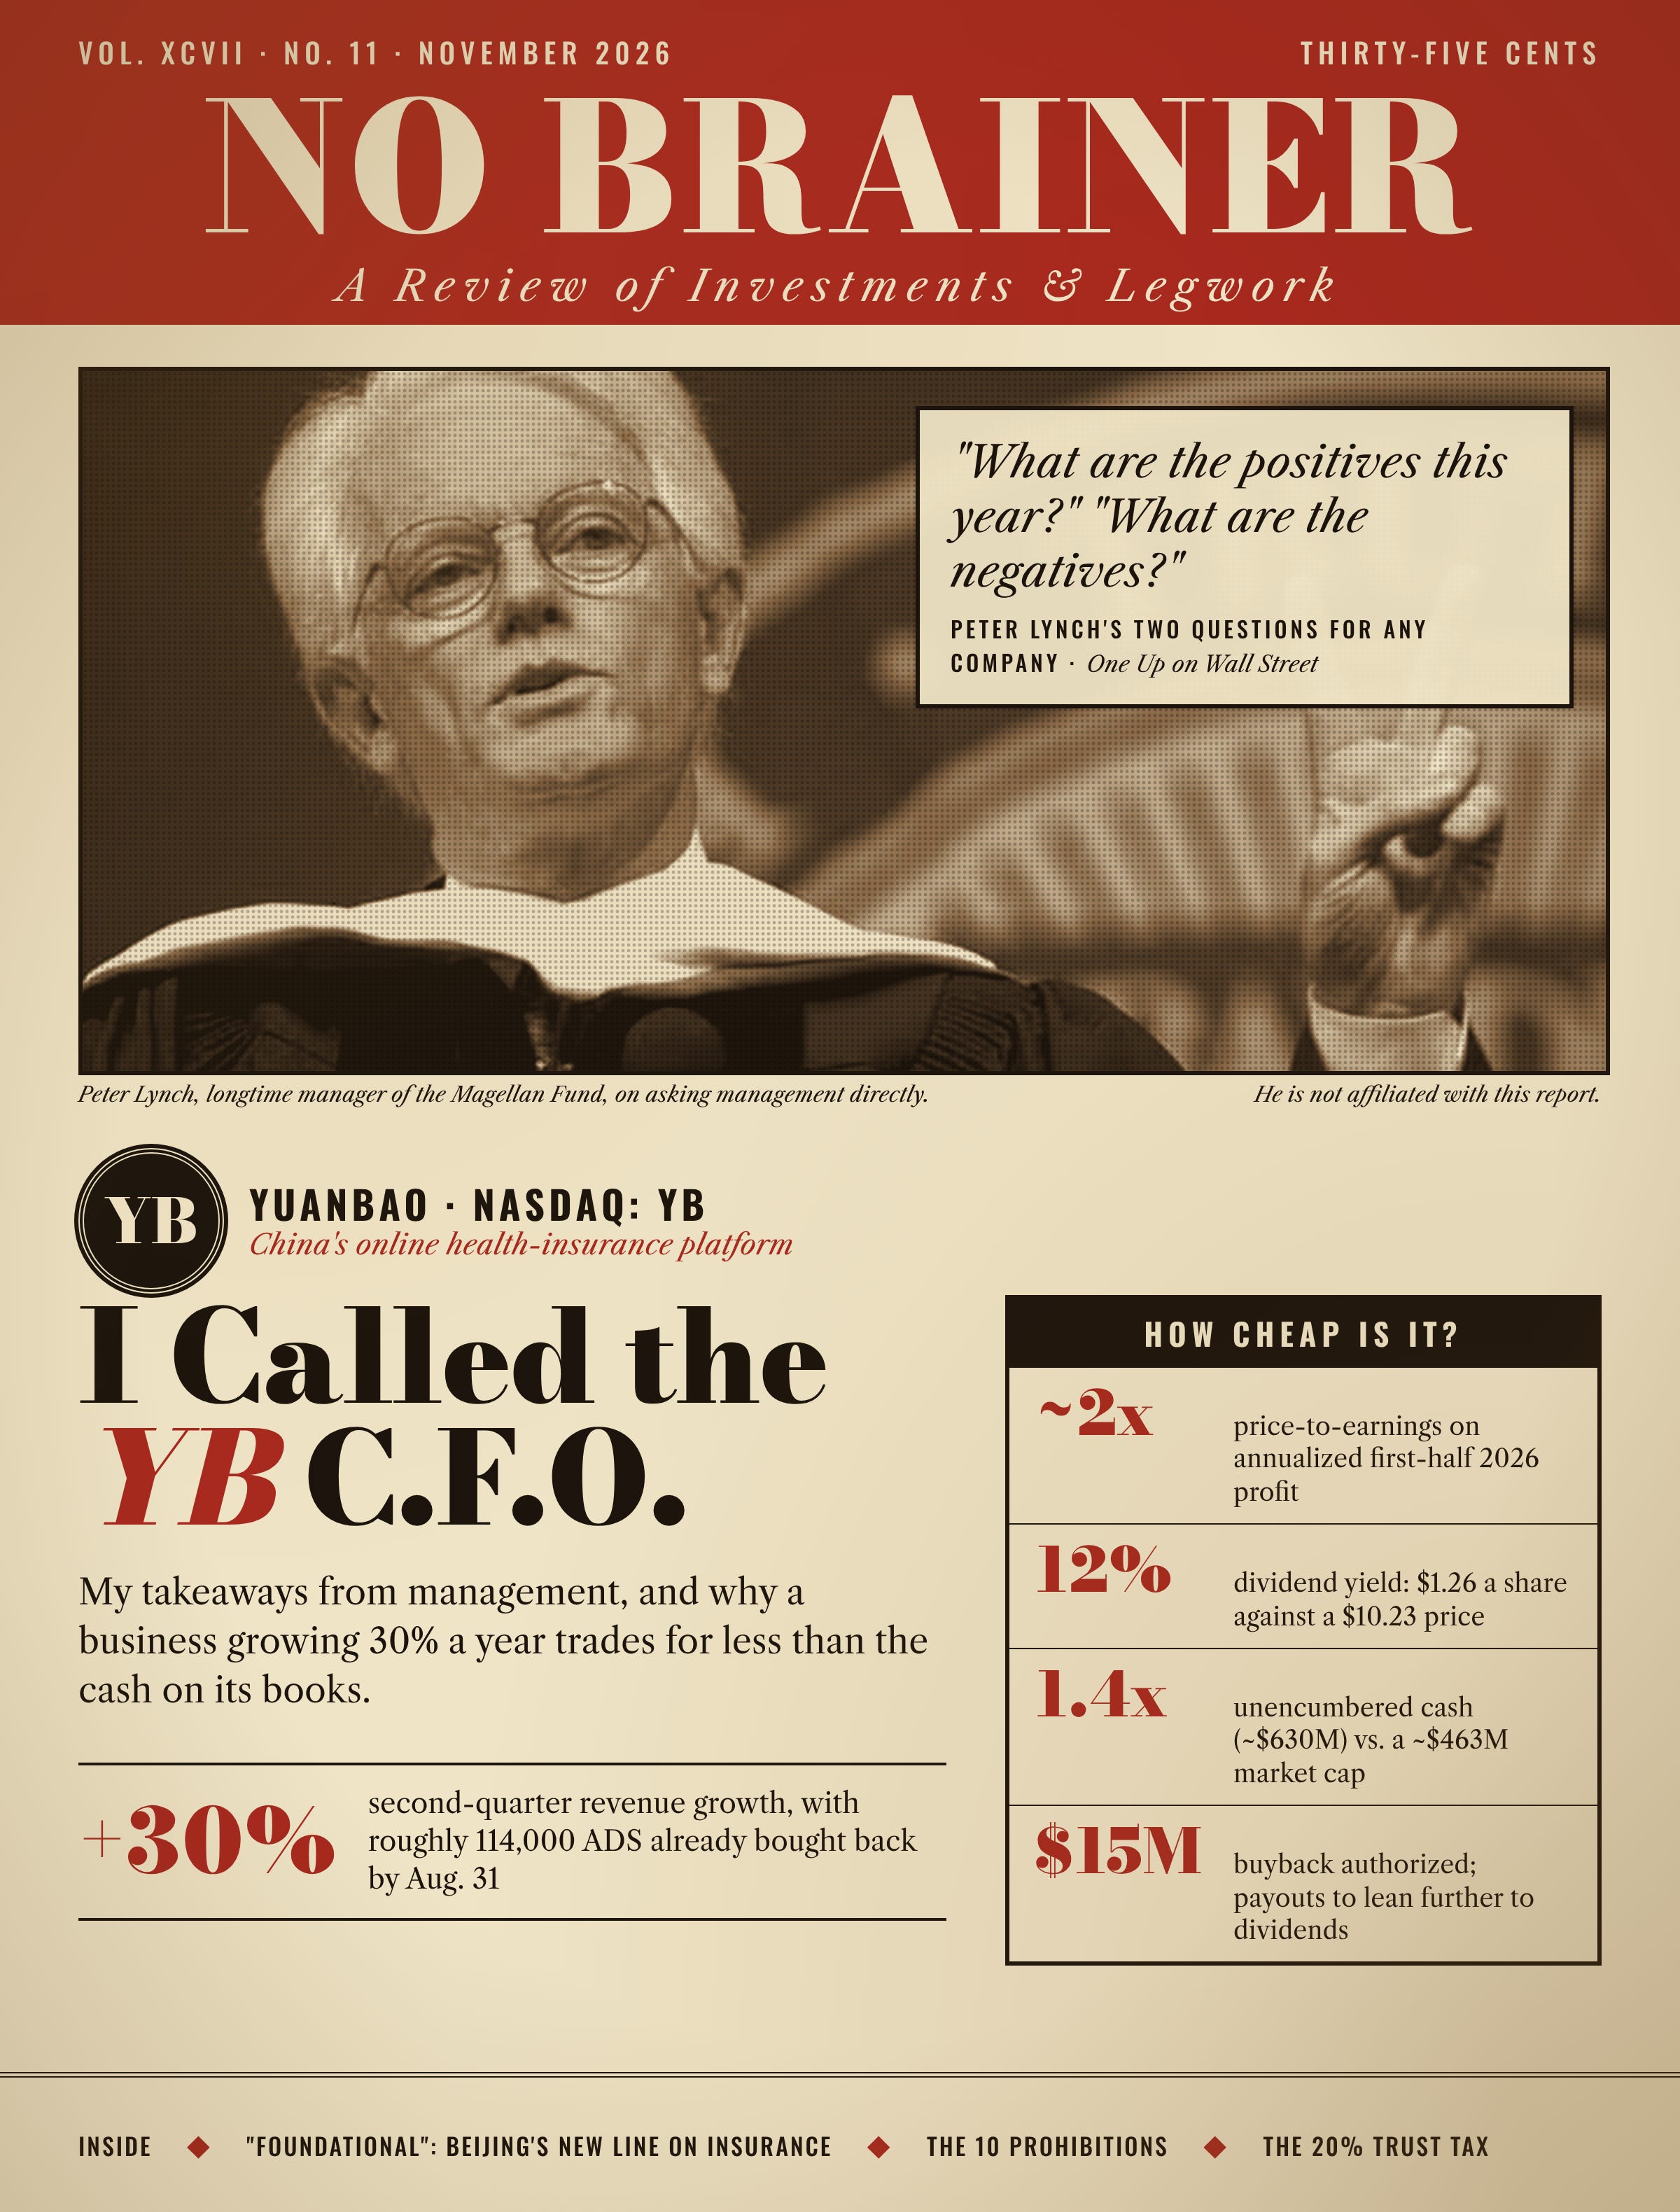
Yuanbao’s CFO says China’s new online-insurance rules target abusive sales practices, while Beijing increasingly frames commercial health…
Village Farms posted record quarterly cannabis revenue, driven by international sales and expanded capacity, while positioning for Texas…
 Alan Sumler 1 click

David Orr argues AI compute capex will create a major oversupply, pressuring semiconductor trades, software moats and white-collar wages…
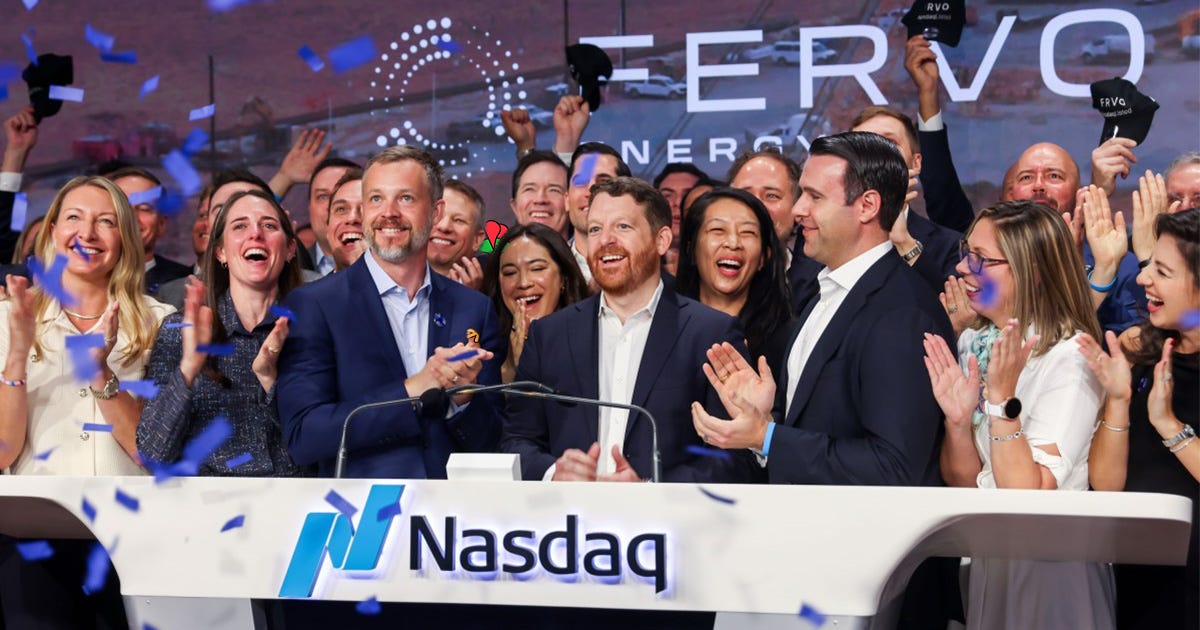
Fervo Energy raised $2 billion in its May IPO, then fell nearly 70% below issue price after a Morpheus short report, despite targeting 1 GW…
Six Flags faces declining deferred revenue, $615.9 million of goodwill impairments and roughly 6.5x EBITDA leverage despite solvency…
 Sanjay Swamy

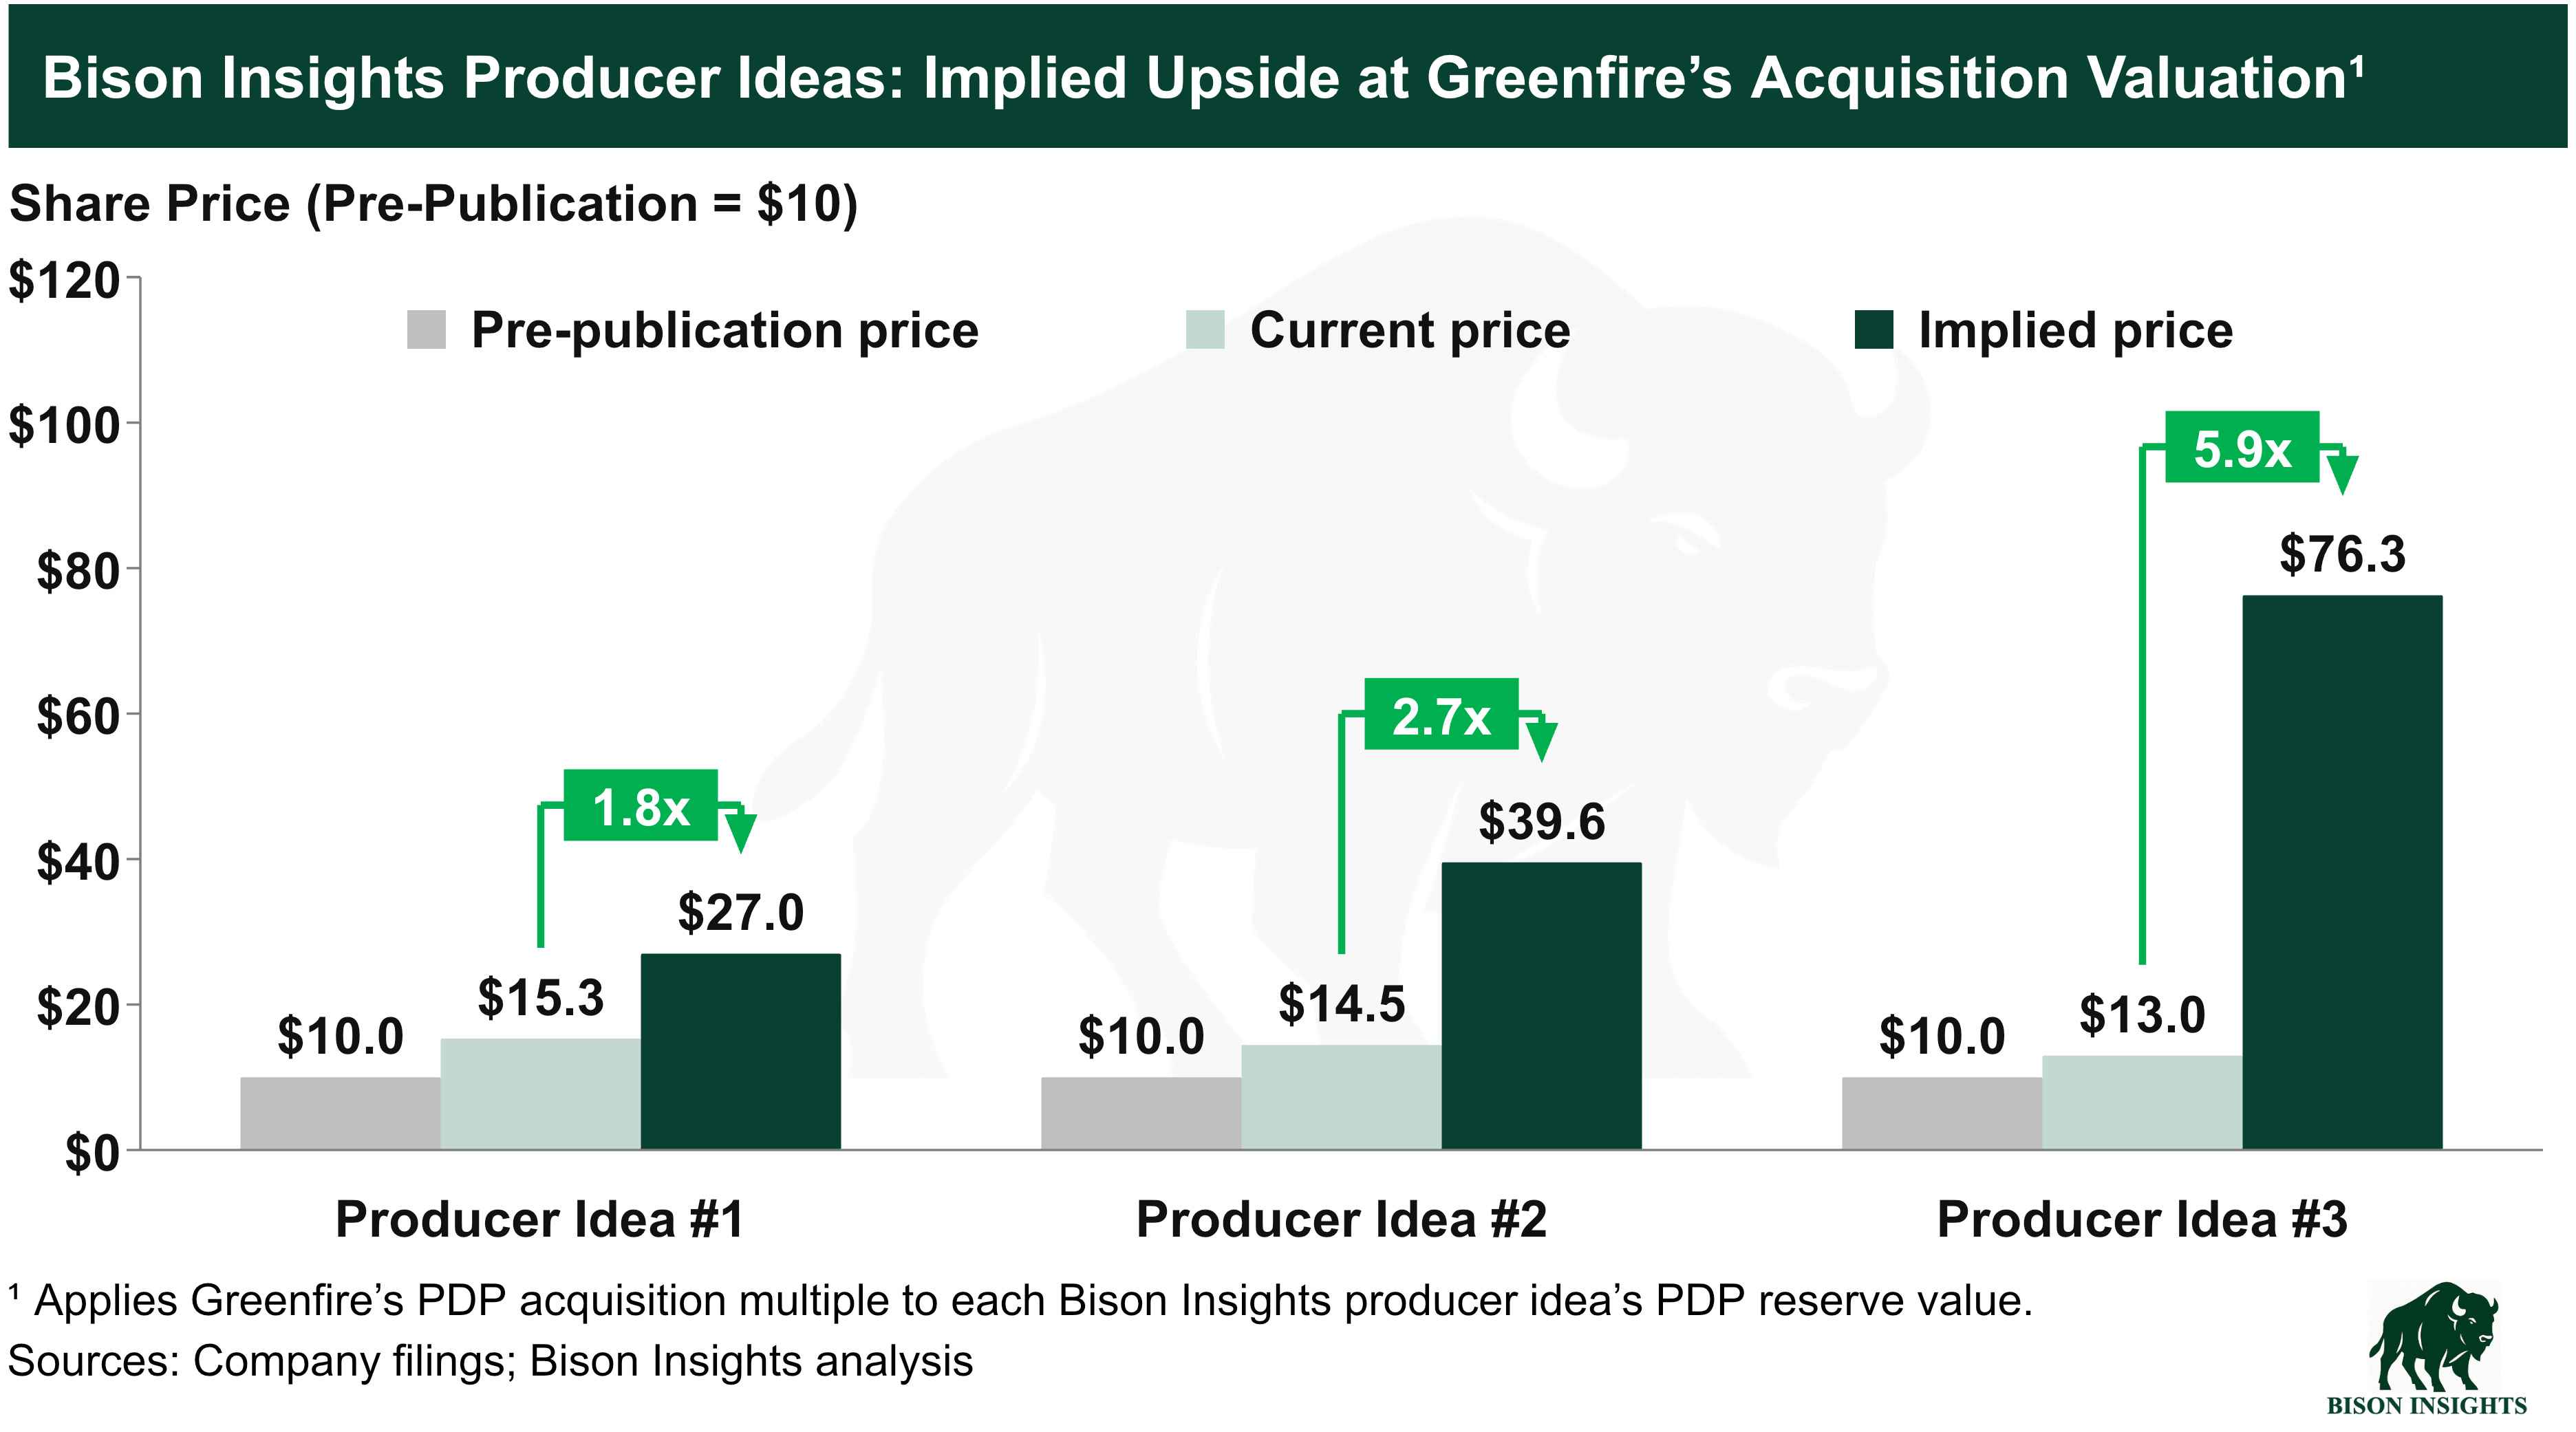
Strathcona Resources will acquire Greenfire Resources for C$2.8 billion including debt, valuing the Canadian heavy-oil producer at up to a…
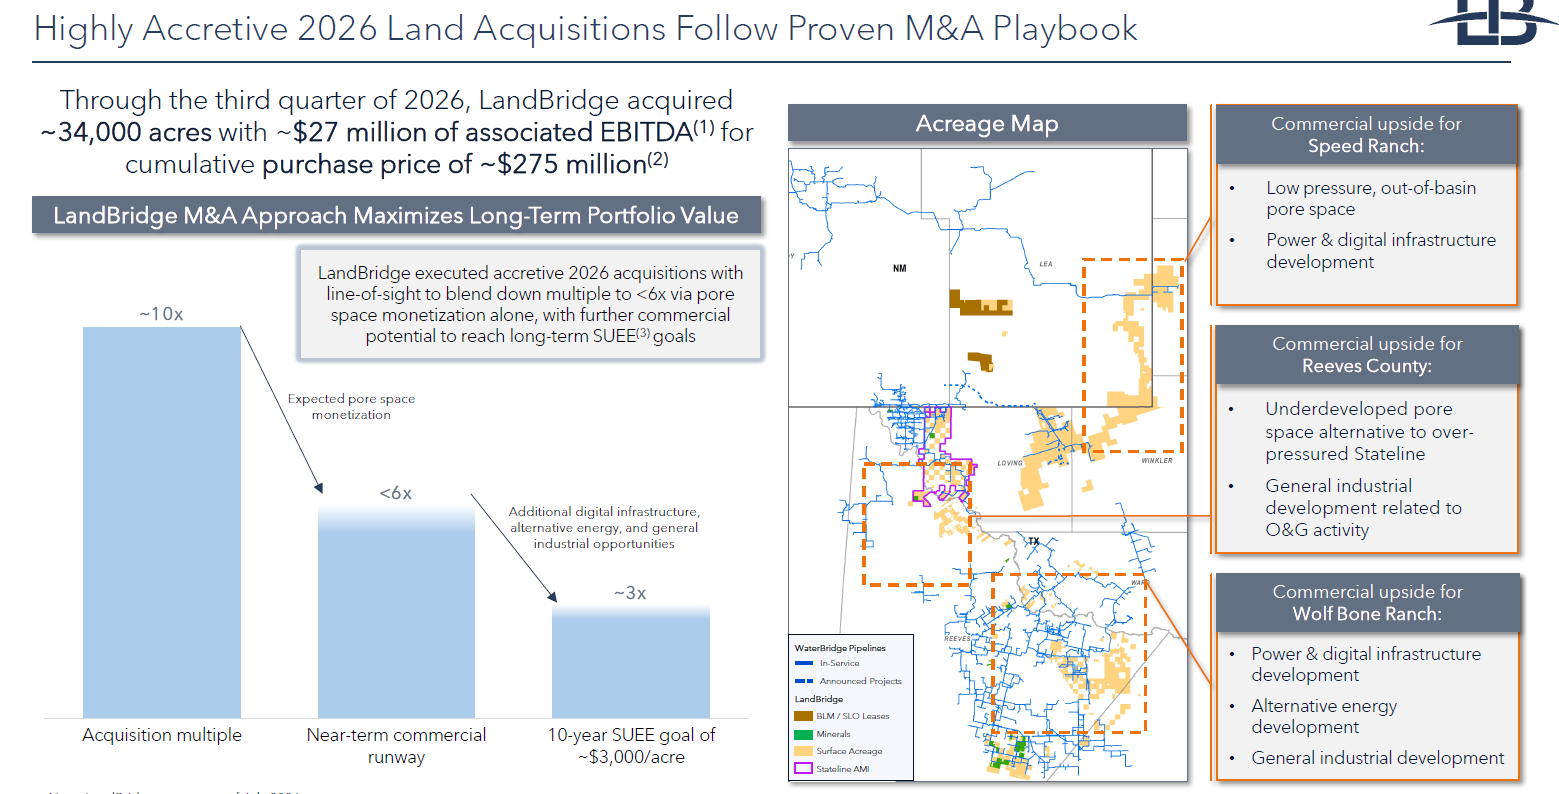
LandBridge’s Q3 revenue rose 39%, while newly acquired pore space could lift pro forma EBITDA and cut its 2027 EV/EBITDA multiple from…
 BYMAF · long
Bolsas y Mercados Argentinos, BYMA, is presented as a long investment idea.
Grindr received a non-binding $18-per-share acquisition offer.
Buzzi SpA, an €8.9 billion Italian cement producer, is presented as the world’s best-managed cement company.
Elastic’s vesting goals reveal what management is incentivizing.
Blend Labs governance discussion focuses on reverse-engineering non-GAAP signals of upside.
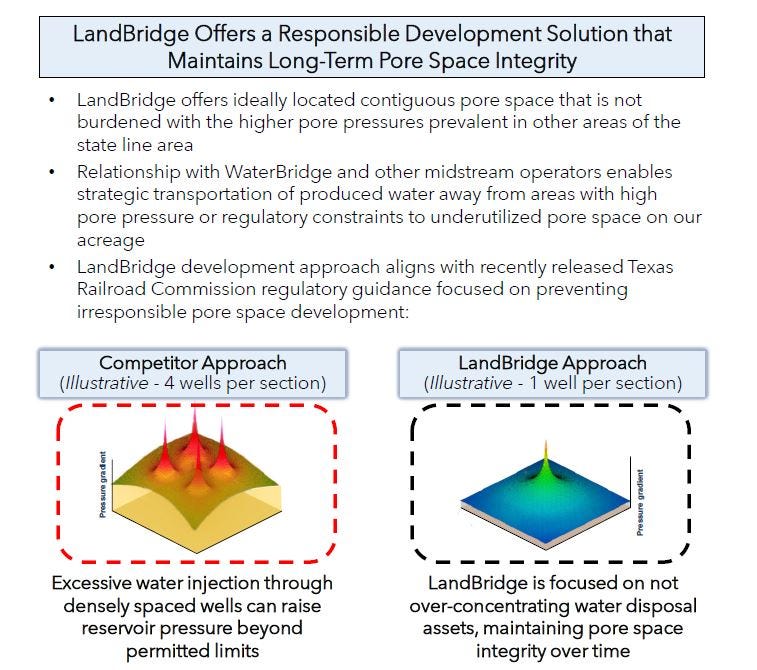
WaterBridge and Secure trade at 10–11x 2025 EBITDA despite produced-water disposal economics resembling higher-multiple municipal waste…
Citizens Bancshares (CZBS) trades below book and parent-level cash while buying back shares, raising its dividend and holding $95.7 million…
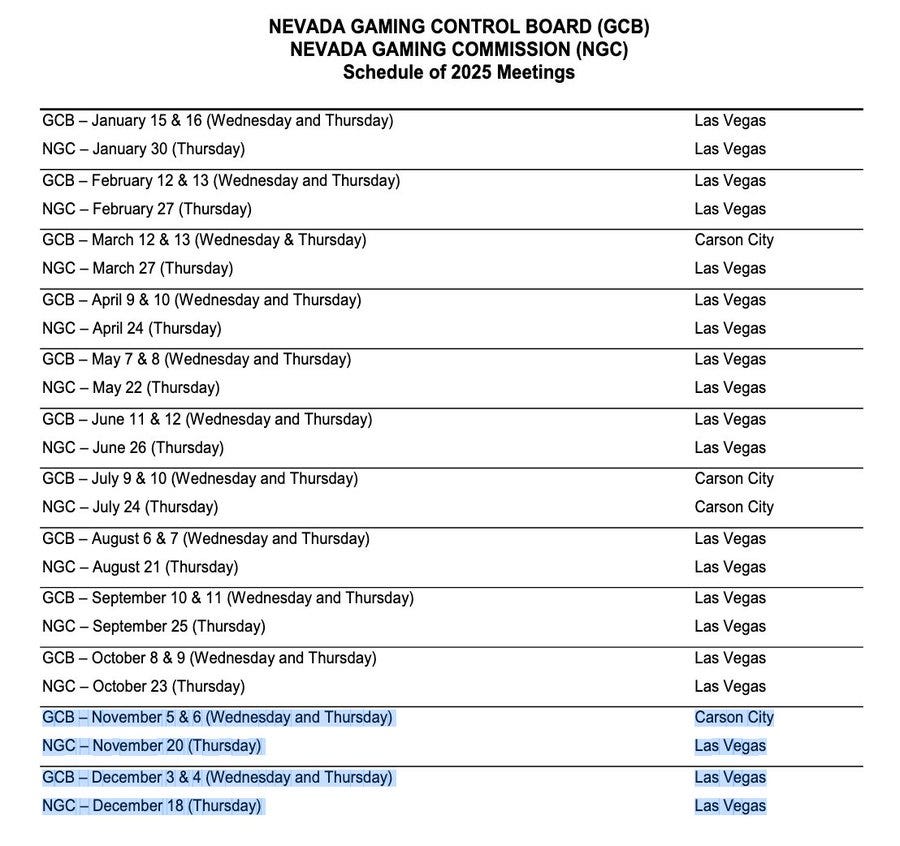
Evolution’s acquisition of Galaxy Gaming awaits regulatory approval, with a claimed 58.7% IRR if completed and a $5 million termination fee…
Arcadia Biosciences plans to merge with Permian E&P Roosevelt Resources, which targets CO2-enhanced recovery from a 13,892-acre Texas field…
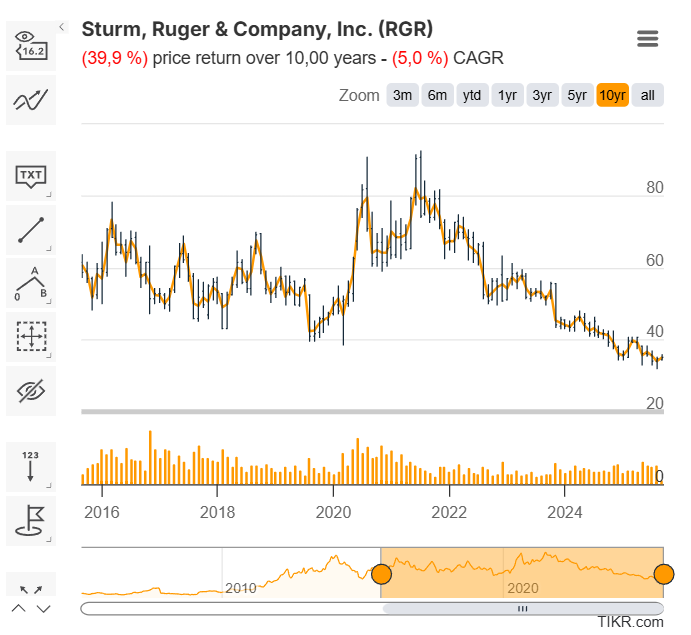
Ruger trades at a $468 million enterprise value, about 7 times normalized free cash flow, with $101 million cash and no debt as gun demand…
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Benjamin C. Barry
 Blake Winiecki
 Capital Connoisseur
 Chetan Woodun
 Crimson And Gold Research
 Cypriot Invests
 Dane Bowler
 Daniel Bell
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Gil Rotstein
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Louis Gerard
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Oakoff Investments
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini Sanjay Swamy
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.