Ouster Q3 FY12/26 Earnings Review (OUST) - Stock Rating: Accumulate
Ouster grew Q3 revenue 50% to $59.3 million, shipped 27,000 sensors and guided Q4 revenue to $61 million to $64 million while posting a $19.3 million operating loss.
Ouster grew Q3 revenue 50% to $59.3 million, shipped 27,000 sensors and guided Q4 revenue to $61 million to $64 million while posting a $19.3 million operating loss.
Softening Colombian Peso, falling interest rates, tariffs going away. Perfect set-up brewing. $TGLS https://t.co/3UHXULRh5V https://t.co/FkvlubmoV8
@TeaBagCapital I’d agree, for me the nearest $SFM is farther than Whole Foods and I have a friend in Seattle where his Sprouts is a hike as well
I had missed that Applebee's and IHOP parent $DIN (like $WEN) rejected a takeover proposal . But then I immediately got distracted by their new menu item Bacon Cheeseburger Wonton Tacos https://t.co/0SemWAJgI9
@TeaBagCapital I think if they continue to stay below or go lower than Whole Foods they win. As someone who buys into all that health stuff $SFM has a much more relevant, comprehensive, niche selection of these trendy healthy items
Soooo, trying to get updated on the mess that is Gildan... was the board perhaps correct in their assessment back in '23? $GIL https://t.co/jDpcgVsj9x
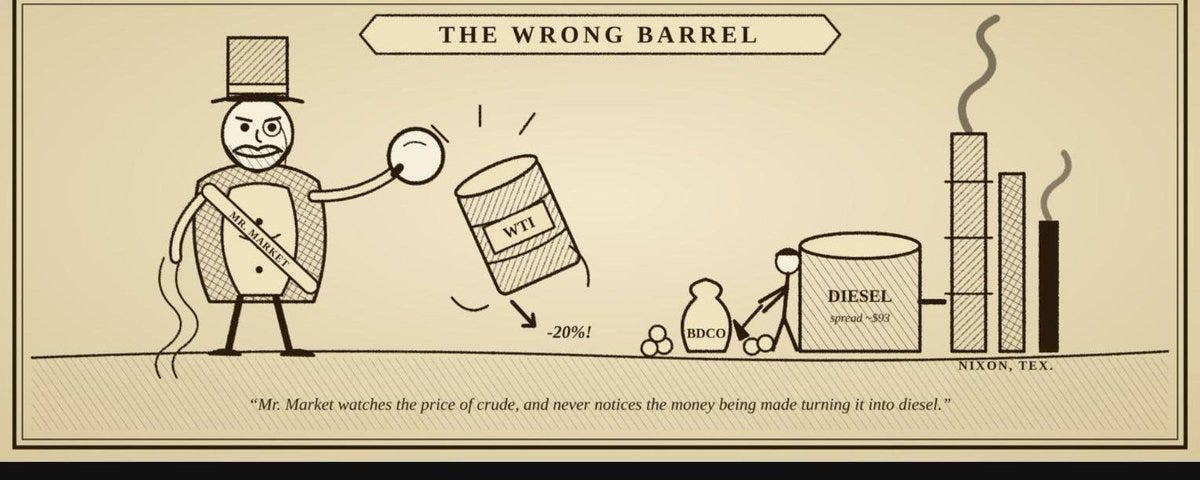
Blue Dolphin’s 15,000-barrel-per-day Texas refinery earned $2.18 per share in first-half 2026 as diesel shortages widened crack spreads,…
Park Hotels & Resorts grew Q3 occupancy and RevPAR as renovations supported group and leisure demand, while leverage, Hawaii exposure and…
 Albert Anthony 1 click
Perimeter Group posted 24% revenue growth to $390 million as fire-safety contracts and acquisitions lifted results, while it brings PDI…

Perimeter Group's third-quarter revenue rose 24% to $390 million as fire safety recovered and Specialty Products grew 84%, while…

AMD’s data-center revenue rose 97%, while MercadoLibre, TIC Solutions, XPEL and Zoetis also report quarterly results.
EVC's Q3 update cites $30 million for a single station, a broadcast-business sale and stronger positioning for 2027.
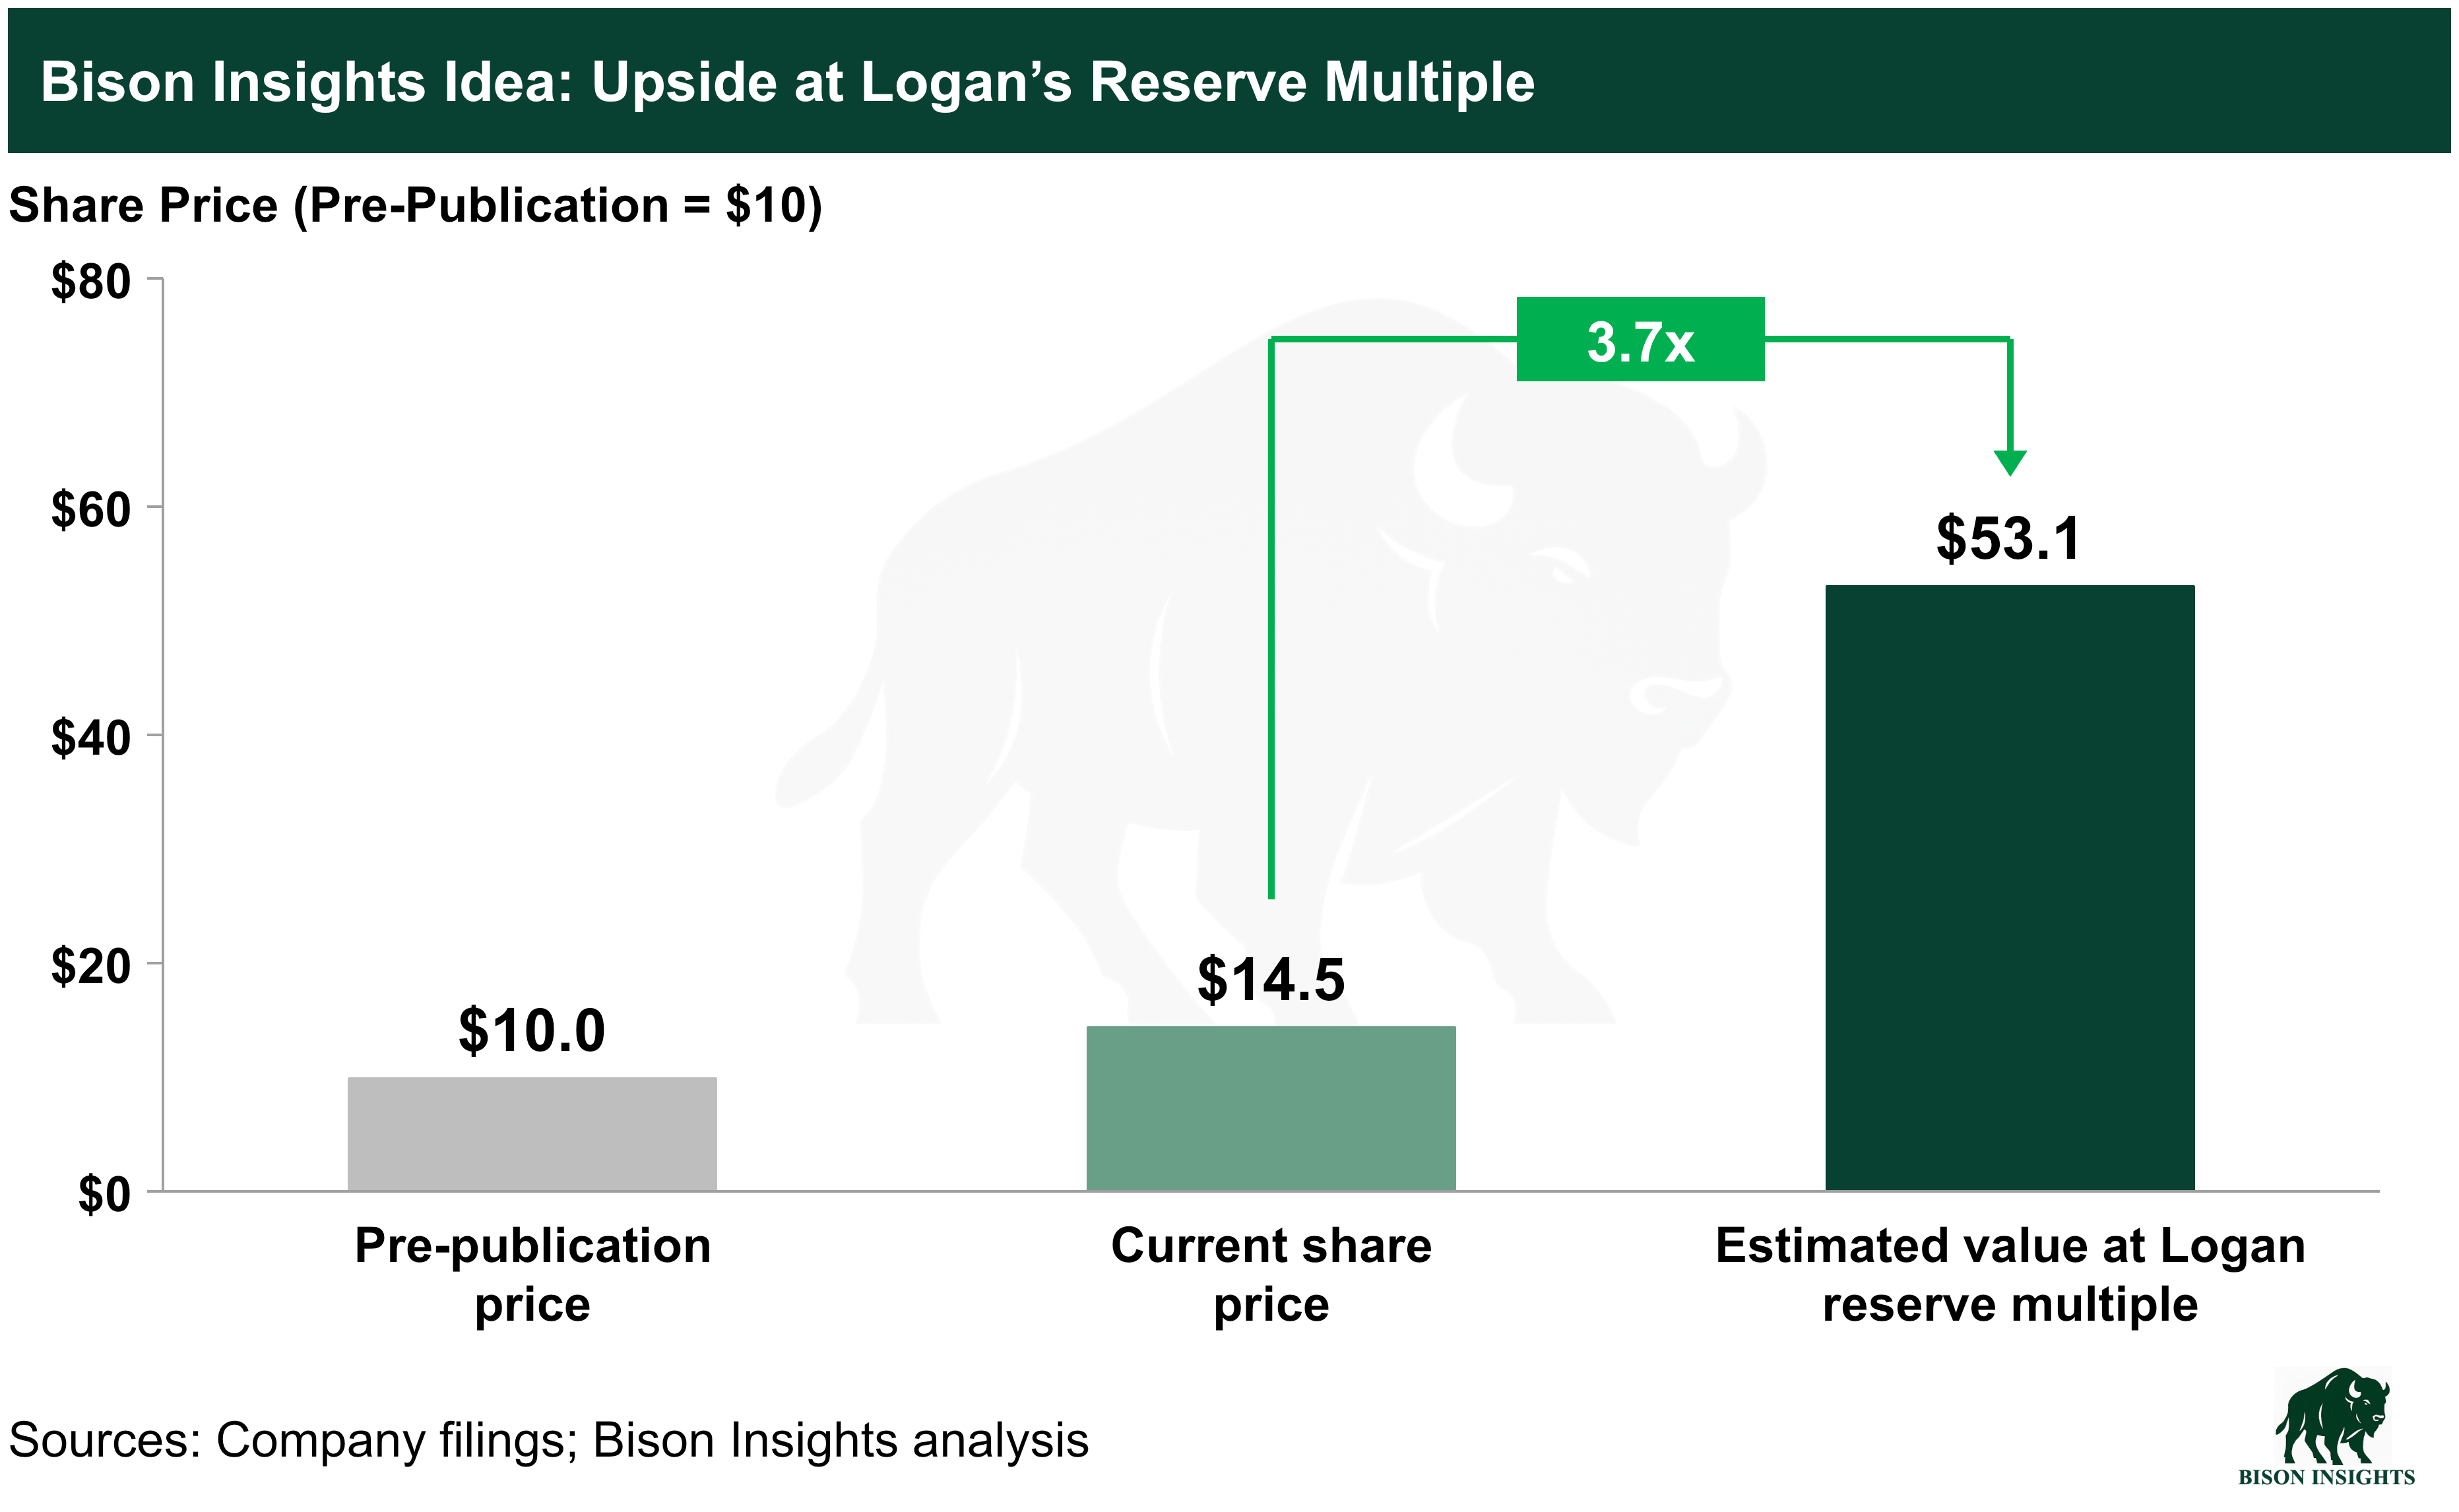
Ovintiv’s C$1.26 billion purchase of Logan Energy at roughly 2x proved reserve value points to further consolidation among Canadian oil…

Entravision’s Q3 ad-tech revenue reached $177.2 million, up 133% year over year, while total revenue rose 88% to $226.3 million and diluted…
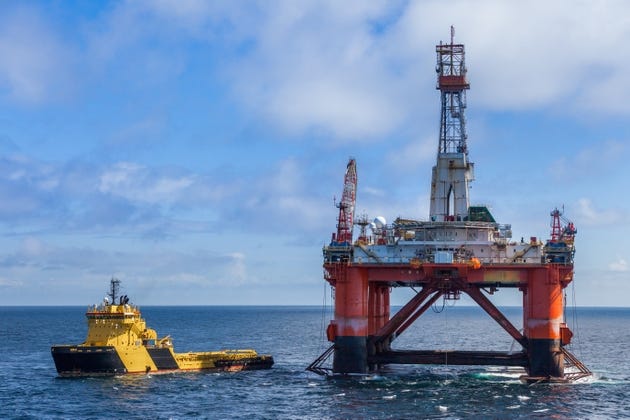
Transocean’s 25.6% selloff reflects oil-market shorting and weak Q3 headlines, while debt reduction after the Valaris acquisition could…
CareCloud rebuilt its sales organization under Christopher Langehaug after 18 months without a sales leader, with a second sales rep…
 NRGV · long
Energy Vault (NRGV) is pitched as a long at about $4 per share, with contracted owned-and-operated projects supporting a $10 to $15 target.
Nomad Foods combines leading European frozen-food brands with a high dividend yield, buybacks and decade-low valuation, while private-label…

Westell’s high-margin segment is positioned to benefit from Verizon 5G upgrades and state broadband deployments funded by the $42.45…
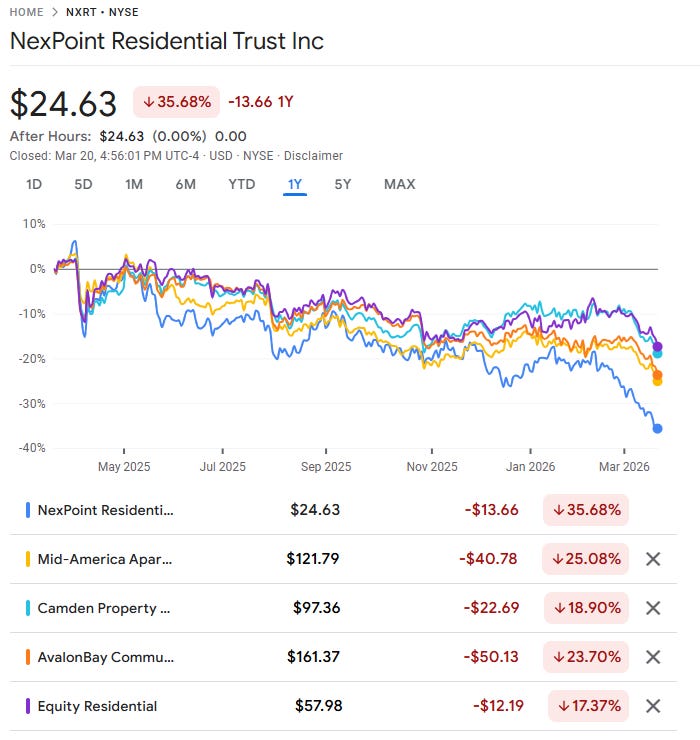
NexPoint Residential is being added despite weak multifamily performance, with insider ownership and a transaction-ready structure…
Solitron Devices' $27.5 million backlog rose 124% year over year as its sole-source military semiconductors support AMRAAM and HIMARS,…
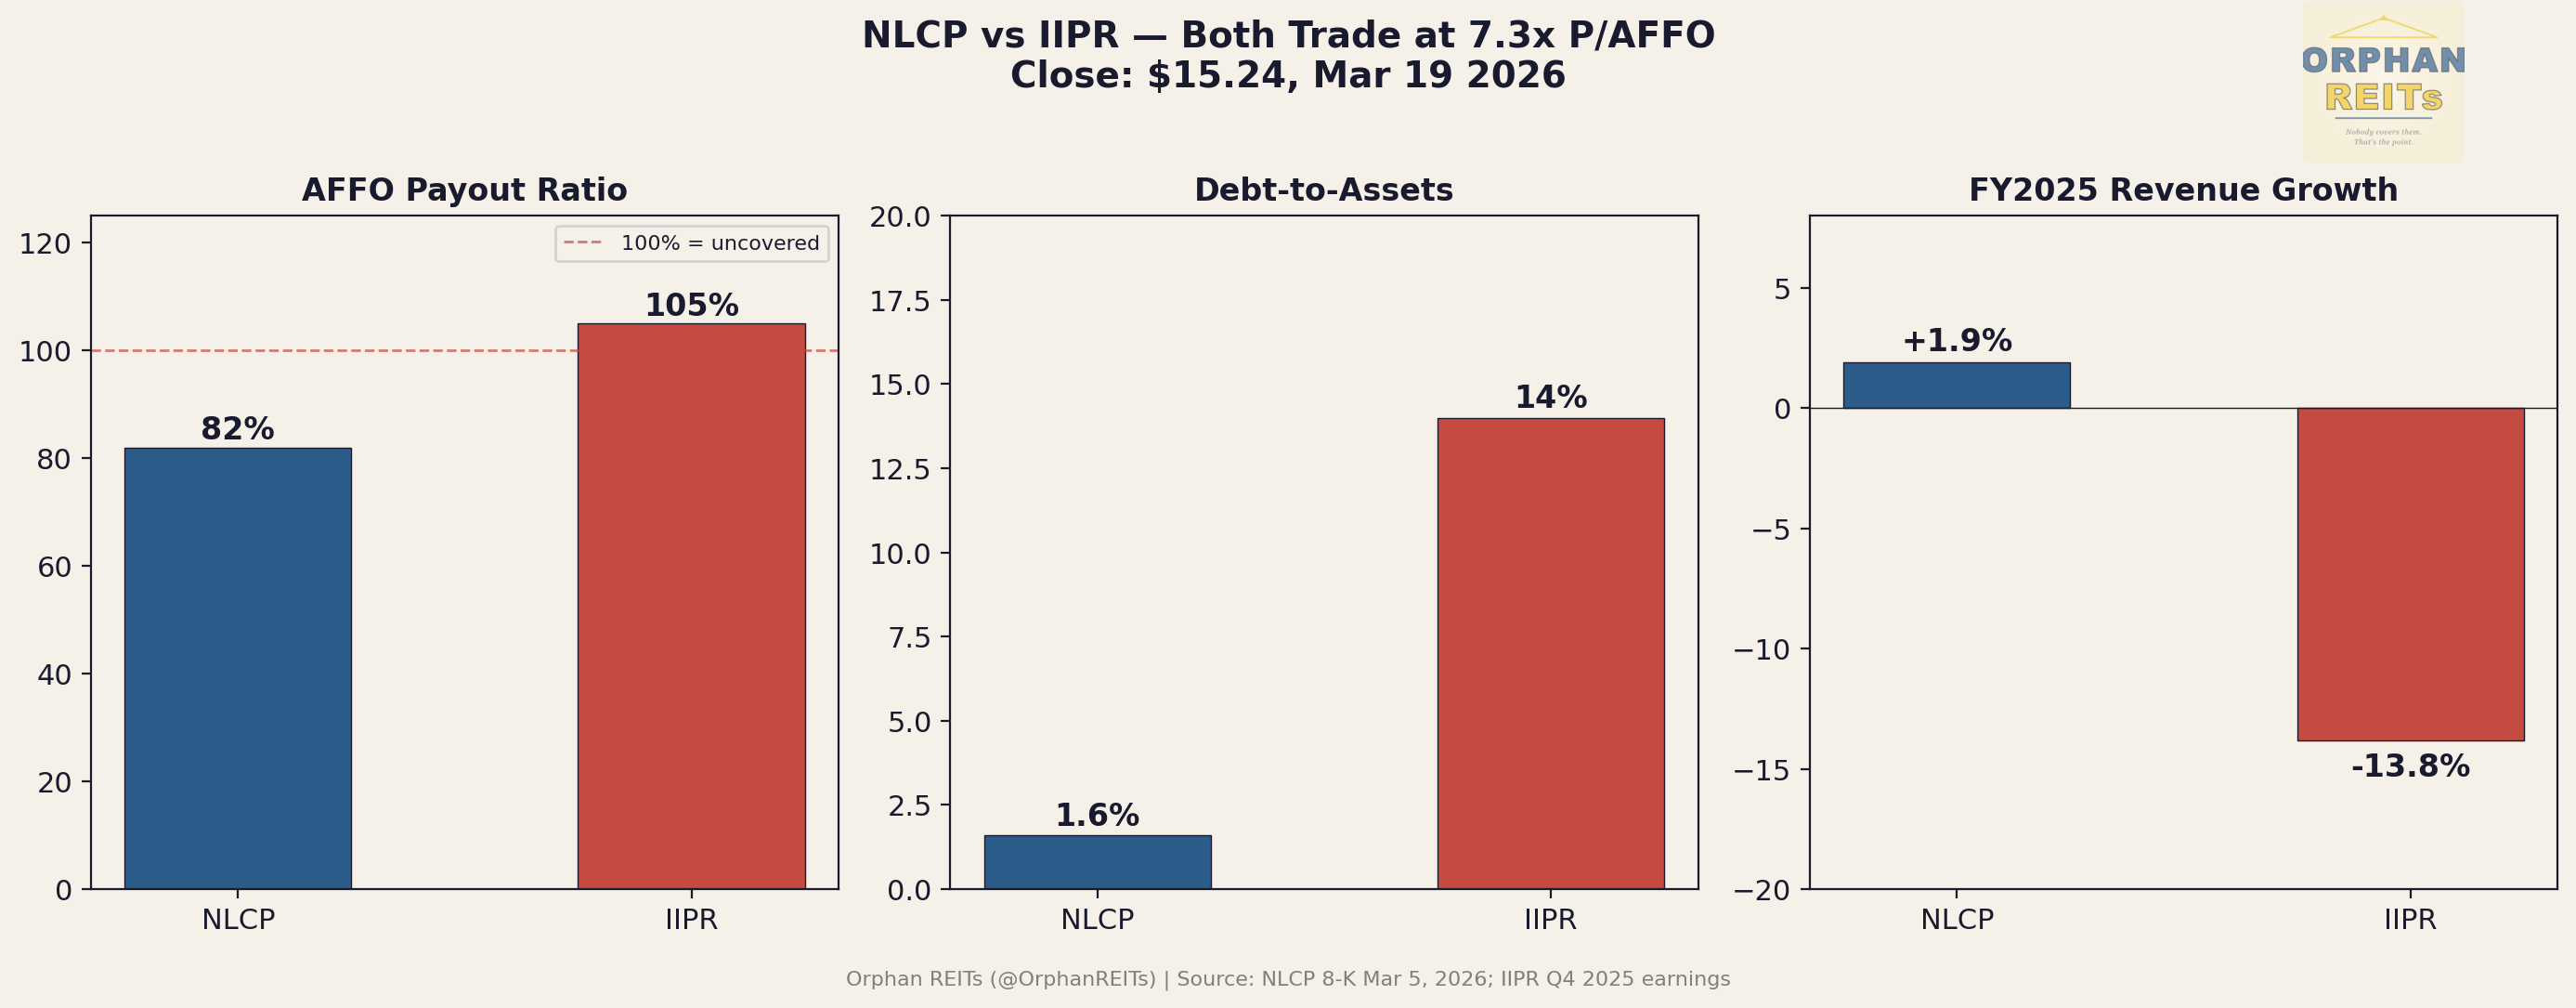
NewLake Capital Partners trades at 7.3x AFFO with $23.9 million cash against $7.6 million debt, discounted for its cannabis tenant base.
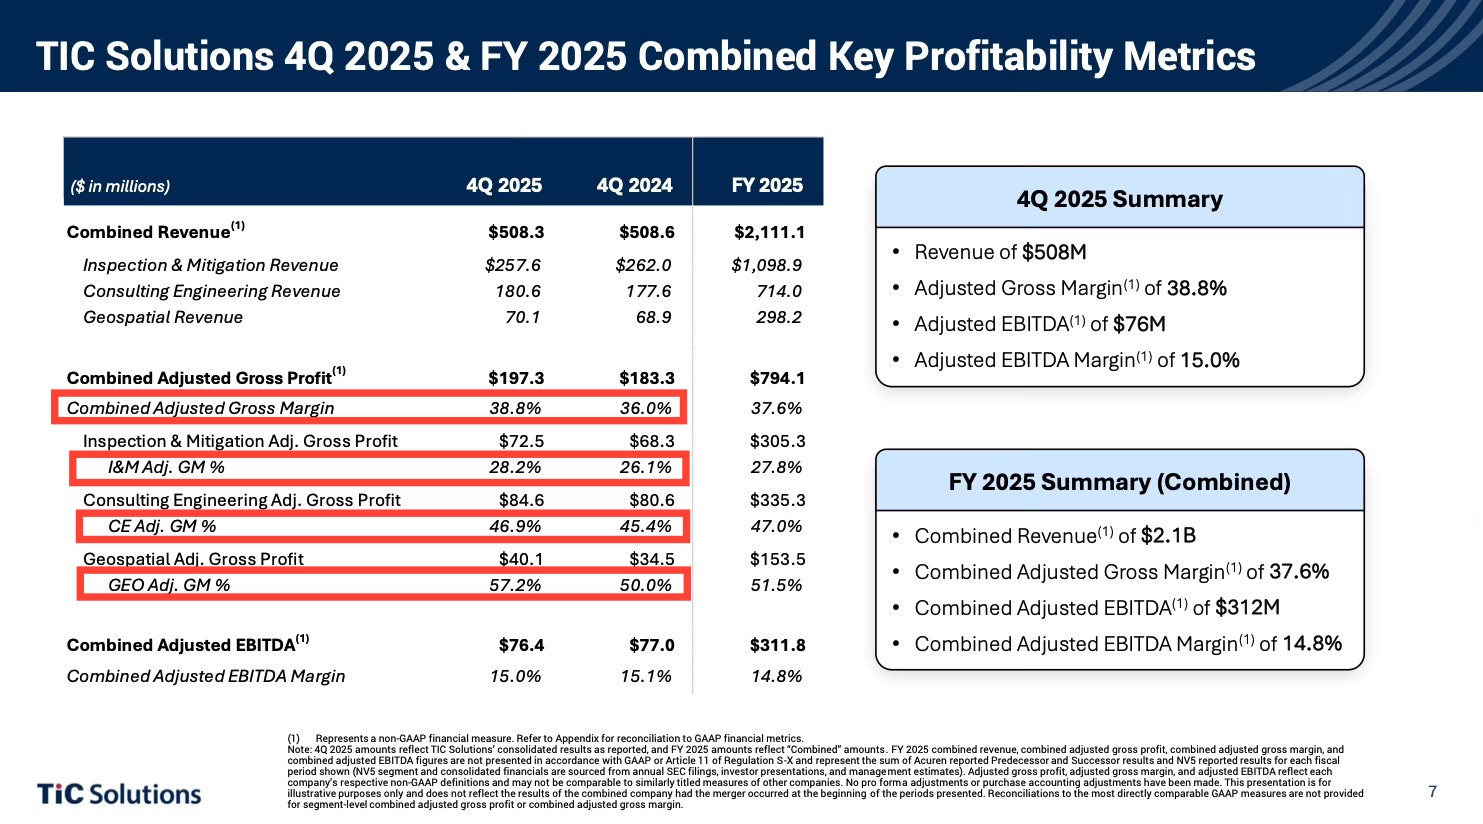
TIC Solutions' NV5 merger lifted consulting and geospatial growth and margins, while its 52%-of-revenue inspection unit stayed flat after…
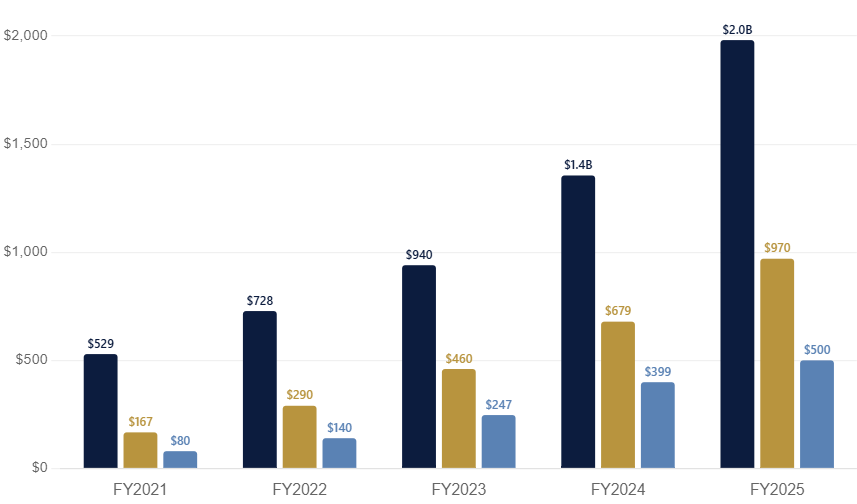
Shift4 Payments earns 50 to 60 basis points on SkyTab volume while acquiring merchant networks, driving 39% annual GRLNF growth since 2021…
Lands’ End’s March 19 results could clarify the WHP IP joint venture, debt paydown and retained stake, supporting a rerating beyond the…
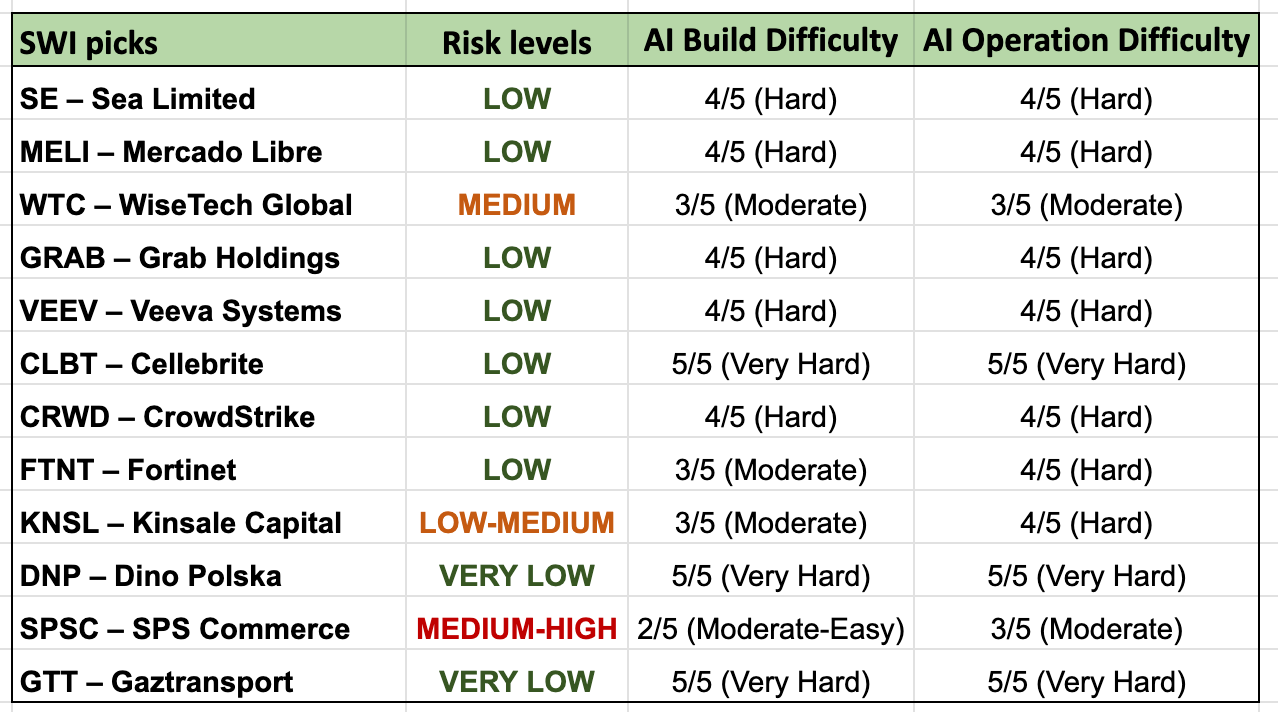
Sleep Well Portfolio is selling SPS Commerce as AI-vulnerable and adding Veeva, Mercado Libre, Cellebrite and Sea, citing proprietary data,…
Every publication on this site, hand-picked.
 Adam Schadt Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Cypriot Invests
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.