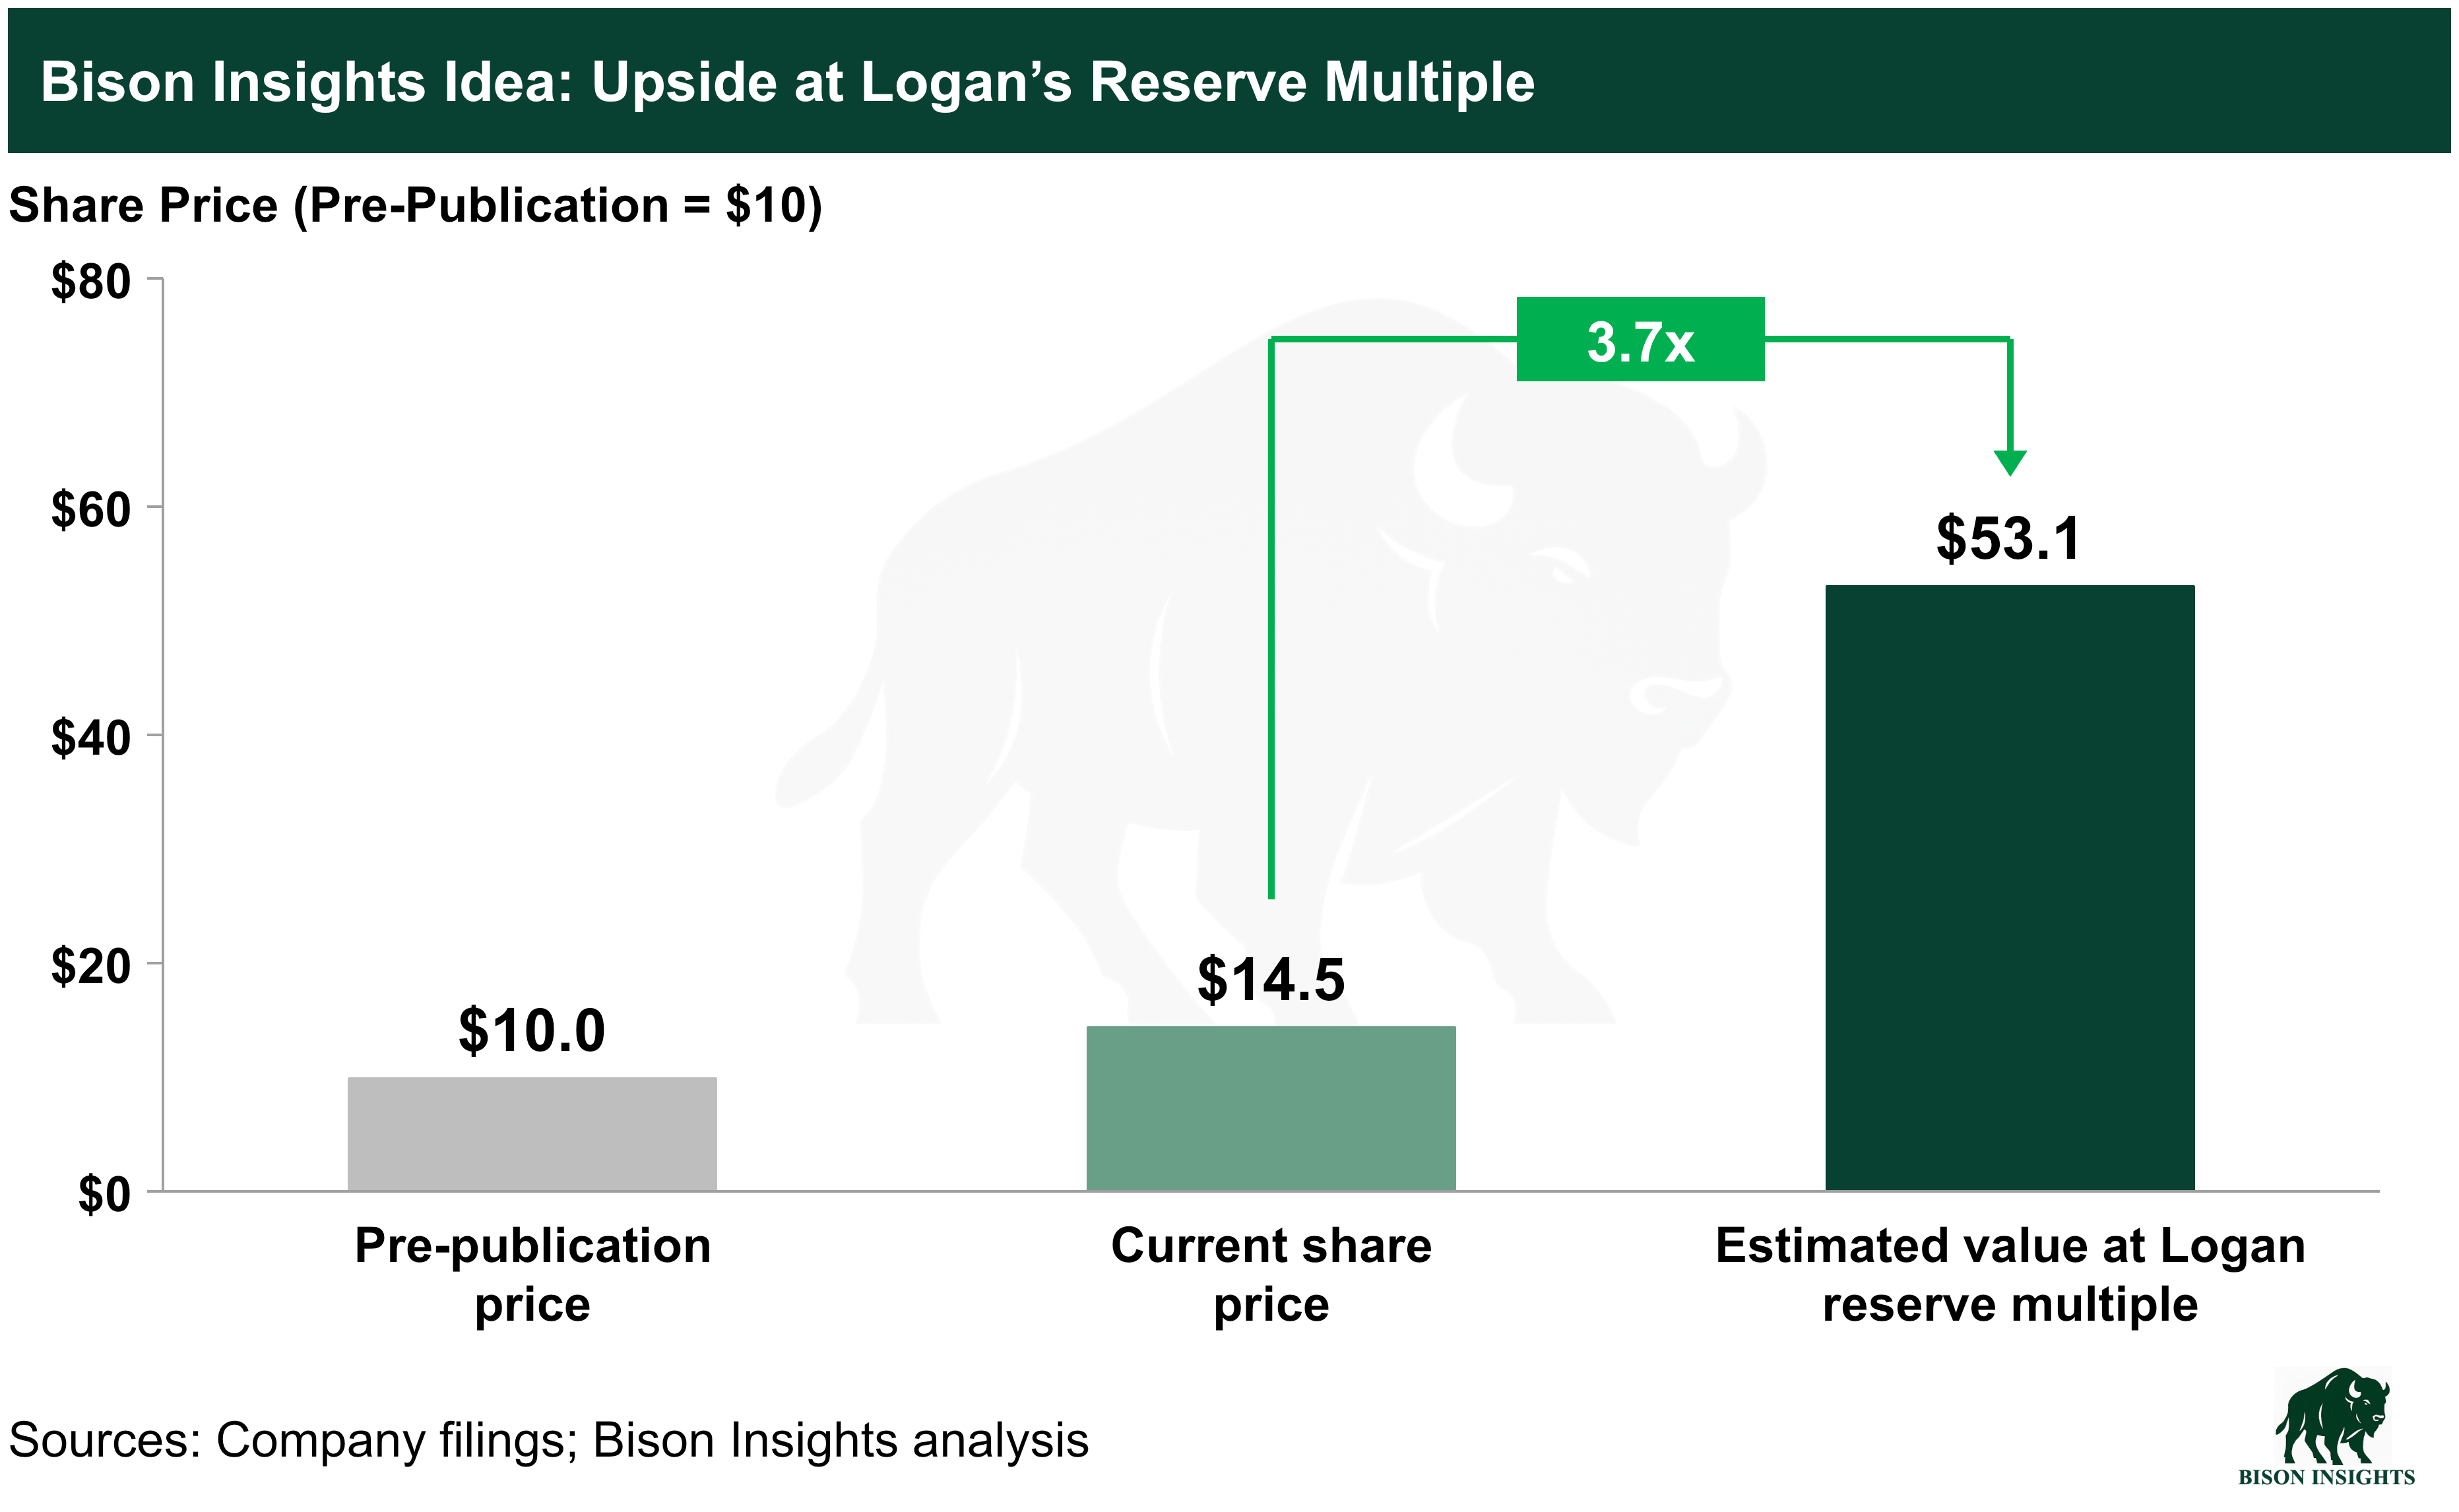
Post Q3 EVC Update
EVC's Q3 update cites $30 million for a single station, a broadcast-business sale and stronger positioning for 2027.
EVC's Q3 update cites $30 million for a single station, a broadcast-business sale and stronger positioning for 2027.
I can not stress enough how $NUAI is an absolute zero now. No chance they land hyperscalers partner on TX. They don’t have much cash either, they were hoping to issue equity at a much higher price.
It's honestly amazing that $ZM is still in business given how awful Zoom is as a product. Then again, when your main competition is Microsoft Teams, I guess you can get away with just about anything.
Sell TV, keep executing, initiate fat buy back, repeat. $EVC https://t.co/dOmr9ZLiTB
Best part of $GPRE earnings call: "As all of our projects compete for capital, from time to time, we expect to be buyers of our own shares as well, and it may be one of the highest cash flow accretive options available" They can repurchase 8% (~5.5M) of the outstanding shares.

Entravision’s Q3 ad-tech revenue reached $177.2 million, up 133% year over year, while total revenue rose 88% to $226.3 million and diluted…
Transocean’s 25.6% selloff reflects oil-market shorting and weak Q3 headlines, while debt reduction after the Valaris acquisition could…
Axon cut full-year guidance after delayed federal Dedrone contracts slowed 3Q revenue growth to 28%, while software and services grew 43%.

Axon’s 3Q26 revenue growth fell to 28% after delayed federal Dedrone contracts, while software grew 43% and its $1.2 billion Skydio…
CareCloud rebuilt its sales organization under Christopher Langehaug after 18 months without a sales leader, with a second sales rep…

Datadog beat Q3 revenue guidance by $52 million, but guided Q4 revenue flat as its largest AI-native customer reduced usage after renewing.
Alpha Metallurgical posted a third consecutive quarterly loss as High Vol A coal margins fell to $14 a ton, while director Kenneth Courtis…
Shift4’s Q3 met guidance, but organic growth is decelerating, management credibility is weakening and leverage reduction remains too slow.
Diversified Energy reported $255.6 million of “true” nine-month free cash flow, while its $1.8 billion Birch acquisition would shift…
Cloudflare’s Q3 revenue rose 39% to $782.5 million, its fastest growth in nearly four years, while a $67.9 million GAAP operating loss and…
Dynatrace reported 17% Q2 revenue growth but flat new ARR and lower profit and free-cash-flow guidance, following its $816 million Arize…
Coherent sells constrained InP capacity through volume-priced modules, while a $20 billion PhotonLink agreement marks its first…
CareCloud’s Q3 revenue rose 9% through acquisitions but fell 8% pro forma; the RCM consolidator targets 25–30% margins by shifting acquired…
Reddit fell 29% after warning that Google search traffic was declining, despite Q3 revenue rising 53%; the bull case rests on communities,…
 Bernard Zambonin 1 click
Marvell’s Lumentum acquisition targets optical networking demand as AI data centers shift from copper to lasers, expanding its hyperscaler…
Blue Owl Capital's NAV rose to $14.32 as buybacks and portfolio marks improved, while OBDC trades at a 25% discount despite a 0.33%…
 Tim Travis 1 click
 AAP · long
Advance Auto Parts, AAP, is presented as a long idea following prior write-ups at $48.81 per share in January 2025.

TransMedics reported record Q3 2026 revenue exceeding $200 million, driven by its organ transplant technology business.
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Cypriot Invests
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.