

Thursday, November 5, 2026
Back to the front page 
From X
Charles Frischer on X
@amuuhasuo $NN Curious how you get to 4 billion valuation. We own almost 14 MHz. I believe Grain is closer to 2 per pop since it is currently 5x5. 14 MHz is 4.5 billion pops. Times 2 is 9 billion or 45 per share.
Kuppy on X
It’s called trade schools, and they’re about to print money as everyone figures this out at the same time. $LINC and $UTI (we’re long) https://t.co/ylEkT81gZ9
Calvin Blissett on X
$OC https://t.co/pA9b0mDR9D https://t.co/Mx02ZpE88d
Charles Frischer on X
@amuuhasuo That is beyond not likely. The way they indicate no would be to do nothing. Let’s face it, SpaceX buying Grain is great comp for $NN. Some days are good for shareholders, some days aren’t. This was a fantastic news day for NN. Throw stones on a bad day, today isn’t that day.
Investor Letters
All letters- Forager Funds Management October 2026 OFX $72MPLT $99M
- FCL Capital October 2026 INTR $1.7BRSGN $876M
- Protean Funds October 2026 AAK $4.7BVIMGF $2.2B
- JB Global Capital Q3 2026 FLO $1.4B
- Pendelhaven Asset Management B.V. Q3 2026 DR0 $417MALM $2.5B
- Chautauqua Capital Management Q3 2026 TMNSF $6.8B
- Night Watch Investment Management Q3 2026 AZLGF $3.3BIMCDY $6.7B
- Greystone Capital third quarter of 2026 KTYCF $461MSRTA $498M


VSH Earnings Review
Vishay reported record Q3 revenue of $979 million, up 24%, and guided Q4 to about $990 million as rising backlog and margins contrast with…
This Week in Special Situations: Lear, AutoNation, NexPoint, AudioCodes, Xponential Fitness
AutoNation, Lear, NexPoint, AudioCodes and Xponential Fitness lead a 52-situation screen spanning buybacks, insider purchases, M&A and…
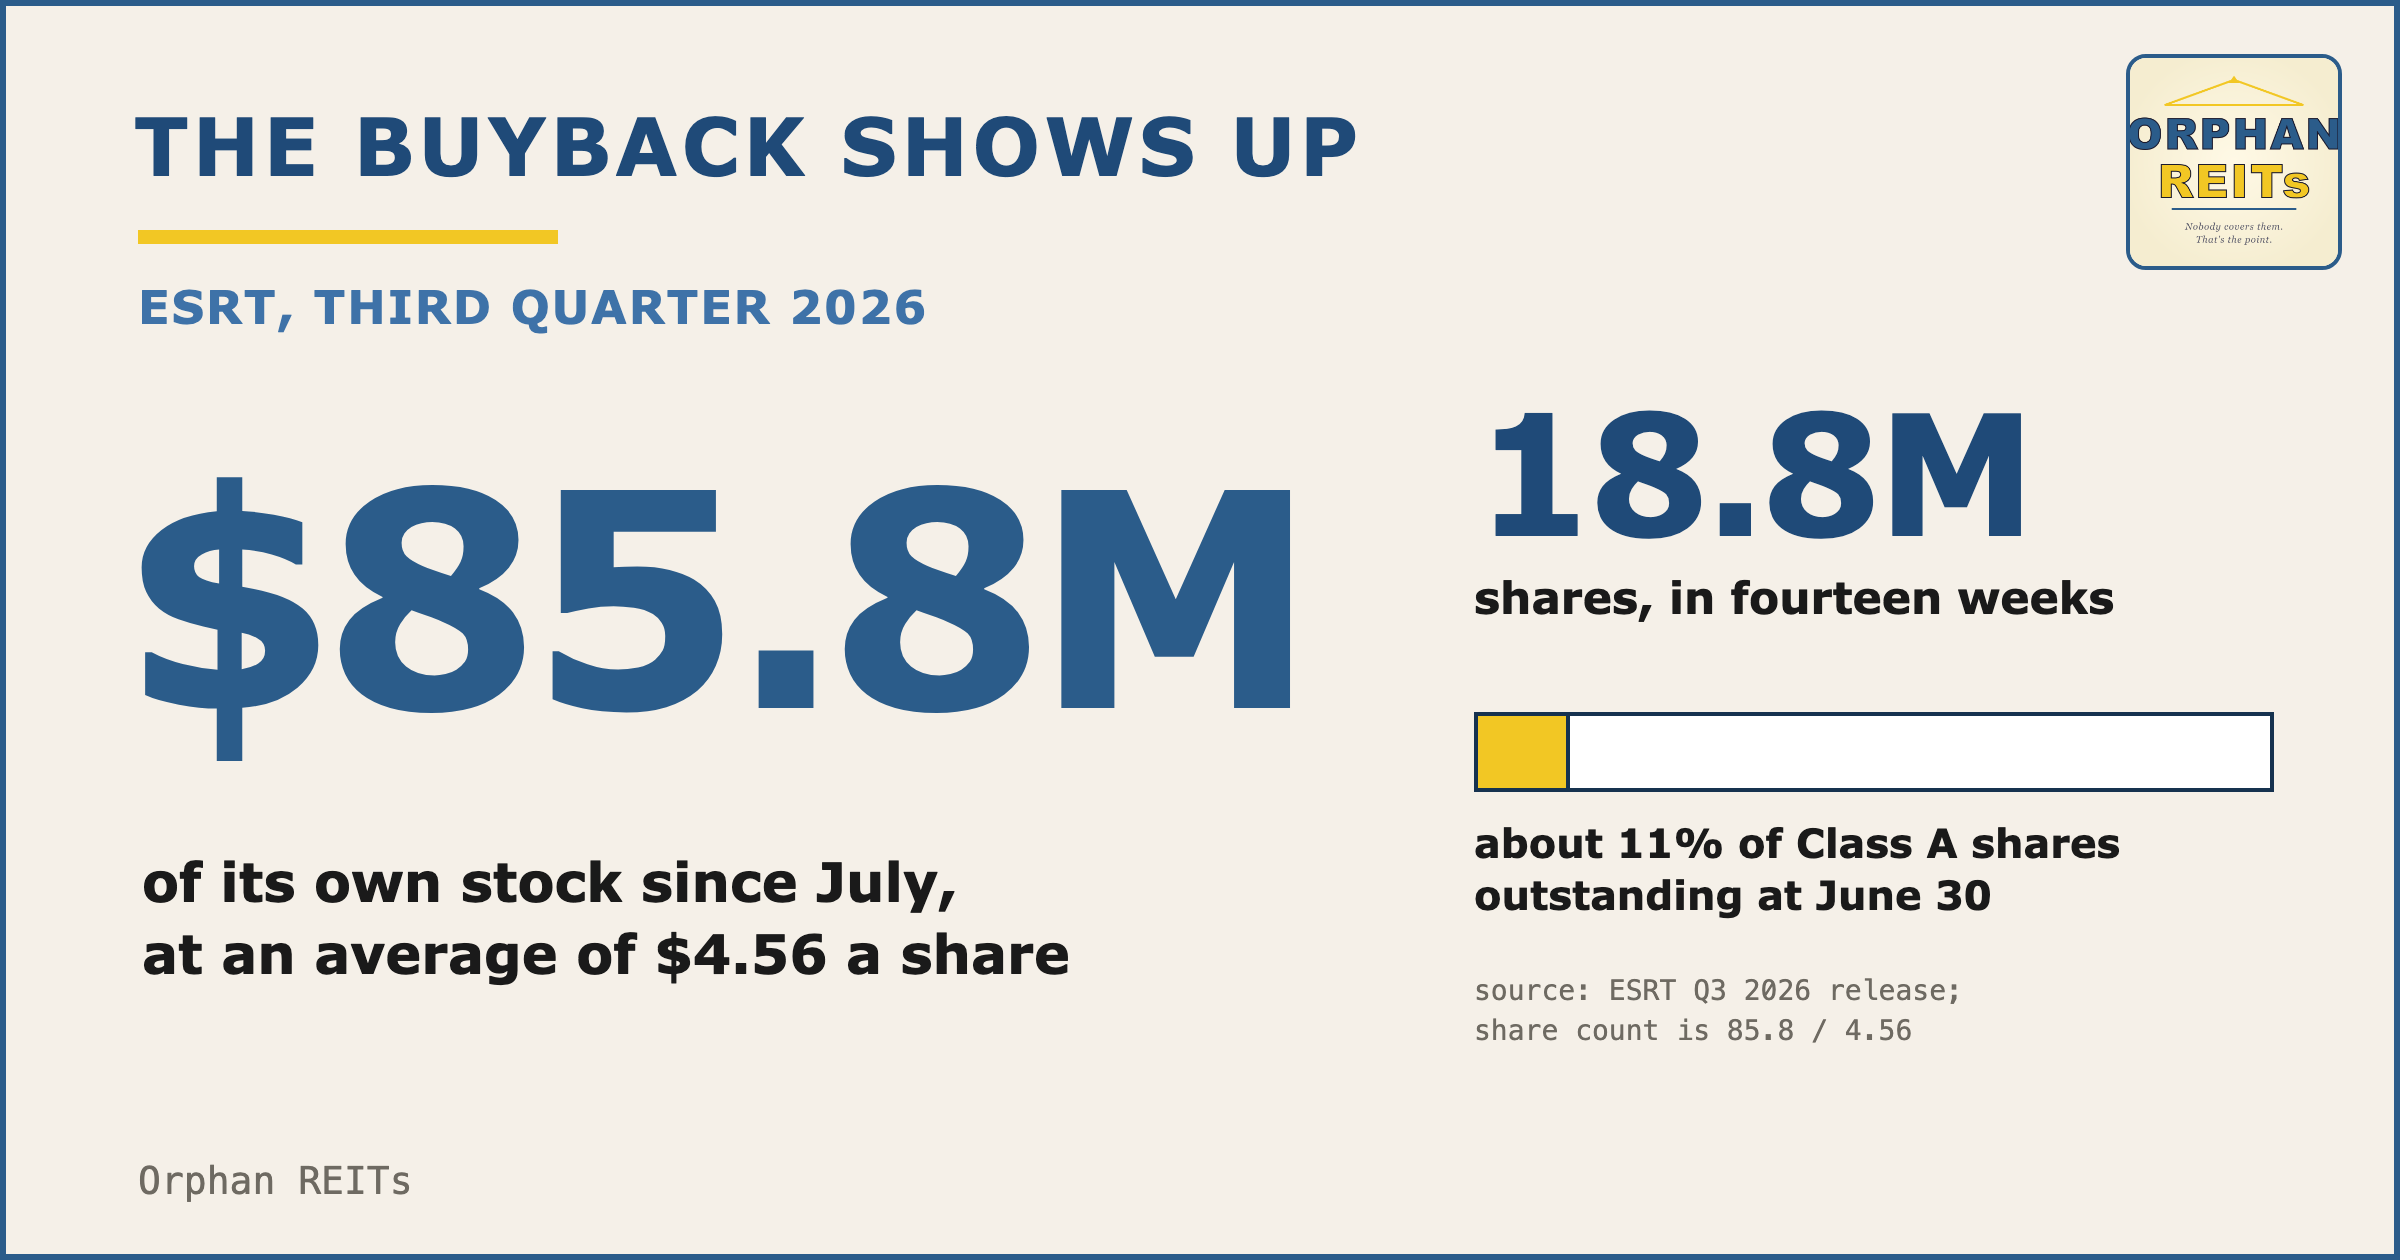
The Buyback Shows Up (ESRT Q3 2026)
Empire State Realty Trust repurchased $85.8 million of shares at $4.56 each, using 1359 Broadway sale proceeds to fund buybacks and debt…
Warrior (HCC): Q3 2026 Earnings
Warrior Met Coal’s Blue Creek mine cut costs to about $93 a ton, offsetting a wider discount for High Vol A coking coal as US supply…
Research Note
Nine Mile Metals is the subject of a research note.
AMSC, Datadog will be fine, SiTime is worth a look
AMSC and Datadog will be fine, while SiTime is worth a closer look.
New Ideas From The Road
Aurelion Research increased healthcare exposure and sees opportunities in banking and defense, alongside research on Alcoa, Nike, ONON and…
Site Centers (NYSE:SITC)
Site Centers' $3 per-share return-of-capital distribution and December delisting leave a discounted liquidation stub, with two properties…

Hedge Fund Manager David Orr Shares His Approach to Investing & Risk Management
David Orr describes running Militia Capital’s roughly 500-stock long-short portfolio, using expected value, correlation and factor…
What AI Bubble? AXT Reports Record Q3 Revenue And Positive Forward Outlook (Rating Downgrade)
AXT reported record Q3 revenue as AI data-center demand for indium phosphide drives supply agreements and capacity expansion.
 Alan Sumler 1 click
 SILC · long
Silicom LTD
Silicom (SILC) is pitched as inexpensive on its existing hardware business, with upside framed as a cheap call option.
Amdocs: The T-Mobile Shock Changes Everything (Rating Downgrade)
 Motti Sapir 2 clicks
Namib Minerals: Research Flash
Namib Minerals accelerates Redwing’s restart, targeting first gold this month and a ramp from 338 ounces monthly to 835 ounces by Q2 2027.
Educational Development (EDUC) – The Book Value Trap
Educational Development trades at 0.21x tangible book after selling its distribution complex to repay debt, but FY26's $2.3m profit masked…
Stevanato down 30%. Yikes.
Stevanato fell 30% after forecasting low-single-digit 2027 growth as lower Nexa syringe volumes from a GLP-1 customer offset solid Q3…
Transocean (RIG): Q3 2026 Earnings
Transocean enters its Valaris merger with 109 of 110 available deepwater rigs contracted and 313 million shares sold short, despite weaker…
Blackstone Digital Infrastructure Trust (NYSE: BXDC)
BXDC trades at a 14% discount to net liquidation value, with $1.9 billion of cash against a $1.6 billion market cap, ahead of data-center…
Why Essential Properties Realty Trust Keeps Winning
Essential Properties Realty Trust is growing faster than Realty Income through acquisition opportunities while trading at a cheaper…
 Jussi Askola, CFA
48 Top Stock Pitches (26th-1st November) [NO PAYWALL] 🖨️
Capital Employed rounds up 48 stock pitches, led by Greystone’s $14.50 target for organ-transplant logistics firm Strata Critical Medical,…
Initiation Report
Nine Mile Metals is initiated under research coverage.
Publications we follow
Every publication on this site, hand-picked.
Newsletters 109
- 310 Value’s Newsletter
- Absurdly Cheap Stocks
- Altay Capital - Mostly Value Investing
- AmsterdamStocks
- Asian Century Stocks
- Aurelion Research
- Base Hit Investing
- Bearhold Research
- Bearstone
- Behind the Balance Sheet
- Best Anchor Stocks
- Bilbel's Substack
- Bison Insights
- Brevarthan Research
- Bristlemoon Capital
- Byron Street Research
- Calvin Blissett
- Cannibal Stocks
- Capital Employed
- Capitalist Letters
- Cassandra Unchained
- Chipstrat
- Citrini Research
- Cluseau Research
- CV's Substack
- D Invests
- Daniel Romero
- Deep Value Insights
- Dismissed & Asset-Backed
- Doomberg
- Eagle Point Capital
- Easy Value
- Emerging Moats Research
- Exploring with Alluvial Capital
- Ezra's Notes
- Fabricated Knowledge
- First Strike Research
- Flyover Stocks
- Global Outperformers
- Guardian Research
- Hated Moats
- Hayden Capital
- Healthy Stock Picks
- HFI Research
- Hidden Gems Investing
- Hidden Rock Capital's Newsletter
- Ian’s Insider Corner
- Iggy on Investing Newsletter
- Inglenook Growth
- Invariant
- Invested Capital
- Investing 501
- Irrational Analysis
- Jimmy's Journal
- John Hempton's Newsletter
- Kairos Research
- Kakashii's Materials
- Key Context by Tae Kim
- Latticework by MOI Global
- Lewistown Capital
- Librarian Capital's Research Library
- Maius Partners
- MBI Deep Dives
- Mispriced Assets
- Modern Value Investing
- Monte Independent Investment Research
- Multibagger Monitor
- Nat Stewart - Stock Picking Newsletter
- Net Interest
- Nongaap Investing
- Nugget Capital Partner's Substack
- Open Insights
- Orphan REITs
- Overlooked Alpha
- P Equity Research
- PETITION
- Phynvesting
- Raging Bull Investments
- Real Assets, Real Value
- Rebound Capital
- Rod’s Ruminations
- ROE The Boat
- scuttleblurb
- Sector Stories
- SemiAnalysis
- Shallow Dives
- Singularity Research
- SixSigmaCapital: Navigating the Financial Markets
- Sleep Well Investments
- Speedwell Memos
- Stock Thoughts
- Substack von Philipp
- Sunday's Idea Brunch
- Sylence Capital
- The Curious Compounder
- The Mikro Kap
- The Oak Bloke
- The Rational Walk
- The Value Road
- Trade Ideas Flow
- Treasure Hunting
- Triple S Special Situations Investing
- TSOH Investment Research
- Underlying Value
- Value Don't Lie
- Vik's Newsletter
- WHAT ARE WE DOING? “Contrarians At The Gate”
- XIX Value
- Yet Another Value Blog
Blogs 15
- Atrium Research - Equity Research
- Bireme Capital - Investor Letters
- Cestrian Capital Research
- Choice Equities Capital Management
- Clark Street Value
- Crossroads Capital | Research-driven, Value-centric
- Hunterbrook
- Kerrisdale Capital
- NoNameStocks
- Raging Capital
- Speedwell Research
- Stratechery by Ben Thompson – On the business, strategy, and impact of technology.
- The Technology Letter
- Undervalued Shares
- Value Investors Club
Seeking Alpha 74 of 278
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Cypriot Invests
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
- Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
X accounts we follow
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
- RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Investor letters we follow
- 1 Main Capital
- 103 Advisory Group
- 1290 Funds
- 13D Activist Fund
- 1851 Capital
- 49 Financial
- ABS Global Investments
- ACATIS Investment
- Aberdeen Investments
- Accelerate Financial Technologies
- Advisors Capital Management
- Advisory Research
- Aegis Value Fund
- Aikya Investment Management
- Akre Capital Management, LLC
- Allspring Global Investments
- Alluvial Capital Management
- Alpha Wealth Funds
- Alpine Capital Research
- Alpinum Investment Management AG
- Amati Global Investors
- Amber River
- Andrew Hill Investment Advisors
- Andvari Associates
- Angel Oak Capital Advisors
- Aoris Investment Management — Aoris International Fund
- Appalaches Capital
- Ariel Investments
- Aristotle Funds
- Artisan Partners
- Askeladden Capital
- Asset Value Investors Ltd
- Atai Capital Management
- Atherean Asset Management
- Auxier Asset Management
- Avenue Investment Management
- Azvalor Asset Management
- BBH
- BNY Mellon
- Bahl & Gaynor
- Bailard
- Baird Equity Asset Management
- Barometer Capital Management
- Baron Funds
- Bell Asset Management
- Bengal Capital
- Berkshire Hathaway
- Bestinver
- Biglari Holdings
- Bilbel Capital
- Biondo Investment Advisors
- Bireme Capital
- Bison Interests
- BlackRock
- Blue Tower Asset Management
- Brandes Investment Partners
- Brasada Capital
- Bretton Fund
- Brighton Jones
- Bristlemoon Capital
- Broadleaf Partners
- Brookfield Asset Management
- Brown Advisory — Large-Cap Growth
- Brown Advisory — Mid-Cap Growth
- Broyhill Asset Management
- Brummer & Partners
- Burke Wealth Management
- ByteTree
- Cambiar Investors
- Cantor Fitzgerald Asset Management
- Carillon Eagle — Mid Cap Growth Fund
- Carillon Eagle — Small Cap Growth Fund
- Carrington Wealth Management
- Castlebay Investment Partners
- Cedar Creek Partners
- Cedar Grove Capital Management
- Chautauqua Capital Management
- Chenavari Investment Managers
- Chevy Chase Trust
- Chilton Capital Management
- Choice Equities
- City Different Investments
- Claret Asset Management
- ClearBridge Investments
- Compound Everyday Capital
- Comus Investment
- Conestoga Capital Advisors
- Confluence Investment Management
- Cooper Investors
- CrossingBridge Advisors
- Crossroads Capital, LLC
- Crypto Native Capital
- Curreen Capital
- Davenport Asset Management
- Davis Advisors Global ADR
- Davis Advisors Large Cap Value
- Davis Opportunity Fund
- Davis Real Estate Fund
- Diamond Hill — Large Cap Fund
- Diamond Hill — Small Cap Fund
- Diranko Capital
- Distillate Capital
- Dodge & Cox Stock Fund
- Donville Kent Asset Management Inc.
- DoubleLine
- Downing
- East 72
- East Capital
- Easterly Asset Management
- EdgePoint Wealth Management
- Elm Ridge Management
- Emerald Wealth Partners
- Emeth Value Capital
- Equity Management Associates
- Evolve Private Wealth
- FCL Capital
- FPA Crescent Fund
- Fairfax Financial Holdings
- Fairlight Capital
- Fairtree Asset Management
- Fawkes Capital Management
- Fenimore Asset Management
- Fiduciary Management
- Fiera Capital
- Financial Synergies Wealth Advisors
- First Eagle Investments
- Focus Capital Management
- Forager Funds Management
- Frank Capital Partners
- Fred Alger Management, LLC
- GCQ Funds Management
- GDS Investments
- GROW Funds
- Gabelli Funds
- Generation Investment Management
- Giverny Capital
- Glass Lake Wealth Management
- Glenmede Investment Management
- GoodHaven Capital Management
- Grandeur Peak Global Advisors
- GreenWood Investors
- Greenhaven Road Capital
- GreensKeeper Asset Management
- Greenwood Gearhart
- Gresham House
- Gresham House Strategic Equity Capital
- Grey Owl Capital Management
- Greystone Capital
- Guinness Global Investors
- HORAN Wealth
- Halvio Capital
- Harding Loevner
- Hardman Johnston
- Harry Qelm Baabsman
- Hayden Capital
- Heartland Advisors
- Hennessy Funds
- Heptagon Capital Future Trends Equity Fund
- Heptagon Capital Kettle Hill US L/S Equity Fund
- Highwood Value Partners
- Hinde Group
- Hoisington Investment Management
- Holland Advisors
- Hood River Capital Management
- Horizon Kinetics
- Horos Asset Management
- Hosking Partners
- Hotchkis & Wiley
- Impax Asset Management
- Infuse Asset Management
- Integrity Asset Management — Micro Cap Value Equity
- Intrepid Capital
- Invenomic Capital Management
- Invesco — Discovery Fund
- Ironvine Capital Partners
- Ithaka Group — US Growth Strategy
- JB Global Capital
- JM Finn
- Jacob Asset Management
- Janus Henderson Investors
- Jemekk Capital Management
- Jenga Investment Partners
- Kathmandu Capital
- Kaydan Wealth Management
- Kennedy Capital Management
- Kernow Asset Management
- Kingdom Capital Advisors
- LVS Advisory
- Lakehouse Capital Global Growth Fund
- Lakehouse Capital Small Companies Fund
- Langdon Equity Partners
- Lansing Street Advisors
- Latitude Investment Management
- Laughing Water Capital
- Lazard Asset Management
- Leonard Rickey Investment Advisors
- Lindsell Train Limited
- Long Cast Advisers
- Loomis Sayles — Global Growth Fund
- Lyrical Asset Management
- MJG Capital
- Madison Investments — Small Cap Fund
- Mairs & Power
- Manole Capital Management
- Mar Vista Investment Partners
- Maran Capital Management
- Markel Group
- Marram Investment Management
- Massif Capital
- Matrix Asset Advisors
- Matthews Asia
- Mayar Capital
- McIntyre Partnerships
- Meridian Growth Fund
- Meridian Hedged Equity Fund
- Merion Road Capital
- Miller Value Partners
- Miller/Howard Investments
- Minot Light Capital Partners
- Minotaur Capital
- Moerus Capital Management
- Mondrian Investment Partners
- Moneta Group
- Montaka Global Investments
- Moon Capital Management
- Mott Capital Management
- Mountain Vista Wealth Management
- Muhlenkamp & Company
- Munro Partners
- Myrmikan Capital, LLC
- NS Partners
- Nelnet
- Newport Capital Group
- Next Century Growth Investors
- Night Watch Investment Management
- Nightview Capital
- Nixon Capital
- North Sky Capital
- O'Keefe Stevens Advisory
- Oak Associates Funds
- Oak Ridge Investments
- Oakmark Funds
- Oceana Investimentos
- Oldfield Partners
- Open Insights Capital
- Ophir Asset Management
- Optimist Fund
- Orange Investment Advisors
- Oujo Wealth Strategies
- Overseas Asset Management Asian Recovery Fund
- Overseas Asset Management European Value Fund
- PM Capital
- Packer & Co
- Palm Harbour Capital
- Palm Valley Capital
- Parnassus Investments
- Patient Capital Management
- Peak Asset Management
- Peapack Private
- Pendelhaven Asset Management B.V.
- PenderFund Capital Management Ltd.
- Penn Davis McFarland
- Pershing Square Holdings
- Pittenger & Anderson
- Plural Investing
- Polaris Capital Management
- Polen Capital 5Perspectives Growth Opportunities
- Polen Capital U.S. Opportunistic High Yield
- Praetorian Capital
- Private Capital Management
- ProChain Capital
- Protean Funds
- Pzena Investment Management
- QV Investors
- QuantStreet Capital
- Quercus Fund
- RD Capital Partners
- REQ Capital
- RF Capital Management
- RGA Investment Advisors
- ROCKLINC Investment Partners
- Rathbones
- Regal Partners Global Investments
- Regency Wealth Management
- Renaissance Investment Management — Large Cap Growth
- Rewey Asset Management
- Right Tail Capital
- RiverPark Funds
- Riverwater Partners
- Robinson Capital Management
- Rowan Street Capital
- Royce Investment Partners
- Rozendal Partners
- SRK Capital
- Saga Partners
- SaltLight Capital
- Sandon Capital — Activist Fund
- Sands Capital — Select Growth Fund
- Sawgrass Asset Management
- Seafarer Capital Partners
- Sequoia Fund
- Seven Corners Capital
- Sharp Capital
- Shelton Capital Management
- Sigil
- Signia Capital Management
- Skybound Wealth Management
- Smead Capital Management
- Social Capital
- Sorfis Investments
- Sound Shore Management
- Southeastern Asset Management
- SouthernSun Asset Management
- Sparrow Wealth Management
- Spheria — Global Smaller Companies Fund
- Spyglass Capital Management
- Starvine Capital
- Stenham Asset Management
- Stewart Asset Management
- Steyn Capital
- Stone Ridge Asset Management
- Stone Sentinel Capital
- Stonehearth Capital Management
- Summers Value Partners
- Sustainable Growth Advisers
- TEAM Asset Management
- TIFF Investment Management
- Tall Oak Capital Advisors
- Tapasya Investment
- The London Company
- Third Avenue Management
- Third Point
- TimesSquare Capital Management
- Touchstone — Balanced Fund
- Troy Asset Management
- Tweedy, Browne
- Unconventional Value
- Upslope Capital Management
- VH Standard Asset Management
- Value Line Funds
- Victory Capital — Sycamore Mid Cap Value Equity
- Vision Capital Fund
- Vltava Fund
- Voss Capital
- Voya Investment Management — MI Dynamic Small Cap Fund
- Vulcan Value Partners
- Warden Capital
- Wasatch Global Investors — Micro Cap Fund
- Wasatch Global Investors — Small Cap Growth Strategy
- Wealthspire Advisors
- Wedgewood Partners
- Weitz Investment Management
- Wellington Management — Quarterly Market Review
- WestEnd Capital Management
- Westfield Capital Management
- Westwood — Quality SmallCap Fund
- White Brook Capital
- White Falcon Capital Management
- YCG Investments
Sectors
Ordered by how often our editor reaches for them.
