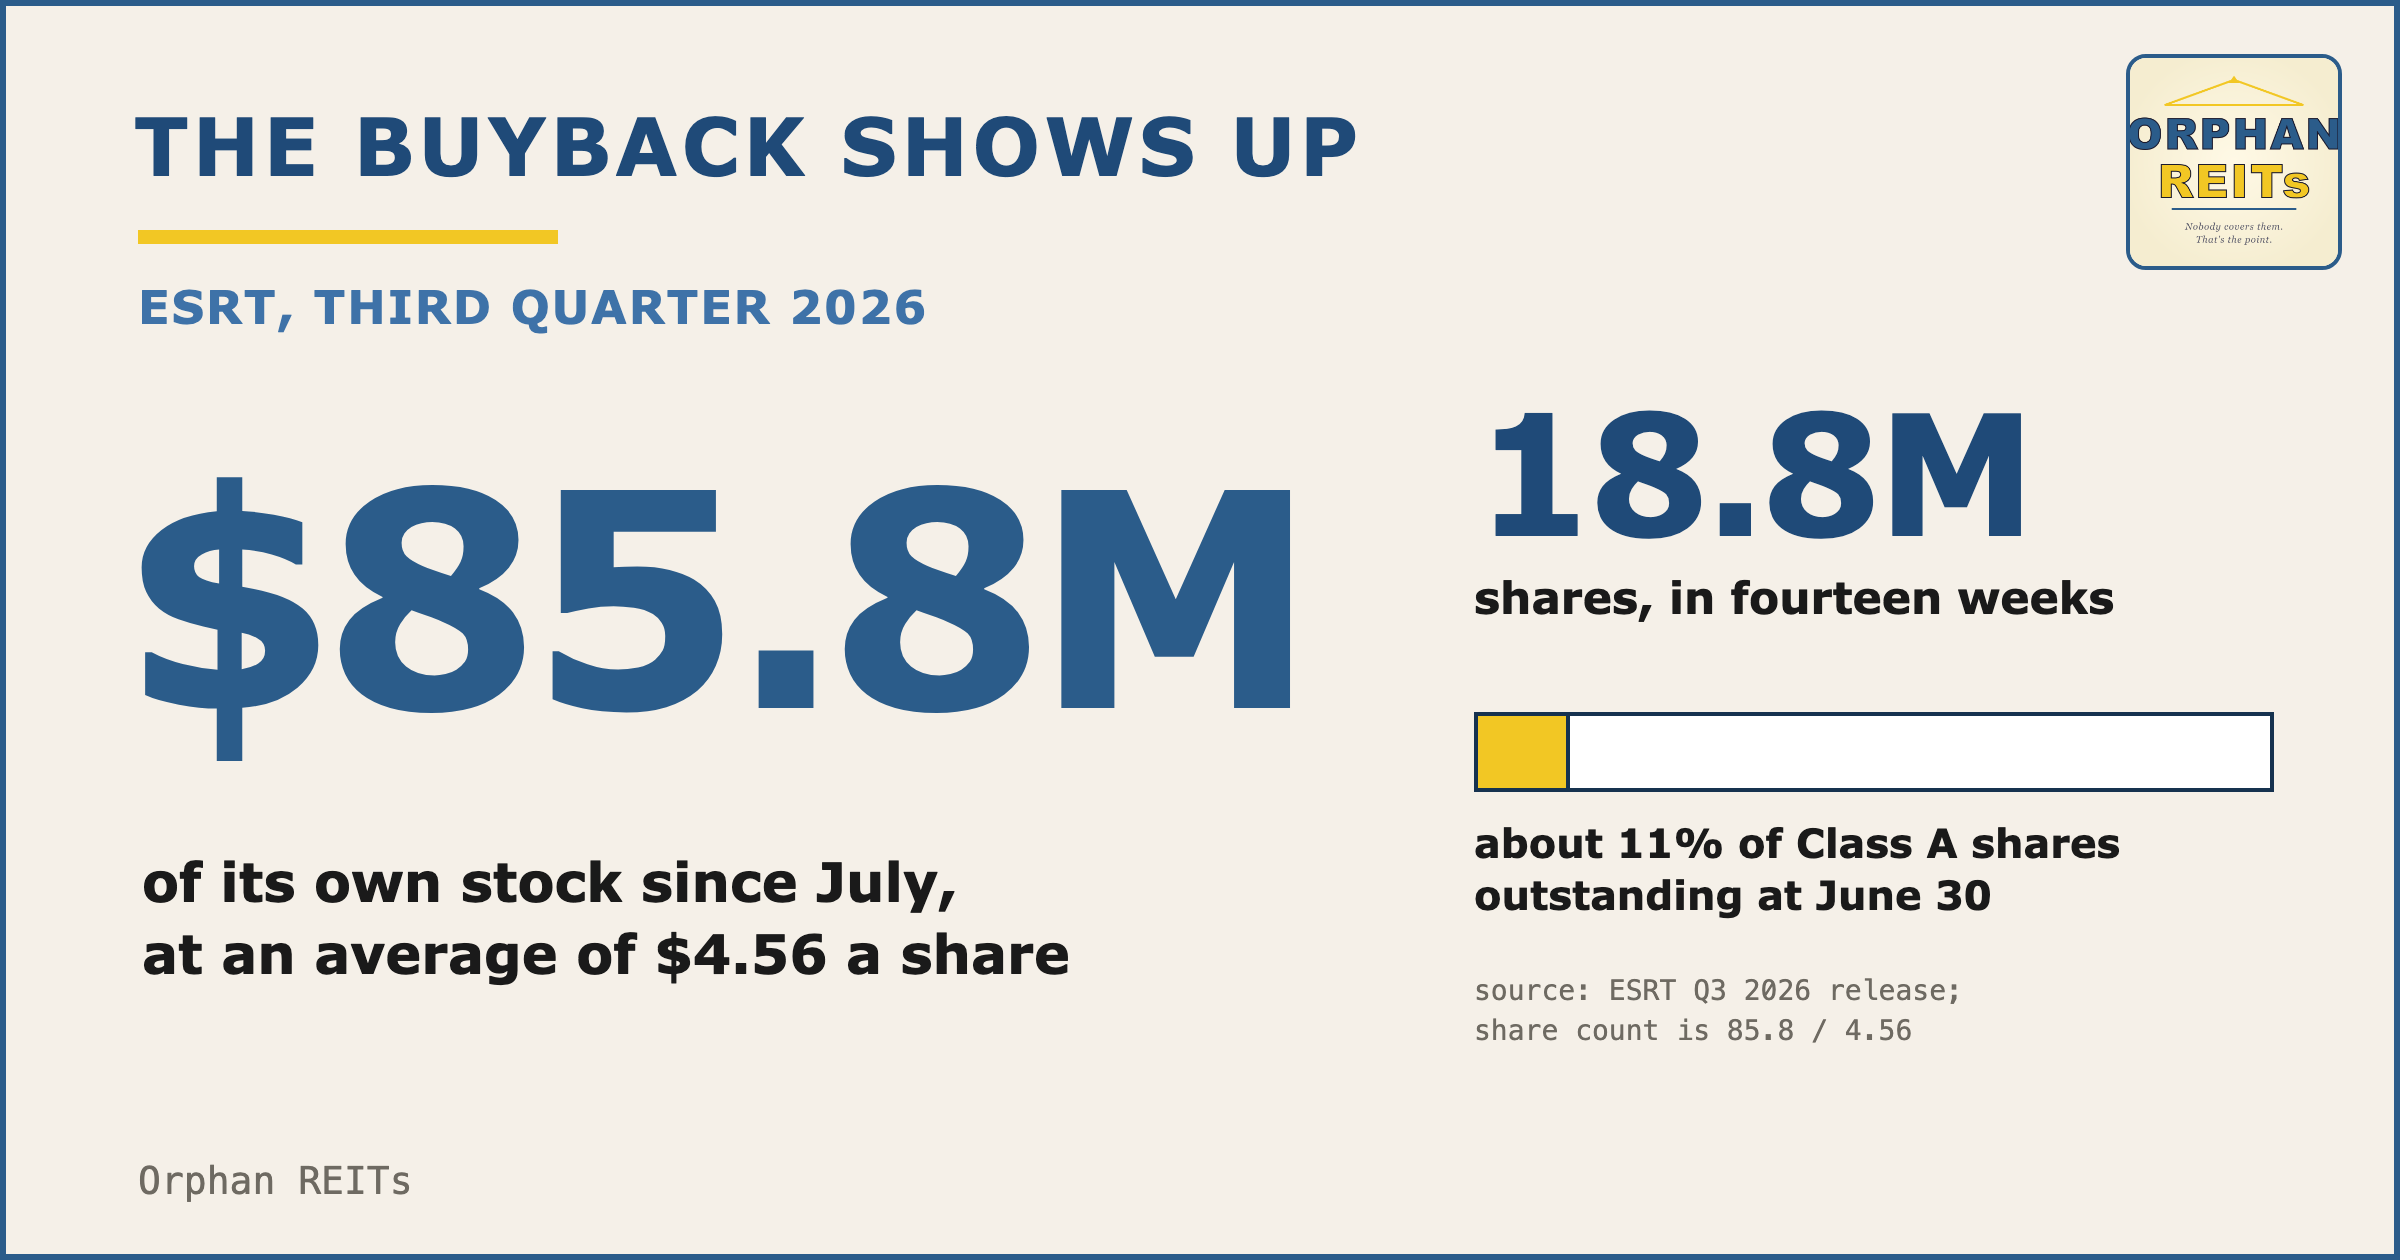
The Buyback Shows Up (ESRT Q3 2026)
Empire State Realty Trust repurchased $85.8 million of shares at $4.56 each, using 1359 Broadway sale proceeds to fund buybacks and debt reduction.
Empire State Realty Trust repurchased $85.8 million of shares at $4.56 each, using 1359 Broadway sale proceeds to fund buybacks and debt reduction.
Bullish china. $GDS and $VNET the two US listed Chinese Data centers were trading at their lows --- likely to benefit if we let china Win AI https://t.co/Tp9F9ADC7H
Blue Owl's Tech BDC ($OTF) just posted Q3. NAV surprisingly increased, helped by $55mm of buybacks. Good on them for the conviction Meanwhile, non-accruals at cost 3x'd (0.6% to 1.8%). At fair value, they went from 0.1% to 1.1%. NII still doesn't cover the base dividend Management calls this a “strong” quarter though
$WU longs -- you hoping for $IMXI deal to close or fall apart? I don't have a strong view. Small long for me rn.
@mkfilko I will hold onto my pants until then. Worst case if you get laid off at mcd and $brun disappoints i have room in my closet 👍🏽🐵
@rubicon59 $APP structurally different from $TTD.
Site Centers' $3 per-share return-of-capital distribution and December delisting leave a discounted liquidation stub, with two properties…

David Orr describes running Militia Capital’s roughly 500-stock long-short portfolio, using expected value, correlation and factor…
AXT reported record Q3 revenue as AI data-center demand for indium phosphide drives supply agreements and capacity expansion.
 Alan Sumler 1 click
Namib Minerals accelerates Redwing’s restart, targeting first gold this month and a ramp from 338 ounces monthly to 835 ounces by Q2 2027.
Educational Development trades at 0.21x tangible book after selling its distribution complex to repay debt, but FY26's $2.3m profit masked…
Stevanato fell 30% after forecasting low-single-digit 2027 growth as lower Nexa syringe volumes from a GLP-1 customer offset solid Q3…
Transocean enters its Valaris merger with 109 of 110 available deepwater rigs contracted and 313 million shares sold short, despite weaker…
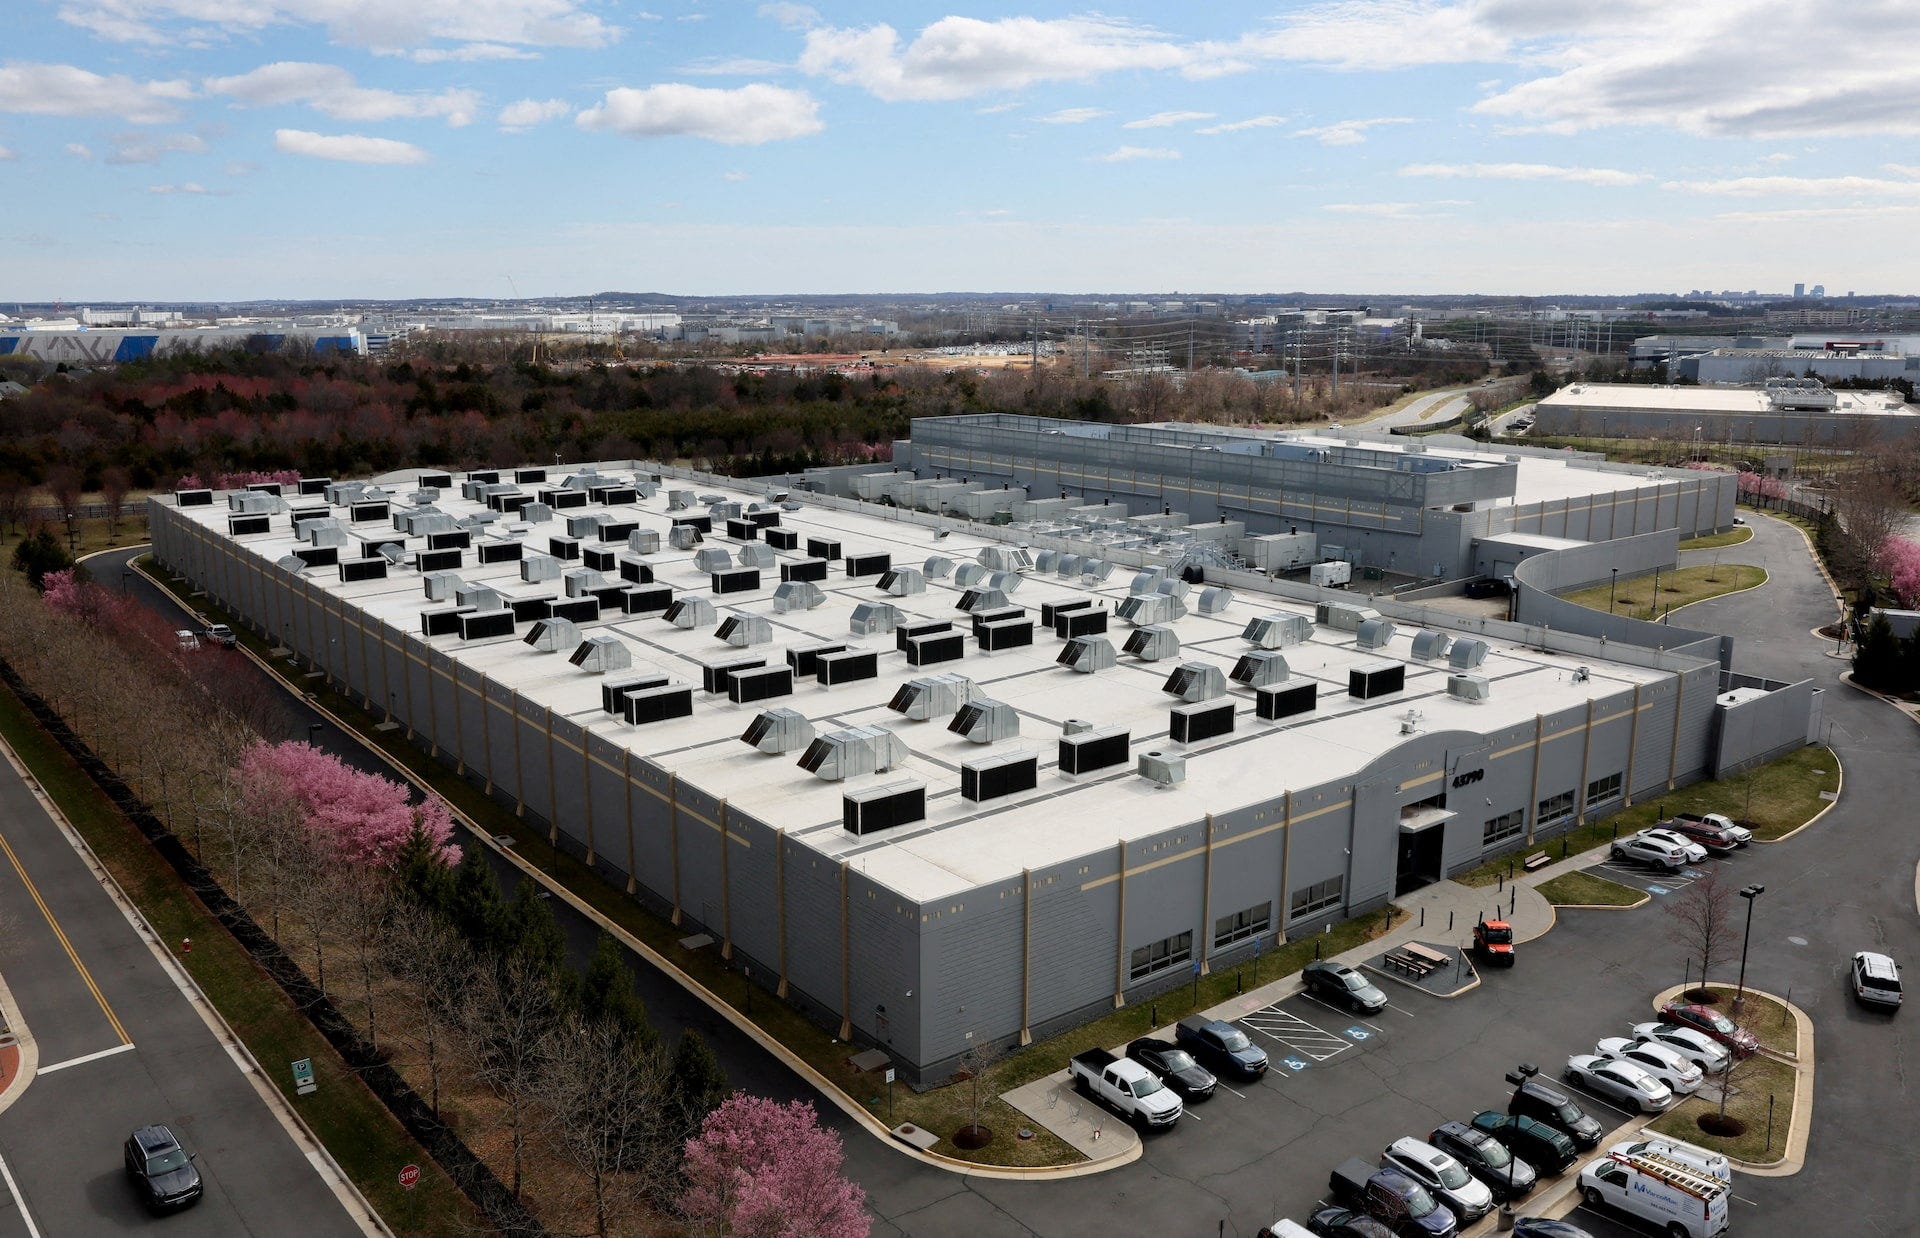
BXDC trades at a 14% discount to net liquidation value, with $1.9 billion of cash against a $1.6 billion market cap, ahead of data-center…
Essential Properties Realty Trust is growing faster than Realty Income through acquisition opportunities while trading at a cheaper…
 Jussi Askola, CFA
Capital Employed rounds up 48 stock pitches, led by Greystone’s $14.50 target for organ-transplant logistics firm Strata Critical Medical,…
 PESI · long
Perma-Fix Environmental Services (PESI) is presented as a long investment idea.
VYX executive chair James Kelly replaces David Wilkinson as CEO.

China Yuchai (CYD) trades at 2x EBITDA and 0.3x book as data-center backup-power demand, buybacks, and net cash support an earnings…

Wendy’s $1 annual dividend yields 6.8%, supported by positive same-store sales and unit growth but constrained by $2.75 billion of debt and…
Playtika's governance is so poor it may create a contrarian opportunity.

UGI's AmeriGas EBITDA fell from $584 million in 2019 to $320 million in 2024, masking growth at its gas utility and midstream divisions.
OTC Markets has lost many profitable small companies to buyouts, privatizations and SEC Rule 15c2-11.

Tecogen ($TGEN) sells gas-or-electric chillers that management says cut data-center cooling costs 30–40%, with factory utilization offering…
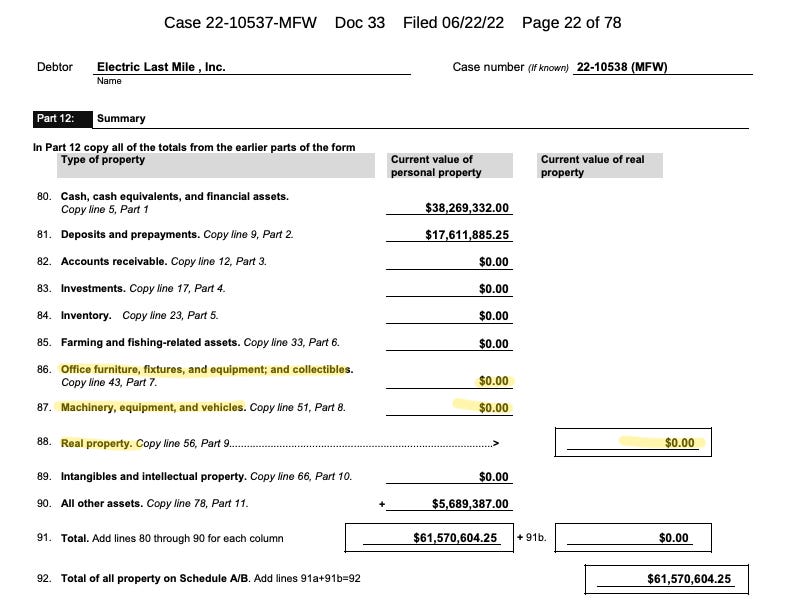
Electric Last Mile Solutions sold assets for $104.6 million after its $5 million OTC market cap reflected a Chapter 7 liquidation and…
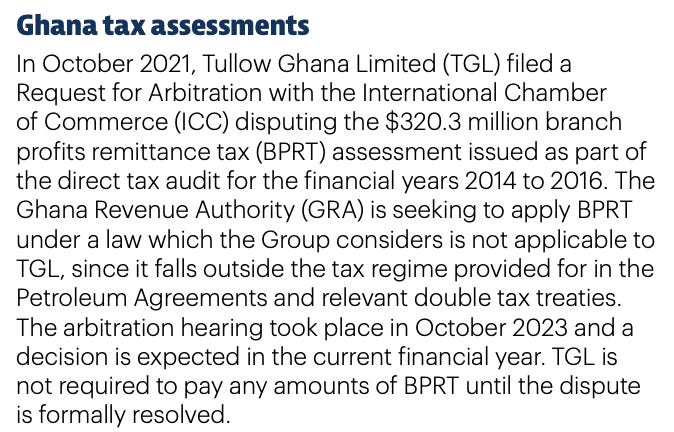
Tullow Oil faces falling Ghana production, heavy debt and tax-arbitration risk as Kosmos weighs a possible acquisition structure.
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Cypriot Invests
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.