Stevanato down 30%. Yikes.
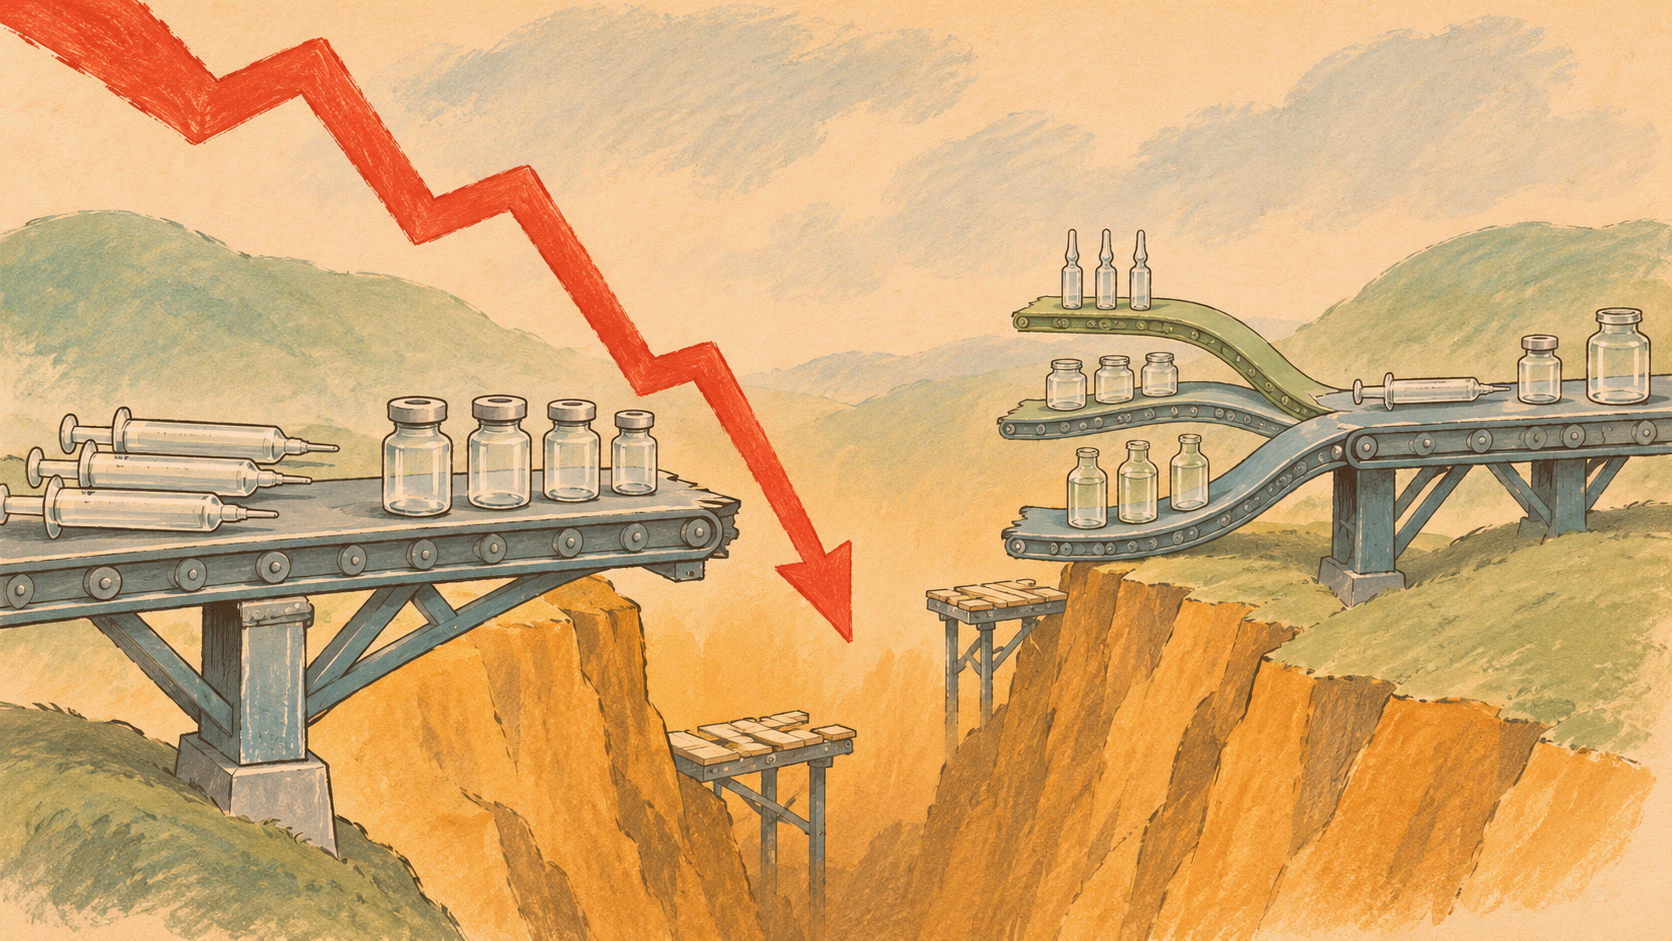
Stevanato fell 30% after forecasting low-single-digit 2027 growth as lower Nexa syringe volumes from a GLP-1 customer offset solid Q3 margins and non-GLP biologics demand.
Stevanato fell 30% after forecasting low-single-digit 2027 growth as lower Nexa syringe volumes from a GLP-1 customer offset solid Q3 margins and non-GLP biologics demand.
I reckon a portfolio of short $WMT, $KO (safety trade), $TSLA, $SPCX, $DJT, $UMAC, $GEO (Trump trade) long $SPY probably beats most things over the next 3 months.
Sometimes it’s hard to keep track of all the companies we cover. Our new MCP-server allows you to access our full 6 years of history, directly connected to your favorite LLM. What did we write about Marex $MRX in the past? Ask Claude! https://t.co/UvpURXmY6X
@DeItaone $KYIV?
Watch prison companies like $GEO and coal names like $BTU. If dems sweep these probably fall and become buying opportunities. https://t.co/I7dgUErhh7
@IkaKnight_ Yeah H1 2026 was more fun, everyone now is depressed and bearish… So recoveries like $NBIS and $CIFR give everyone PTSD. I’m hoping this is the fabled midterm election rally and not another selloff https://t.co/9HWkUkMQjg
Calumet and other refiners sold off alongside AI names, but the RIN thesis for renewable fuel earnings remains unchanged ahead of Q3…
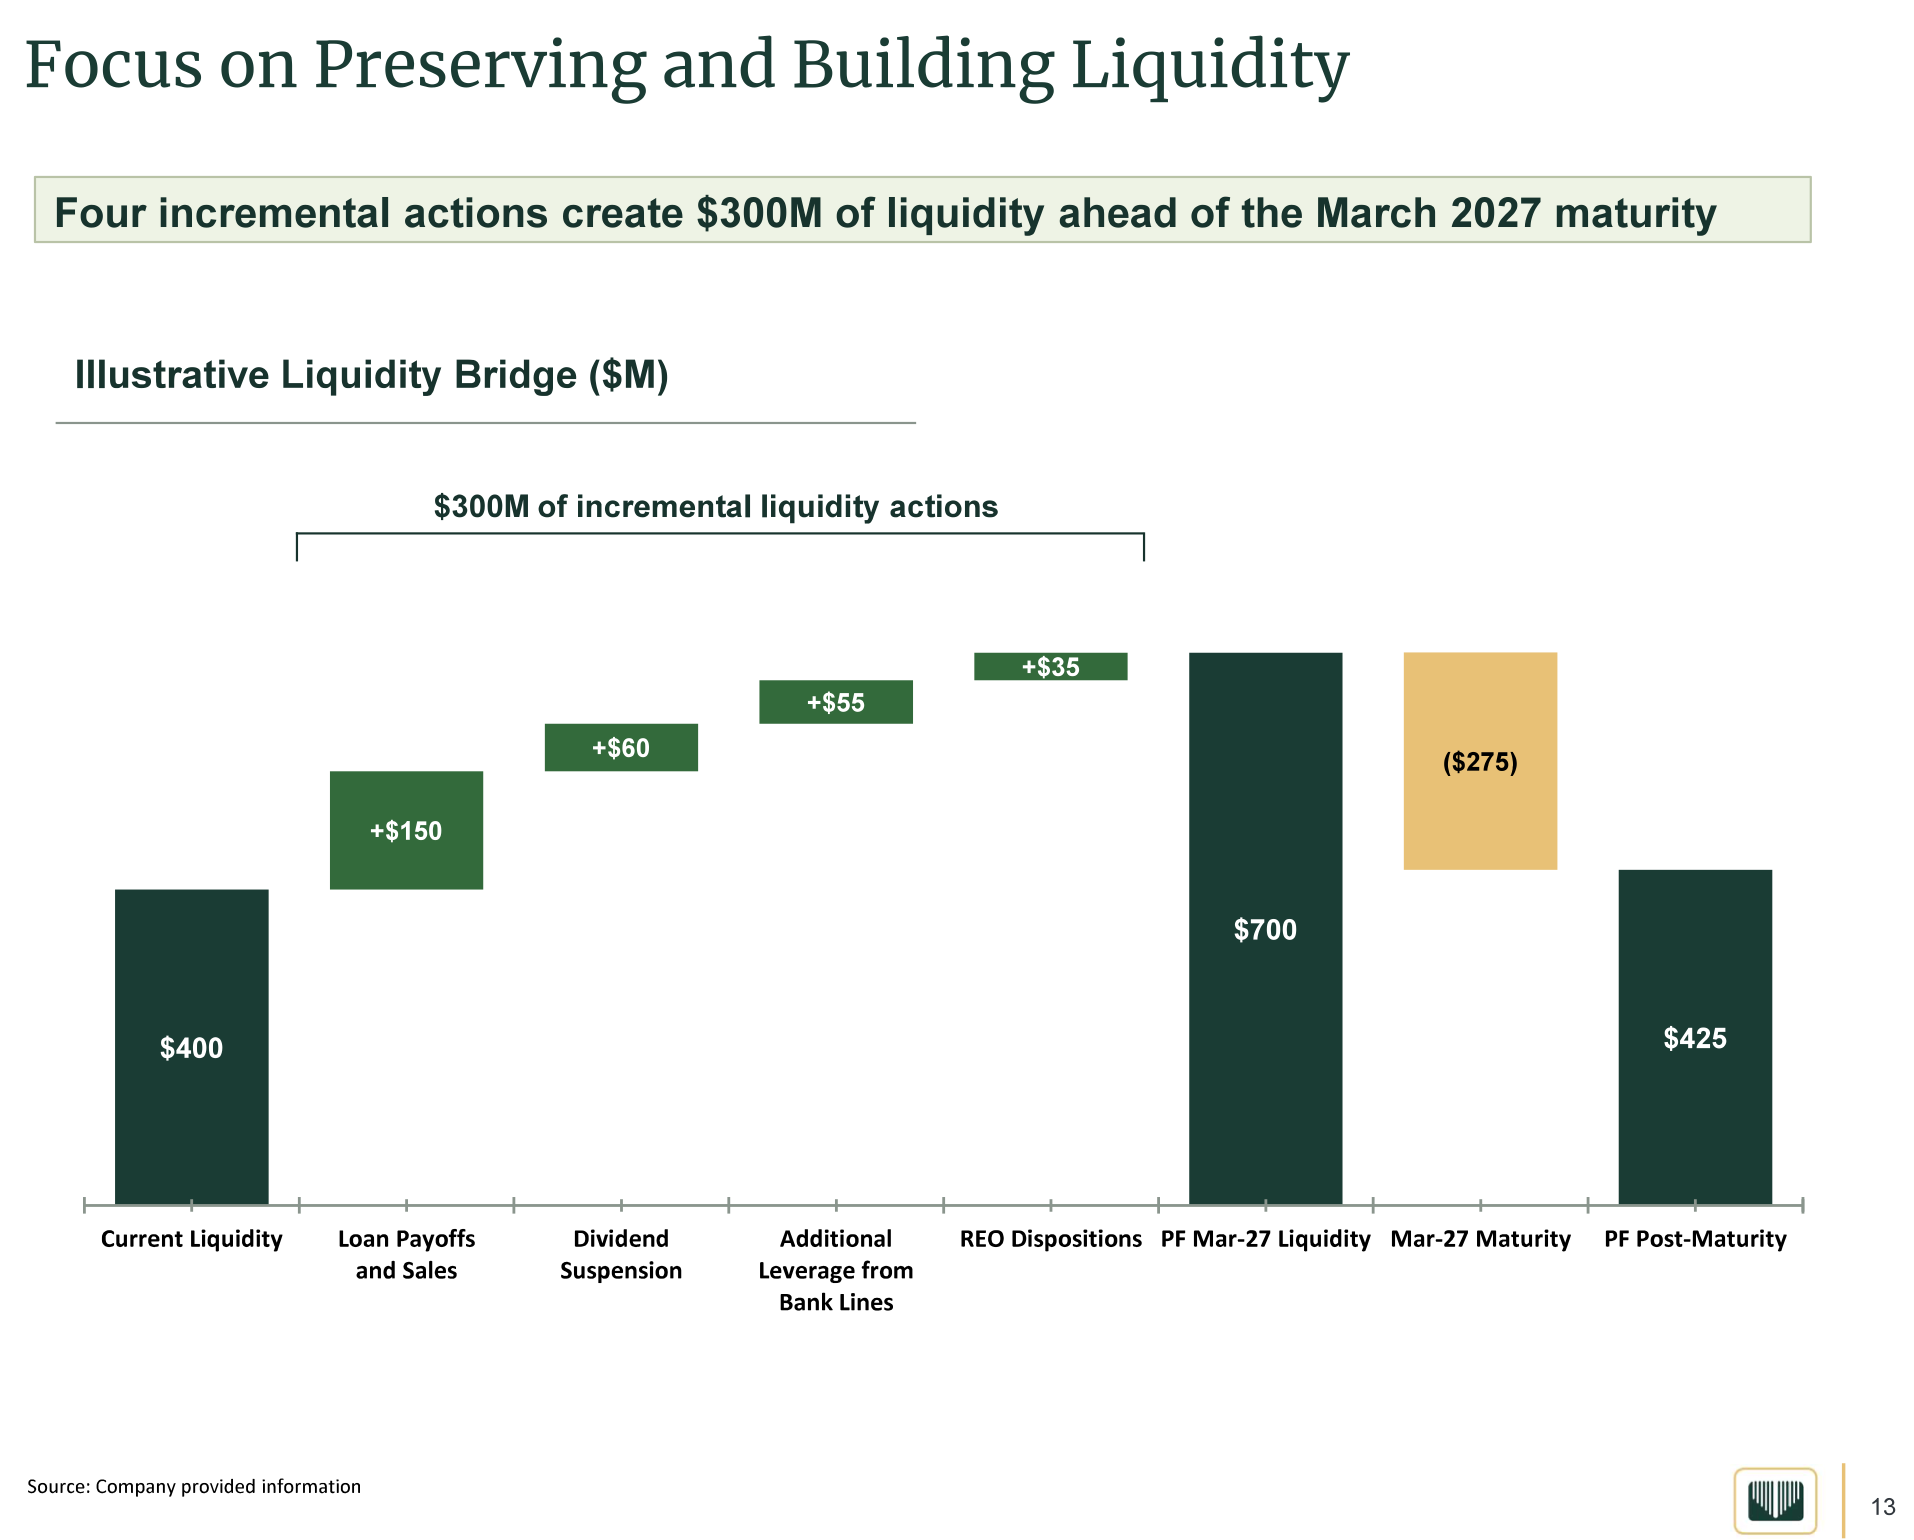
Arbor Realty Trust’s dividend suspension is presented as creating $60 million of liquidity, raising questions about its ability to meet…
Life360 has fallen 60% despite 40% revenue growth, 100 million monthly users and profitability, as its family-safety subscriptions and…

Markel spent $315 million repurchasing shares in Q3 as Thrive agreed to buy ADT for $7.6 billion and Hasbro cited rising adult toy demand.
Tango Therapeutics reported an 82% response rate and 88% nine-month PFS for vopimetostat plus RASONQUE in RAS-mutant pancreatic cancer,…
 Terry Chrisomalis 2 clicks
Mattel, Winnebago and PayPal lead 37 special situations spanning activist campaigns, buybacks, M&A and strategic alternatives.
Kratos posted Q2 FY2026 revenue growth of 30.5% to $458.8 million as unmanned systems, propulsion and defense-electronics production ramps…
 Arizona Equity Research
Group 1 Automotive trades at 5.5 times earnings as aging gasoline vehicles and EV repairs sustain service profits; insiders bought while…
Alexandria Real Estate (ARE) faces lease expirations and occupancy pressure through 2028, but leasing momentum supports a projected…
 Luuk Wierenga
Enova’s Q3 2026 revenue exceeded $1 billion as originations rose 31%, while its failed Grasshopper Bank bid drove a 23% one-day stock…
 GNCGF · long
Greencore is the UK’s leading fresh prepared food producer, pitched as undervalued with potential to nearly double within 12–24 months.
Micron’s customer agreements, Analog Devices’ acquisitions, Ondas’ GATE deal and Baker Hughes’ power systems position them for AI…
ZIM faces Israeli review of Hapag-Lloyd’s $35-per-share bid, with $2.46 billion cash and elevated transpacific rates supporting potential…
 Melissa Tucker

Shift4 trades at 6.5x EBITDA despite 11% reported organic growth, with Shift4 Dine equipment leases cited as evidence of net-new merchant…
Texas Instruments, ON Semiconductor and Vishay are rated Accumulate on rising robotics demand for analog, power and discrete chips after a…
Firefly Aerospace grew backlog to $1.5 billion, won two 2028 lunar missions and acquired Space-ng for autonomous navigation across its Blue…
Cellebrite converts more than 110% of EBITDA into free cash flow and trades at 12.5 times free cash flow, with management targeting 15% or…
Undercovered Dozen spotlights 12 lesser-covered stocks, including Rithm Capital, Sterling Infrastructure and Corning.
 The Undercovered Dozen
Shift4 trades at 6.5 times EBITDA despite 11% organic growth, with Shift4 Dine equipment leases reaching a $400 million run rate as…
Corteva will spin off its Pioneer seed business, Vylor, on October 1, leaving crop protection RemainCo that could trade at 6.5-8.5x 2026…
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Andres Veurink Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.