TWLO Q3 FY12/26 Earnings Review
Twilio's Q3 revenue rose 20% to $1.56 billion, but Q4 organic growth guidance fell to 11% to 12% and RPO declined 28%.
Twilio's Q3 revenue rose 20% to $1.56 billion, but Q4 organic growth guidance fell to 11% to 12% and RPO declined 28%.
$AVO calling out the fact that they have been overearning and margins reverting. “experienced normalization of our per unit avocado margins during in Q1.” Noted weak harvest anticipated in Mexcico. $CVGW will be even more adversely impacted by these factors.
BTW, his stock trades for 10x, posts an ROE of 17% while running with excess capital, and is part of a banking oligopoly in Puerto Rico. $OFG
$DAKT CEO departing, new high-quality CFO (temp) w very attractive secular tailwinds in digital display demand + activist involvement = increased likelihood of takeout. Optimal business for PE. Multiple logical strategics. +75% upside.
$FTDR Vol declining (existing home sales=driver). Pricing lagging inflation, massively over-earning. Problematic given 25% churn w aggressive new entrants. Dubious company overall. Investor day yesterday was comical, compared themselves to $NFLX. Earnings misses coming.
$AVO $CVGW 1) Retailers $CMG, etc sourcing elsewhere given MX tariff risk. 2) Avocado price spike during last year’s peak harvest season enabled distributors to realize outsized margins. 1-time benefit has reversed, significant earnings misses ahead for these commodity businesses
$NX Outlandishly guiding to flat 2025 sales, customers and channel -DD. Commodity window and door components facing pricing pressure from larger customers ($JELD, $OC). Now levered 4x, trading at a premium to higher value-add building products peers. Guide cut inevitable.
Marvell and Lumentum’s merger targets uVCSEL scale-in optics, combining Marvell’s DSP and analog IP with Lumentum’s laser manufacturing for…
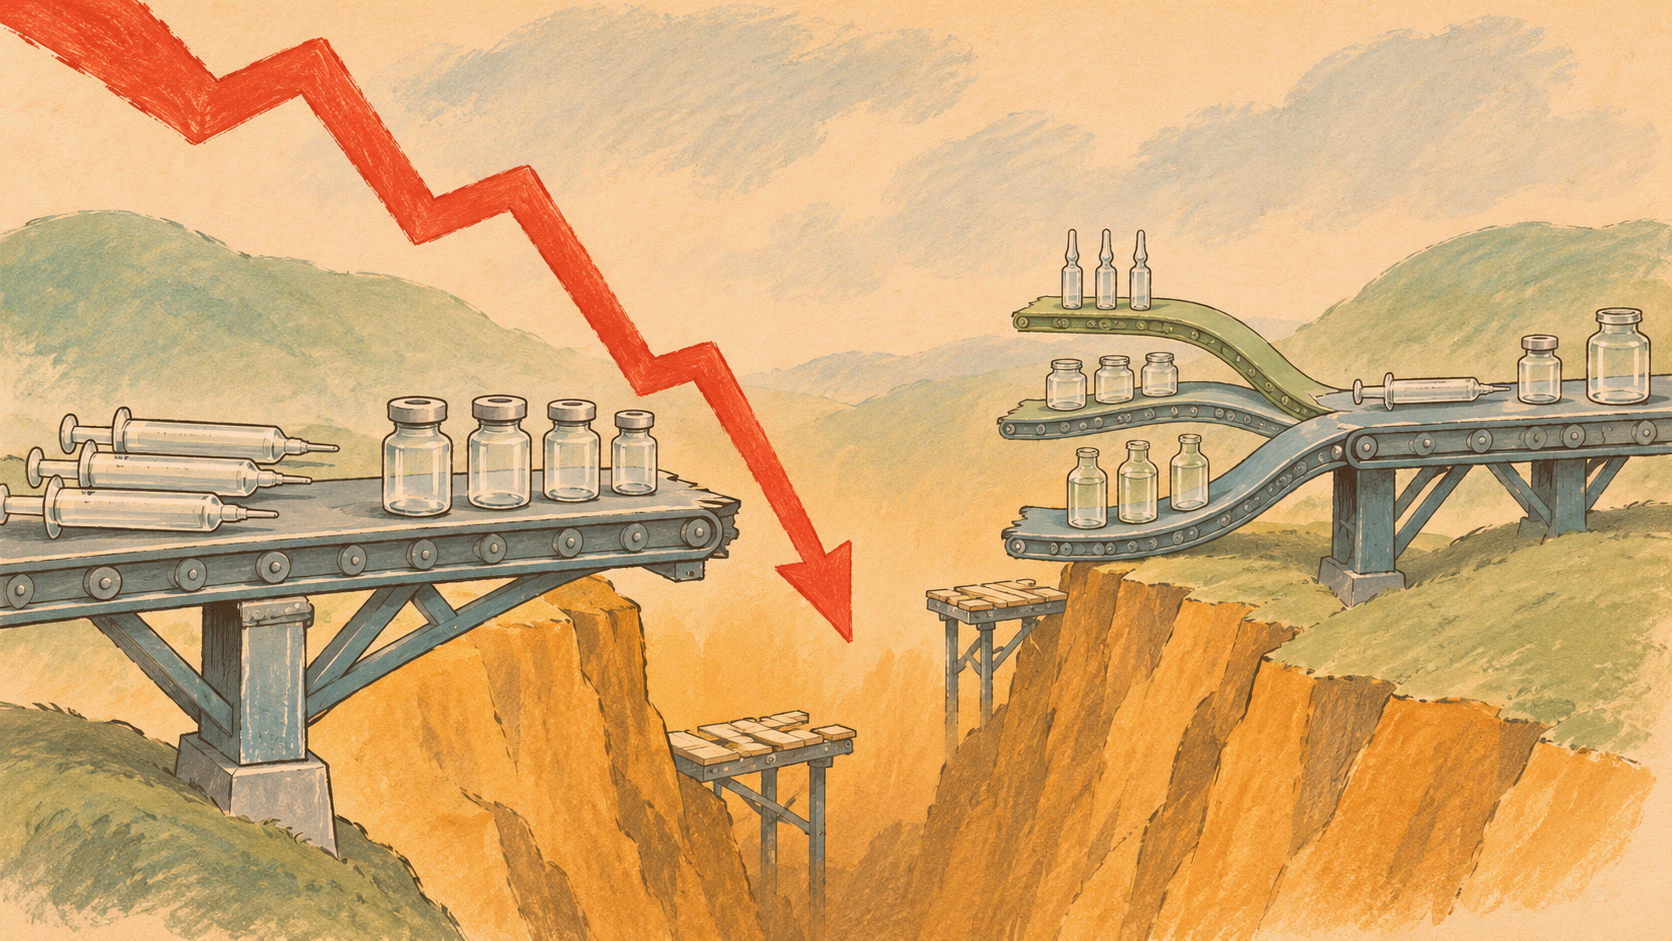
Stevanato fell 30% after forecasting low-single-digit 2027 growth as lower Nexa syringe volumes from a GLP-1 customer offset solid Q3…
Transocean enters its Valaris merger with 109 of 110 available deepwater rigs contracted and 313 million shares sold short, despite weaker…
BXDC trades at a 14% discount to net liquidation value, with $1.9 billion of cash against a $1.6 billion market cap, ahead of data-center…
Veeva Systems' Commercial Solutions returned to 13% subscription growth, while R&D and Quality grew 19.3%, with Falcon AI agents and…
 Ignacio Planas Gonzalez
Marvell’s proposed Lumentum deal risks alienating Cloudlight customers and losing engineering talent, despite limited optical integration…
ARS Pharmaceuticals’ neffy adoption and insurance hurdles have driven cash burn and a falling share price, while management targets…
 Cypriot Invests
Marvell Technology and Lumentum fell sharply after announcing a historic merger, reviving comparisons with JDS-Uniphase.
FTAI Aviation’s $234 million Jereh JV deposit funds Power inventory, while customer concentration, lower cash guidance and pending U.S.
Grab’s Southeast Asian delivery business nears a profitability inflection point, while consolidation and a potential GoTo deal challenge…
 Wavelength Research 2 clicks
BioMarin's Q3 revenue rose 32% to $1.02 billion after the Amicus acquisition, while Alesta charges drove an $82 million operating loss and…
BioNTech's Q3 revenue beat consensus on €613 million of BMS partnership revenue, while COVID vaccine sales fell 35% and net cash totaled…
Onsemi's Q3 revenue rose 11% to $1.72 billion, driven by 175% AI data-center growth, while automotive revenue fell 1% and net debt dropped…
Marvell’s all-stock Lumentum deal exposes LITE holders to MRVL volatility while paying peak-cycle AI multiples, with US and China antitrust…
 Dustin Quasney 2 clicks
 BSP · short
Bending Spoons is a software and digital-assets holding company that has completed more than 50 acquisitions since 2013.
Nebius faces refinancing and dilution risks from short-term borrowing and heavy GPU infrastructure spending despite higher rental prices…
 Hunting Alphas 2 clicks
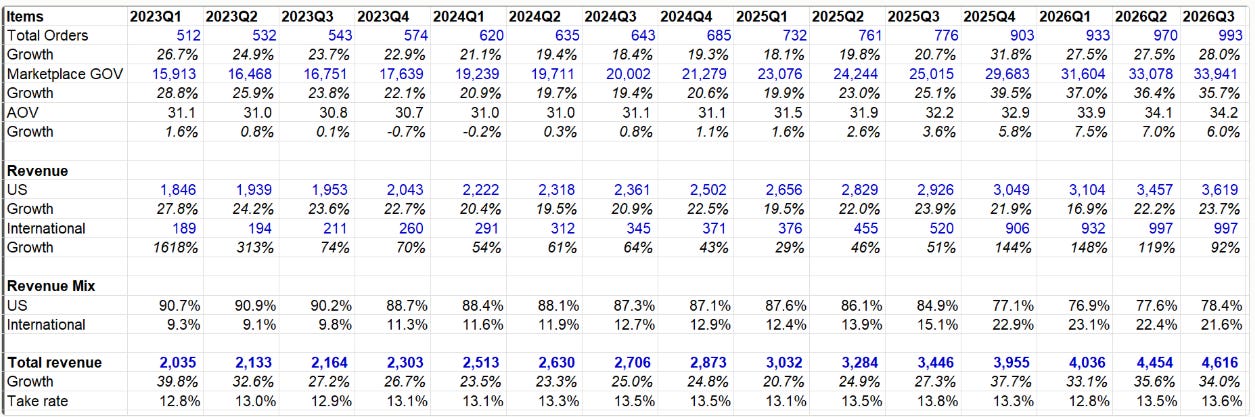
DoorDash’s 3Q orders rose 28% as it announced a $17 billion Instacart acquisition, expanding its grocery basket strategy after buying…
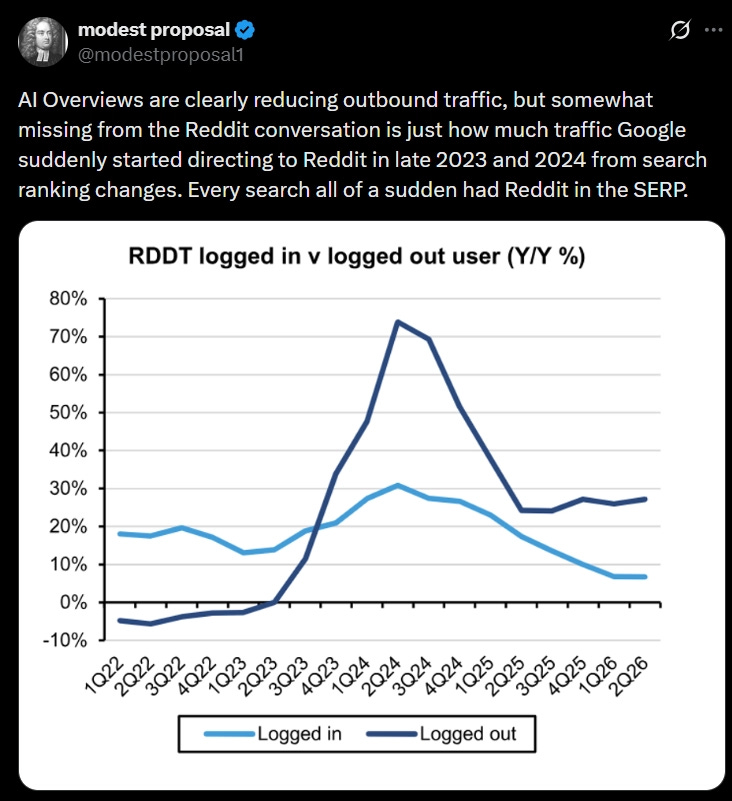
Reddit’s Google referrals fell by more than 1 million a week as AI search expands, prompting a logged-in-user push to protect ad yield and…
Iron Mountain’s upgraded Q2 guidance, revenue, EBITDA and AFFO trends support its outlook before Nov.
 Albert Anthony 3 clicks
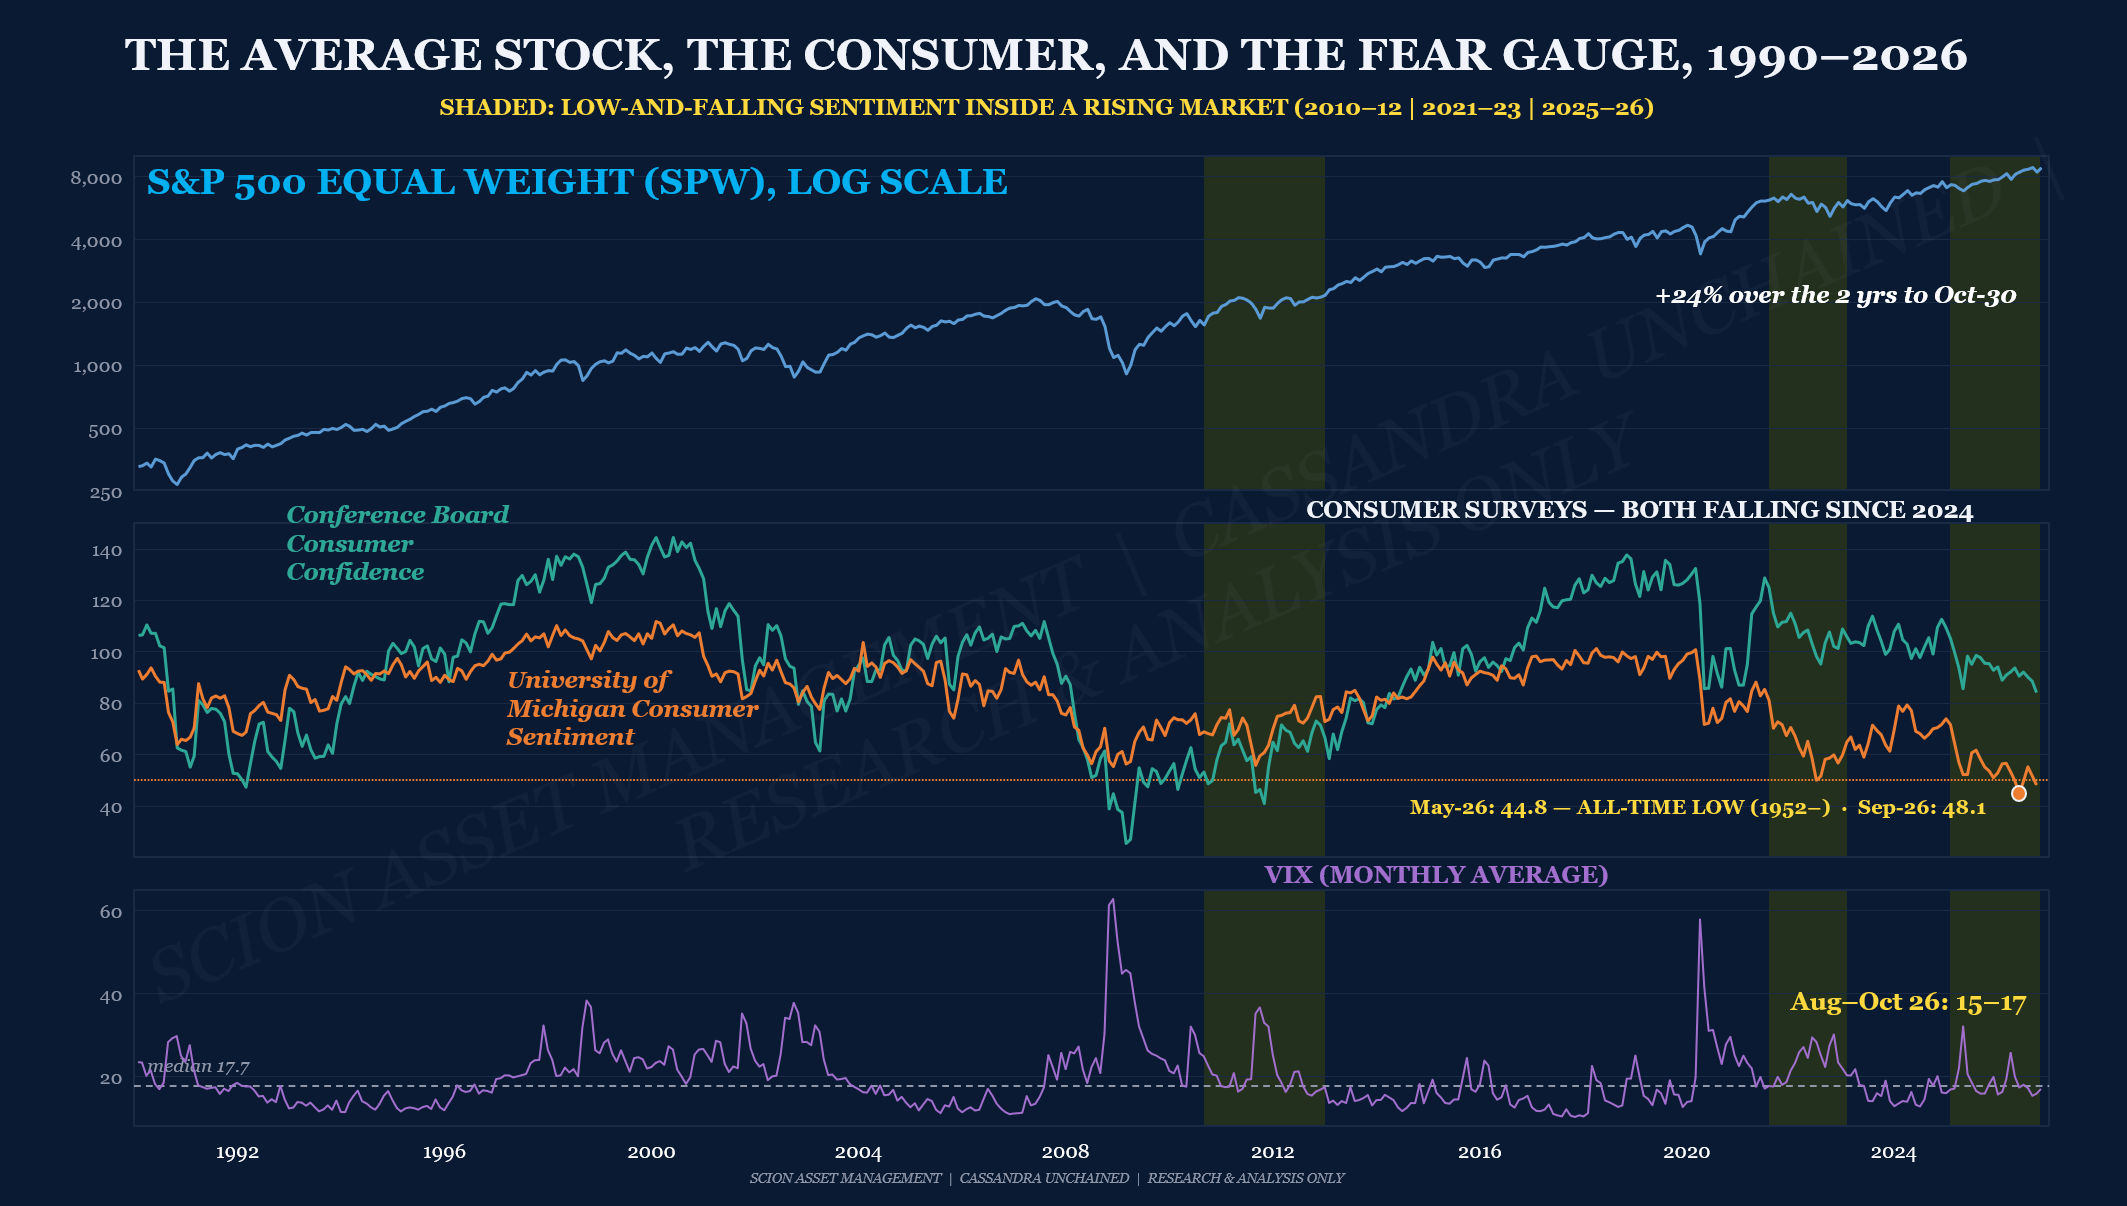
Global Payments rose 18% on a reported CD&R and GTCR take-private bid, while estimated control value is $45-$60 versus a $96.84 share price.
Every publication on this site, hand-picked.
 Adam Schadt Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur Cypriot Invests
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.