EQT Q3 FY12/26 Earnings Review - Distribute Rating
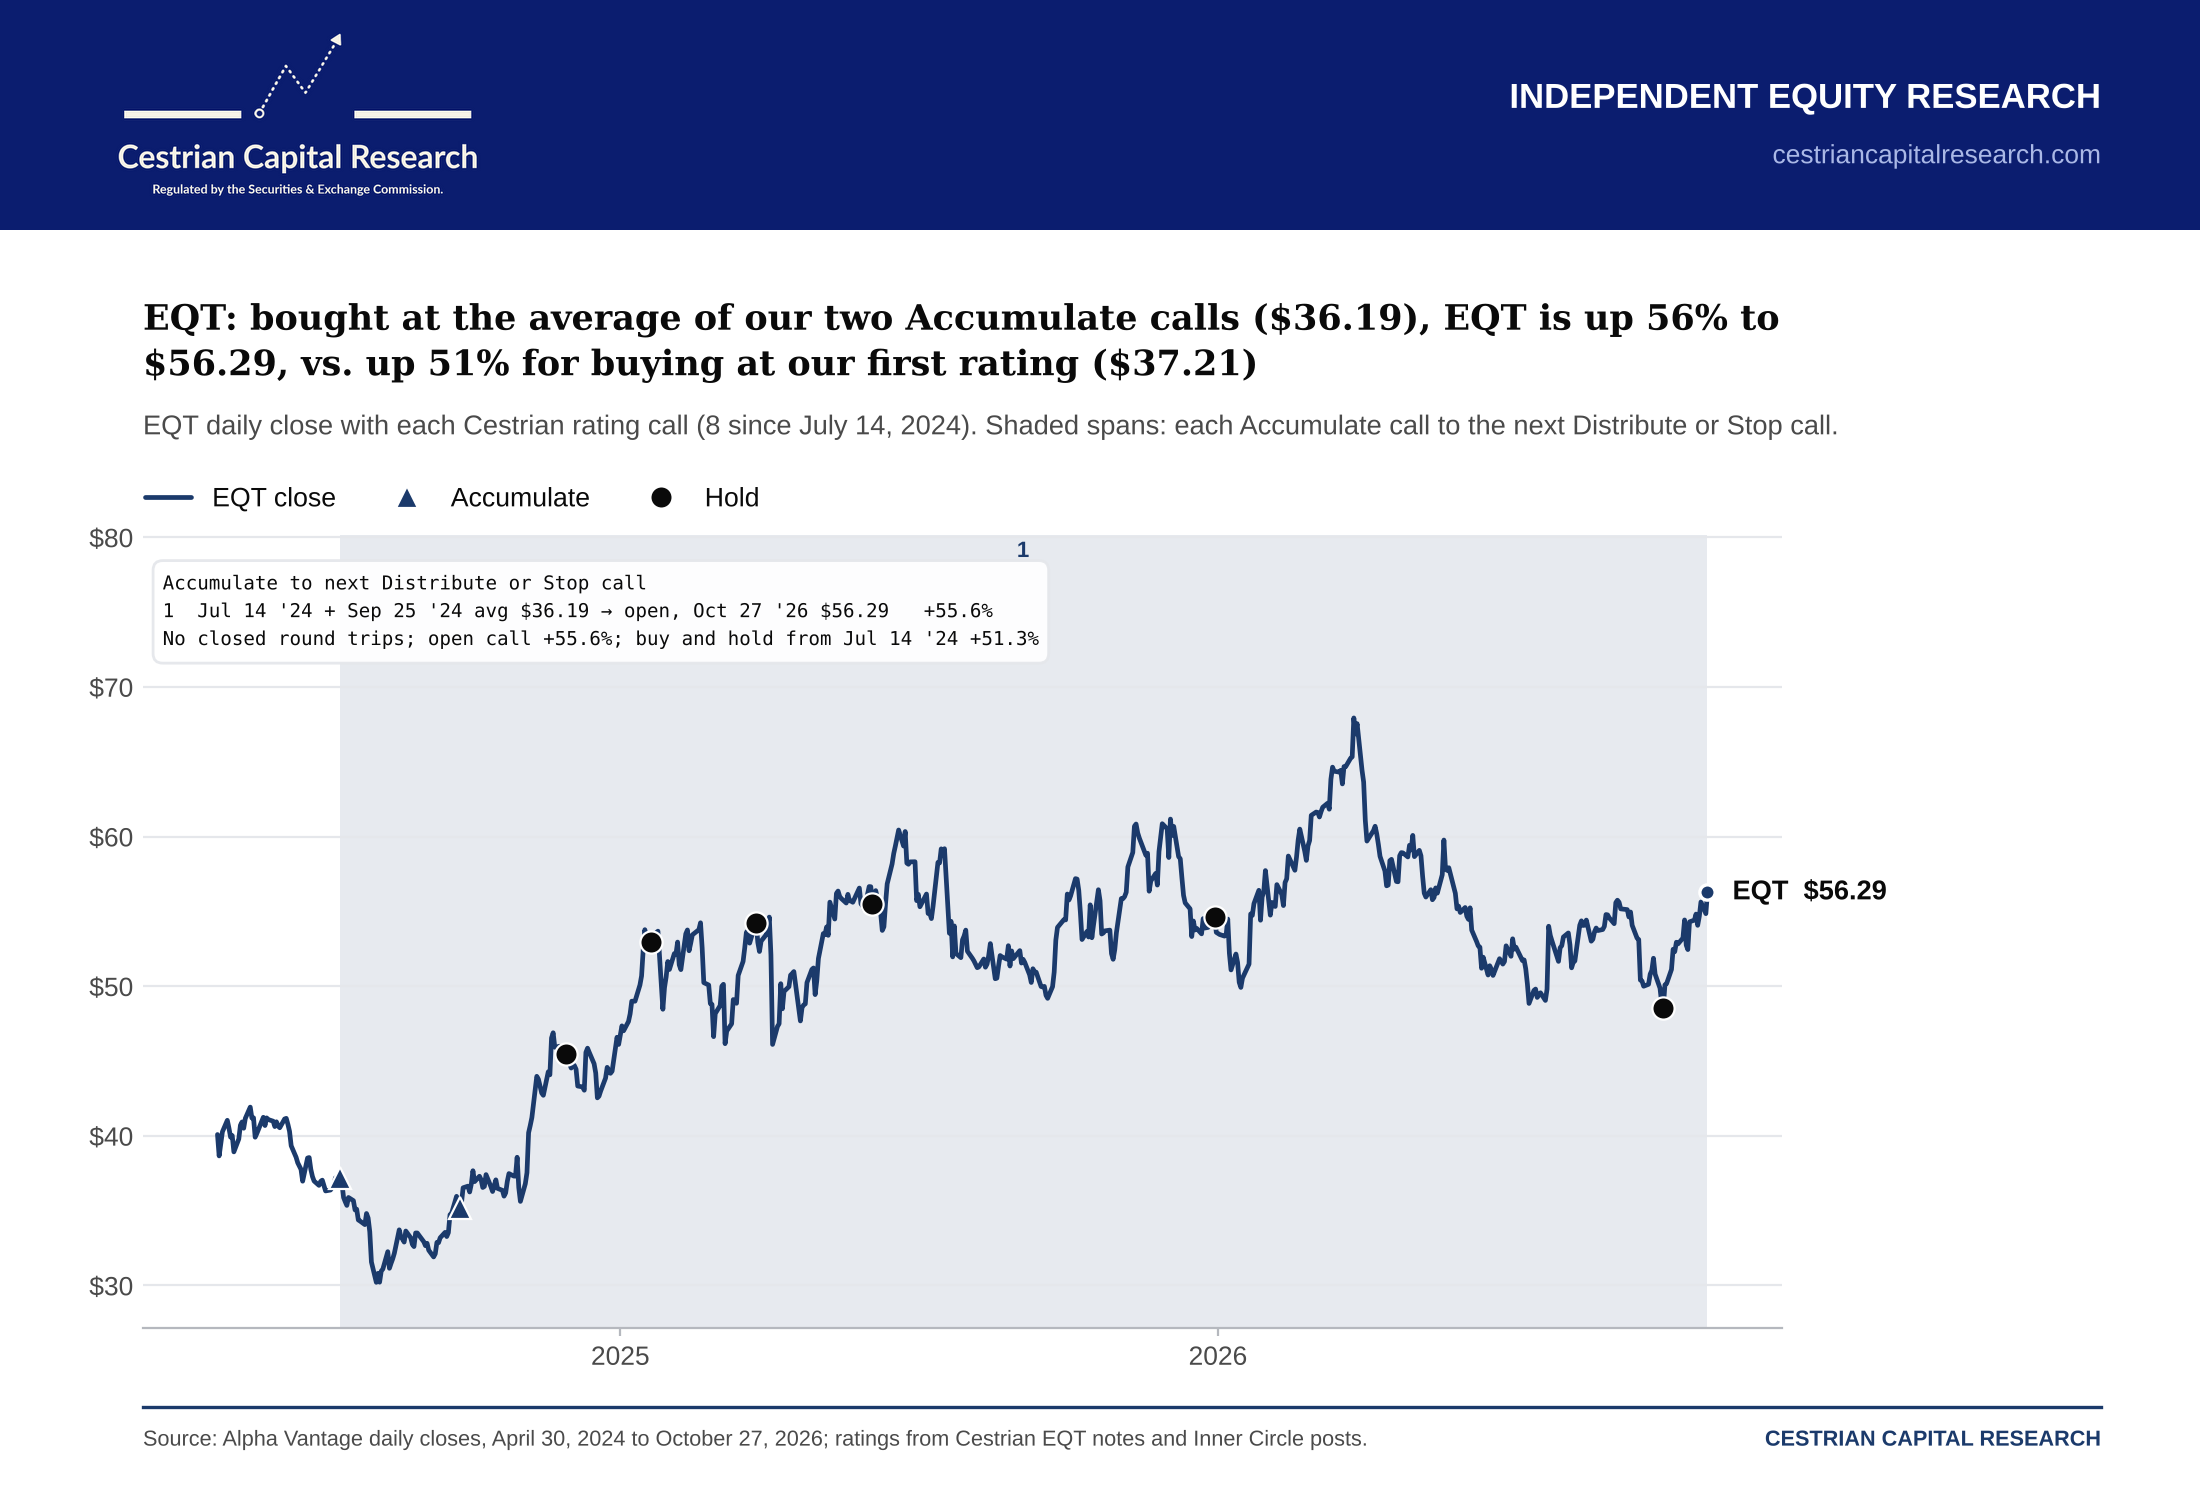
EQT moved to Distribute at $56.29 after Q3 revenue fell 9.6%; a 44% trailing free-cash-flow margin signals cycle risk despite lower debt and an EPS beat.
EQT moved to Distribute at $56.29 after Q3 revenue fell 9.6%; a 44% trailing free-cash-flow margin signals cycle risk despite lower debt and an EPS beat.
Newest out. Philip Morris International: Centered "Q1'26 note" $PM $BTI $MO $IMBBY $HAYPP $STG https://t.co/QWIjmx81rA
I just published my Earnings Update about the Q1 2026 of Evolution $EVO $EVVTY. You can find it in the Portfolio section of the blog :) https://t.co/QXlBS93lji
Excelsior Cap $ECL is a good example of why I like small and micro-cap liquidations stocks. The good ones look like this. Big step-change moves and otherwise stable. https://t.co/CrSEoHnShP
Newest out. Imperial Brands: An Ode to Zero "April Trading Update note" $IMBBY $LOG $PM $BTI $MO $STG $HAYPP https://t.co/RkLxSWZa64
@ACapitalLP You forgot to mention $IWM / r1k index inclusion plus tsx60 bc of float cap... $gfl
how is this not the end for $wix and $gddy? https://t.co/nY1p4vAMfN
AST SpaceMobile targets intermittent US satellite service by end-2026 as New Glenn progress could speed constellation launches after…
 Melissa Tucker 1 click
Neoclouds face tighter debt financing as AI infrastructure capex outruns cash flow, leaving cash-burning GPU providers more exposed than…
Reddit generated $805 million in Q2 2026 revenue, 95% from ads, but slowing Google search referrals expose AI-driven traffic and…
GameStop’s $6.1 billion in net cash equivalents and shift toward collectibles underpin a $30 to $40 per-share valuation thesis.
Monte Investments updates Carpenter Technology after a 25% sell-off, tracks EQT’s $12.83 billion Range Resources acquisition and assesses…
Cadence Design Systems grew Q3 revenue 22% to $1.633 billion, built an $8.2 billion backlog and raised its 2026 revenue growth outlook to…
Blackstone’s Q3 brought $1.37 trillion in AUM and $63.3 billion of inflows, with other businesses offsetting real estate weakness as…
 Timur Mekhantev 2 clicks
EQT’s $50 billion merger with Range Resources and Ovintiv’s $1.26 billion acquisition of Logan Energy reshape North American oil and gas…
Celestica rose 12% after beating revenue and profit expectations and raising its full-year outlook, as AI chip demand supports contract…
Amkor's Q3 sales were flat at $1.991 billion as computing and automotive/industrial growth offset a 27% communications decline; Q4 sales…
 SBAC · long
SBA Communications trades at 14.9x forward AFFOPS, near a record low, despite being pitched as the market’s cleanest tower operator.
Truist Financial trades at 10.5x earnings and 1.5x tangible book as new CEO Mike Lyons sells non-core assets and targets 16% to 18% ROTCE.
Molina Healthcare and Kinsale Capital’s earnings are reassessed through a long-term lens, emphasizing conviction and detachment during…
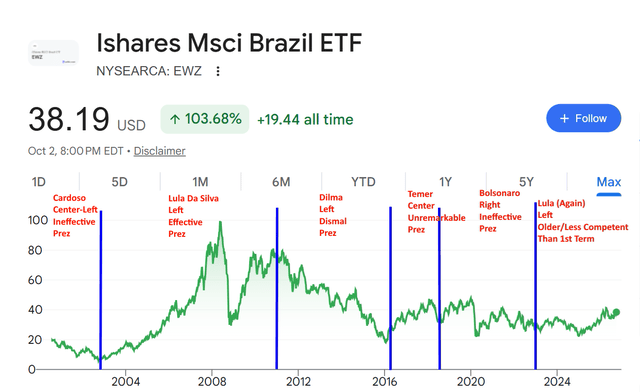
Brazil’s Lula victory leaves Nu and Inter’s thesis intact, while JetBlue heads toward bankruptcy and Mexican airlines pursue a merger.
Tower Semiconductor’s low-loss photonics chips halve lasers in 1.6T optical modules, supporting a $680 million annualized photonics run…
Super Micro’s 2026 xAI rack orders, GB300 price increases and B300 mix frame its gross-margin outlook.
Ares Capital’s 10%+ yield is supported by a $30.5 billion portfolio with over 70% floating-rate debt, though dividend coverage remains…
 Jonathan Weber 6 clicks
Petrobras’s Morpho-1 well revived hopes that Brazil’s Equatorial Margin can become a major new oil frontier after hydrocarbons were…
CoreWeave’s rising debt yields and fading confidence in AI data-center economics frame a weekly review of Meta, Tesla, SpaceX, Netflix,…
CoreWeave's financial statements point to a business model familiar to the authors after a closer review of the AI infrastructure company.
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Cypriot Invests
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.